

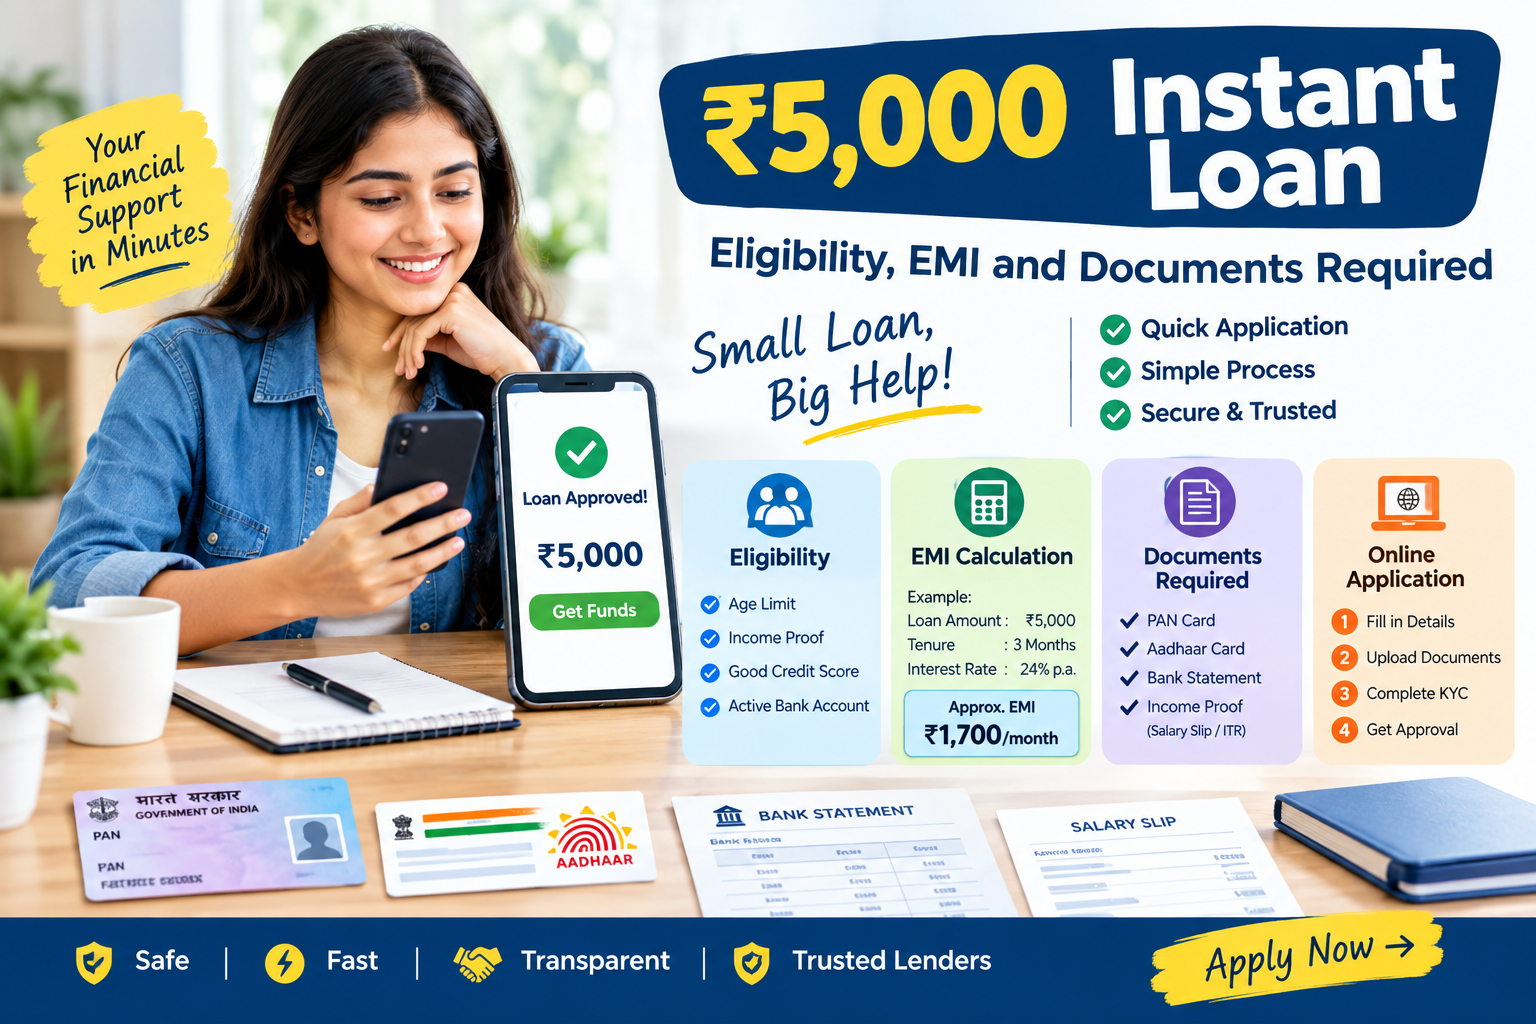
A ₹5,000 instant loan can help cover a small emergency, medical expense, bill, travel need or temporary cash shortage. Several lenders and digital lending platforms offer small personal loans online, but approval depends on the applicant's profile and the lender's eligibility rules.
Even for a small loan, borrowers should check the interest rate, EMI, processing fee, total repayment amount and lender details before accepting the offer.
What Is a ₹5,000 Instant Loan?
A ₹5,000 instant loan is generally a small-ticket personal loan that can be applied for online. Depending on the lender, the process may include digital KYC, credit assessment, bank-account verification and electronic signing.
Some platforms advertise loan amounts starting at ₹5,000, while others offer higher limits with ₹5,000 as the minimum amount.
Important: “Instant” refers to the application or processing speed. It does not mean guaranteed approval.
₹5,000 Loan Eligibility
Eligibility varies between lenders, but common factors include:
- Indian residency or citizenship, where required
- Meeting the lender's minimum age requirement
- Valid PAN and KYC information
- Active bank account
- Regular income or adequate cash flow
- Acceptable credit profile
- Manageable existing EMI obligations
- Successful identity and bank verification
For example, published lender criteria can differ considerably: some lenders specify minimum income or credit-score requirements, while others assess applicants using broader credit and financial information.
Does Credit Score Matter?
Yes. Lenders may consider your credit history, previous repayment behaviour, existing debt and recent credit enquiries.
A good credit profile can support eligibility, but no particular credit score guarantees approval.
Documents Required for a ₹5,000 Loan
The exact documents depend on the lender and borrower profile.
Common requirements may include:
| Document | Purpose |
|---|---|
| PAN Card | Identity and financial verification |
| Aadhaar/other KYC | Identity or address verification |
| Bank Statement | Income and repayment-capacity assessment |
| Salary Slip | Income verification for salaried applicants |
| ITR/financial records | May be required for self-employed borrowers |
| Selfie/e-KYC | Digital identity verification |
Some digital lenders may use electronic KYC and require fewer physical documents. CIBIL notes that document requirements vary by lender and may include identity, address, bank statements and income documents.
₹5,000 Loan EMI Calculation
Your EMI depends on the interest rate and repayment tenure.
For example, if a ₹5,000 loan is taken for 3 months at 24% annual interest, the approximate EMI would be ₹1,700 per month, before considering applicable fees.
A shorter tenure can mean higher monthly payments but may reduce the overall interest cost. Always check the lender's actual repayment schedule rather than relying only on an online estimate.
What Charges Should You Check?
Before accepting a ₹5,000 loan, look for:
- Interest rate
- APR or overall borrowing cost
- Processing fee
- GST and applicable charges
- Late-payment charges
- Prepayment/foreclosure conditions
- Total amount payable
- EMI due date
A small loan can become expensive if fees and interest are high compared with the amount borrowed.
How to Apply Safely
Step 1: Verify the Lender
Find out which bank or NBFC is actually providing the loan.
Step 2: Check Eligibility
Review age, income, credit and KYC requirements.
Step 3: Compare the Total Cost
Don't select a loan only because the advertised amount is available quickly.
Step 4: Complete KYC
Provide only the information and permissions required for the legitimate lending process.
Step 5: Read the Loan Terms
Check the repayment schedule, fees, interest rate and other charges before accepting.
Step 6: Confirm the Disbursal
Approved funds should be credited through the lender's stated process.
Beware of Fake Instant Loan Apps
Borrowers should be cautious about apps promising guaranteed loans, zero checks or instant cash without verification.
Red flags include:
- Requests for unnecessary phone permissions
- Unclear lender identity
- No proper loan agreement
- Hidden charges
- Pressure to pay money before loan processing
- Requests to transfer repayments to personal accounts
- No clear grievance or customer-support information
₹5,000 Instant Loan: Key Takeaways
- A ₹5,000 loan may be available through banks, NBFCs and digital lending platforms.
- Eligibility differs between lenders.
- PAN, KYC and bank information are commonly requested.
- Salaried borrowers may need salary/income documents; self-employed borrowers may need ITRs or other financial records.
- EMI depends on interest rate and tenure.
- Instant approval is not guaranteed approval.
- Always check the lender, fees, APR, repayment amount and loan agreement.
FAQs
Can I get a ₹5,000 loan online?
Some lenders and digital platforms offer personal loans starting at ₹5,000, subject to their eligibility and verification process.
What documents are needed for a ₹5,000 loan?
Depending on the lender, you may need PAN, Aadhaar or another KYC document, bank details and income-related documents.
Can I get ₹5,000 without salary slips?
Some lenders may accept alternative income or banking information, but this depends on their assessment and documentation requirements.
Does a ₹5,000 loan require collateral?
Small personal loans are generally unsecured, meaning collateral is usually not required. However, the exact product terms depend on the lender.
How much EMI will I pay on ₹5,000?
The EMI depends on the interest rate and tenure. For example, at 24% per year over three months, the approximate EMI is around ₹1,700 before applicable fees.
Is instant loan approval guaranteed?
No. A lender can approve or reject an application after checking KYC, credit profile, income, bank information and repayment capacity.
Should I use any loan app offering ₹5,000?
No. Verify the actual lender and carefully check the loan terms before submitting personal information or accepting credit.
Final Word
A ₹5,000 instant loan can be useful for a short-term financial need, but speed should not be the only consideration. Compare the interest rate, APR, fees, EMI and total repayment amount, and make sure you can comfortably repay the loan.
Published on : 23th September
Published by : Shibam Nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed