

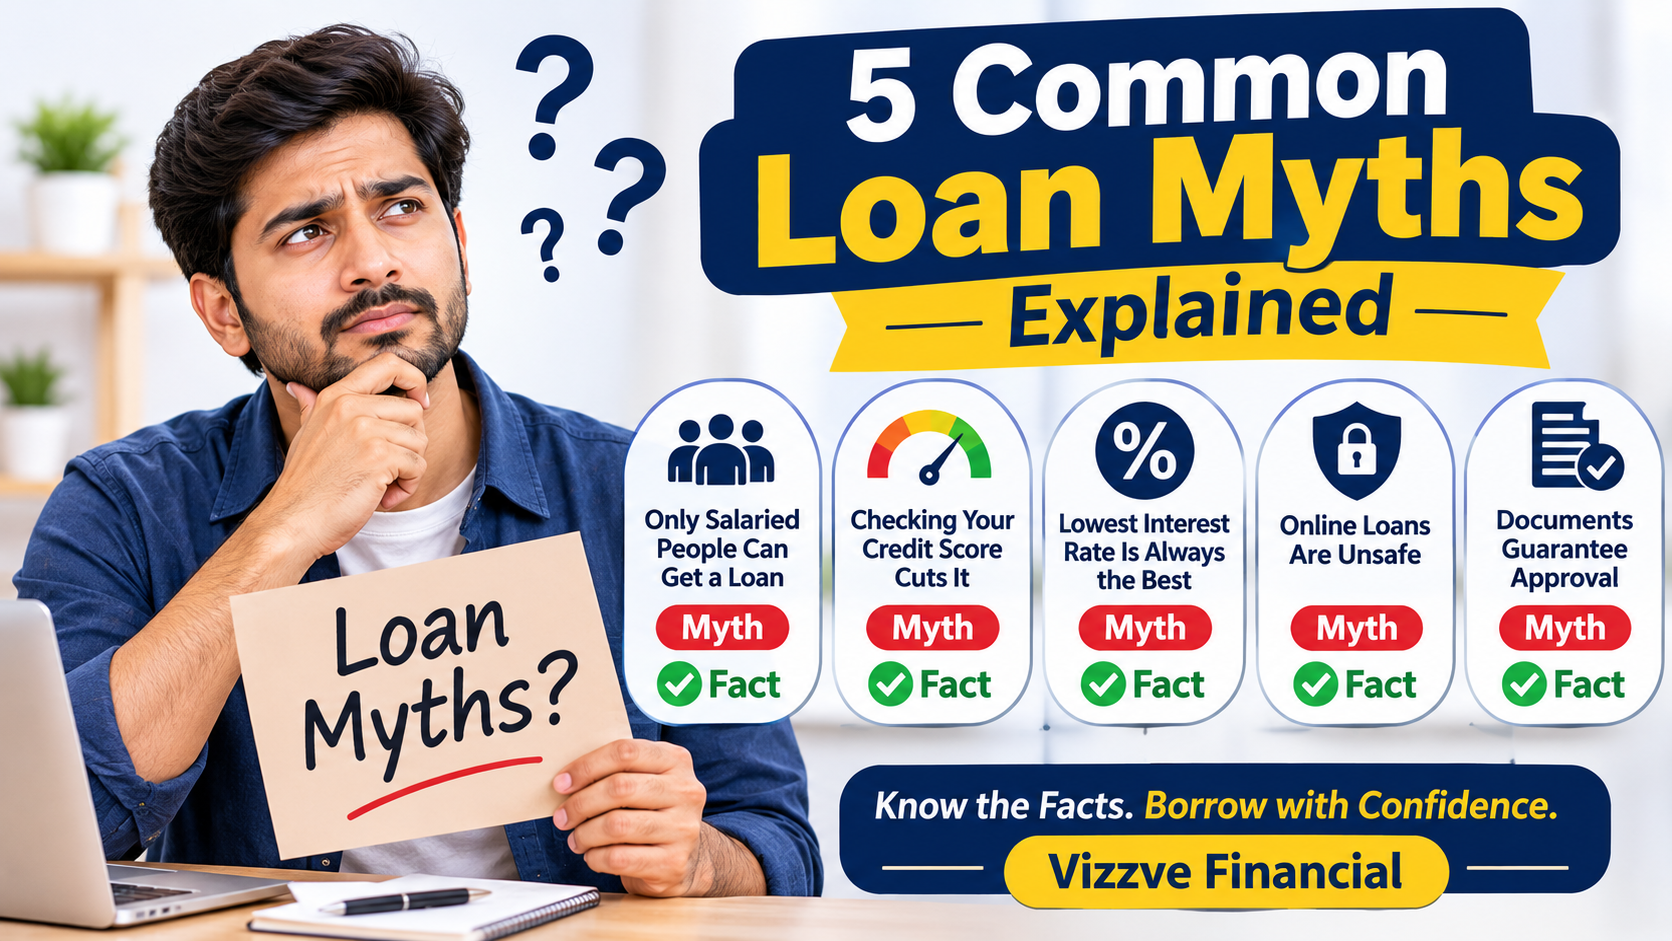
Many people have questions about personal loans but hesitate to ask. They may worry about credit scores, high interest rates, hidden charges or whether they qualify.
The problem is that not every financial belief is correct. Some loan myths come from outdated information, while others arise from misunderstandings about how lenders assess applications.
Learning the facts can help borrowers:
-
Understand how loan eligibility works.
-
Avoid unnecessary fear about credit scores.
-
Compare loan offers more carefully.
-
Recognise unsafe lending practices.
-
Make informed borrowing decisions.
Let's explore five common loan myths and understand what borrowers should know before applying.
Loan Myth: Only Salaried People Can Get Personal Loans
Myth: Personal loans are available only to people working in salaried jobs.
Fact: Self-employed individuals, freelancers and business owners may also qualify for personal loans, depending on the lender's eligibility rules.
Many people earn money through businesses, freelance projects, consulting, shops or other independent work. A salaried job is not the only way to demonstrate repayment capacity.
Who Can Apply for a Personal Loan?
Depending on lender requirements, applicants may include:
-
Salaried employees.
-
Self-employed professionals.
-
Small business owners.
-
Freelancers with regular income.
-
Other applicants who meet the lender's conditions.
How Do Lenders Evaluate Different Income Sources?
Lenders may look at several factors when reviewing an application:
|
Factor |
What lenders may check |
|---|---|
|
Income |
How much the applicant earns. |
|
Income stability |
Whether income is reasonably consistent. |
|
Bank statements |
Financial activity and cash flow. |
|
Credit history |
Past borrowing and repayment behaviour. |
|
Existing EMIs |
Current repayment commitments. |
|
Eligibility |
Whether the applicant meets the lender's criteria. |
What Can Self-Employed Borrowers Prepare?
Self-employed applicants may be asked for:
-
Bank statements.
-
Income records.
-
Business-related documents.
-
PAN and identity verification.
-
Other documents requested by the lender.
Expert insight: Income stability and repayment capacity are more meaningful than simply having a particular job title. Applicants should provide accurate financial information and choose a loan amount they can comfortably repay.
Loan Myth: Checking Your Credit Score Will Lower It
Myth: Checking your credit score reduces your credit score.
Fact: Checking your own credit report or score is generally a soft enquiry and does not lower your credit score.
Credit scores help lenders understand how a person has handled credit in the past. Reviewing your own credit report can help you identify errors, understand your financial standing and prepare before applying.
What Is the Difference Between Soft and Hard Credit Enquiries?
|
Soft enquiry |
Hard enquiry |
|---|---|
|
Usually occurs when you check your own credit score. |
May occur when a lender checks your credit report for a credit application. |
|
Generally does not affect your credit score. |
May affect your score, depending on the scoring model and circumstances. |
|
Useful for monitoring your credit. |
Used during lending decisions. |
Why Should You Check Your Credit Report?
Checking your credit report regularly can help you:
-
Find incorrect account details.
-
Check whether payments are recorded correctly.
-
Identify unfamiliar credit enquiries.
-
Understand your credit history.
-
Prepare before applying for a loan.
How to Maintain a Healthy Credit Profile
-
Pay EMIs and credit card bills on time.
-
Avoid unnecessary credit applications.
-
Keep track of existing loans.
-
Review your credit report periodically.
-
Correct errors through the appropriate credit bureau process.
Expert insight: Checking your credit report before applying can help you spot problems early. It is better to understand your credit profile than to avoid checking it out of fear.
Loan Myth: The Lowest Interest Rate Is Always the Best Loan
Myth: A loan with the lowest advertised interest rate is always the cheapest option.
Fact: The interest rate is important, but the total cost of a loan also includes other charges, repayment terms and conditions.
Two loans may have similar interest rates but different processing fees, repayment periods or other costs. Borrowers should compare the complete loan offer before making a decision.
What Should You Compare Before Taking a Loan?
|
Loan feature |
Why it matters |
|---|---|
|
Interest rate |
Determines the interest charged on the loan. |
|
Processing fee |
May increase the cost of borrowing. |
|
Repayment tenure |
Affects monthly EMI and total interest. |
|
EMI |
Helps you understand monthly repayment commitments. |
|
Late payment charges |
May apply if repayments are delayed. |
|
Prepayment conditions |
May affect the cost of repaying early. |
|
Total repayment |
Shows how much you will pay over the loan period. |
Example: Why Total Cost Matters
Imagine two loan offers for a loan amount of ₹1,00,000.
|
Feature |
Loan A |
Loan B |
|---|---|---|
|
Interest rate |
12% |
13% |
|
Tenure |
12 months |
12 months |
|
Processing fee |
₹2,000 |
₹500 |
Illustrative comparison only. Actual EMIs, fees and total costs depend on lender calculations, repayment schedules and loan conditions.
Even when one loan has a lower interest rate, the processing fee and other charges can change the overall cost.
How to Make a Better Loan Comparison
-
Compare the interest rate and fees.
-
Check the EMI amount.
-
Review the repayment tenure.
-
Calculate the total amount payable.
-
Read the loan agreement carefully.
Expert insight: A lower EMI does not always mean a cheaper loan. A longer repayment period may reduce the monthly payment but increase the total interest paid over time.
Loan Myth: Online Loans Are Always Unsafe
Myth: Every online loan application is risky or fraudulent.
Fact: Digital lending can be convenient and legitimate when borrowers apply through verified platforms connected to regulated lenders and follow safe practices.
Digital lending allows borrowers to apply, submit documents and complete certain verification steps online. However, fraudulent websites, misleading advertisements and unauthorised agents also exist.
How Can You Identify a Safe Online Loan Platform?
Before applying, check:
-
The actual lender's name.
-
Whether the lender is a regulated bank or RBI-regulated NBFC.
-
Whether the digital lending platform clearly identifies the regulated lender it works with.
-
Whether the official website is genuine.
-
Whether the interest rate and fees are clearly disclosed.
-
Whether a Key Fact Statement (KFS), where applicable, is provided.
-
Whether the privacy policy explains how your data is handled.
Warning Signs of a Suspicious Loan Offer
|
Warning sign |
Why you should be careful |
|---|---|
|
Guaranteed approval |
Approval depends on lender assessment. |
|
Upfront payment demanded by an unknown agent |
Could be a fraud attempt. |
|
OTP or PIN requests |
Never share OTPs or PINs with others. |
|
Unverified website |
Could be used to collect personal information. |
|
Unclear interest rates |
Makes it difficult to understand borrowing costs. |
|
Pressure to accept immediately |
Can prevent careful review of loan terms. |
Safe Digital Borrowing Tips
-
Apply through official websites or verified applications.
-
Never share passwords, PINs or OTPs.
-
Read the loan agreement before accepting.
-
Check the lender and platform relationship.
-
Avoid clicking suspicious loan links.
-
Understand the total repayment amount.
Expert insight: Digital lending is not inherently unsafe. The important thing is to verify the lender, understand the loan agreement and protect your personal information.
Loan Myth: Loan Approval Is Guaranteed If You Have All the Documents
Myth: If you submit all the required documents, your loan will definitely be approved.
Fact: Documents help lenders verify your information, but approval depends on several factors.
Submitting complete documents is important, but lenders may also evaluate your credit history, income, existing EMIs and repayment capacity.
What Do Lenders Consider Before Approving a Loan?
|
Approval factor |
What it means |
|---|---|
|
Income |
Your ability to manage repayments. |
|
Credit history |
Your past credit and repayment behaviour. |
|
Existing debt |
Current loans and repayment commitments. |
|
Employment or business stability |
Your income source and financial stability. |
|
Documents |
The accuracy and completeness of the information provided. |
|
Eligibility criteria |
Whether you meet the lender's conditions. |
How Can You Improve Your Chances of Loan Approval?
-
Check your eligibility before applying.
-
Keep your credit report healthy.
-
Provide accurate income details.
-
Submit clear and complete documents.
-
Avoid unnecessary credit applications.
-
Choose an affordable loan amount.
-
Maintain a manageable EMI burden.
Does a High Credit Score Guarantee Approval?
No. A good credit score may improve your chances of qualifying for certain loan products, but it does not guarantee approval.
Lenders may consider income, employment or business stability, existing debt, loan amount and their own eligibility policies.
Expert insight: A strong application is not simply about uploading documents. It is about demonstrating that you meet the lender's conditions and can repay the loan responsibly.
Quick Comparison of Loan Myths and Facts
|
Loan myth |
Actual fact |
|---|---|
|
Only salaried people can get loans. |
Self-employed applicants and other income groups may also qualify. |
|
Checking your own credit score lowers it. |
Checking your own score is generally a soft enquiry. |
|
The lowest interest rate means the cheapest loan. |
Fees, tenure and total repayment also matter. |
|
All online loans are unsafe. |
Verified digital lending can be legitimate and convenient. |
|
Complete documents guarantee approval. |
Approval depends on multiple eligibility and risk factors. |
Key Takeaways
-
Loan myths can prevent people from making informed financial decisions.
-
Personal loans may be available to salaried and self-employed applicants.
-
Checking your own credit report generally does not reduce your credit score.
-
Compare the total cost of a loan, not only the interest rate.
-
Online lending can be safe when you verify the lender and protect your information.
-
Documents alone do not guarantee loan approval.
-
Borrow only when you have a clear repayment plan.
Pros and Cons of Understanding Loan Facts
Pros
-
Helps you make informed borrowing decisions.
-
Reduces confusion about loan eligibility.
-
Encourages better credit management.
-
Helps you compare lenders.
-
Makes it easier to recognise potential fraud.
-
Promotes responsible borrowing.
Cons of Ignoring Loan Facts
-
You may miss suitable loan opportunities.
-
You may choose expensive loan products.
-
You may misunderstand credit enquiries.
-
You may fall for misleading loan advertisements.
-
You may borrow more than you can comfortably repay.
A Simple Checklist Before Applying for a Personal Loan
Use this checklist to make sure you are prepared.
Frequently Asked Questions
Are personal loans only available to salaried people?
No. Self-employed professionals, freelancers and business owners may also qualify for personal loans, depending on the lender's eligibility conditions.
Does checking my credit score reduce it?
Generally, no. Checking your own credit score is usually a soft enquiry and does not lower your credit score.
Is a personal loan with a low interest rate always better?
Not necessarily. Processing fees, other charges, repayment tenure and total repayment amount should also be considered.
Are online personal loans safe in India?
They can be safe when offered through legitimate lending arrangements with regulated lenders. Always verify the lender and read the loan terms.
Can I get a personal loan with a low credit score?
Some lenders may consider applicants with lower credit scores, but approval, loan amounts and interest rates depend on their policies and the applicant's overall profile.
Does having a good credit score guarantee loan approval?
No. Lenders also consider income, existing debts, repayment capacity, documents and other eligibility conditions.
Why do lenders ask for bank statements?
Bank statements may help lenders review income, cash flow, financial activity and repayment capacity.
Can self-employed people apply for personal loans?
Yes. Self-employed applicants may qualify if they meet the lender's income, credit, documentation and other requirements.
Should I apply to several lenders at the same time?
It is generally better to compare loan options first and avoid unnecessary applications. Multiple hard enquiries may affect your credit profile, depending on the scoring model and circumstances.
How can I avoid loan fraud?
Apply through verified websites or applications, check the actual lender, read the loan agreement, avoid suspicious upfront payments and never share OTPs or passwords.
Conclusion
Loan myths can create unnecessary fear and confusion. Understanding the facts about eligibility, credit scores, interest rates, digital lending and approval requirements can help you make better financial decisions.
Before applying for a loan, take time to compare offers, check your repayment capacity and verify the lender. A loan should support your financial needs without creating unnecessary repayment pressure.
Explore Loan Options with Vizzve Financial
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Make informed financial decisions, understand your repayment commitments and borrow responsibly.
Published on : 22th Novemebr
Published by : MD HDEAYATULLAJ
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed