

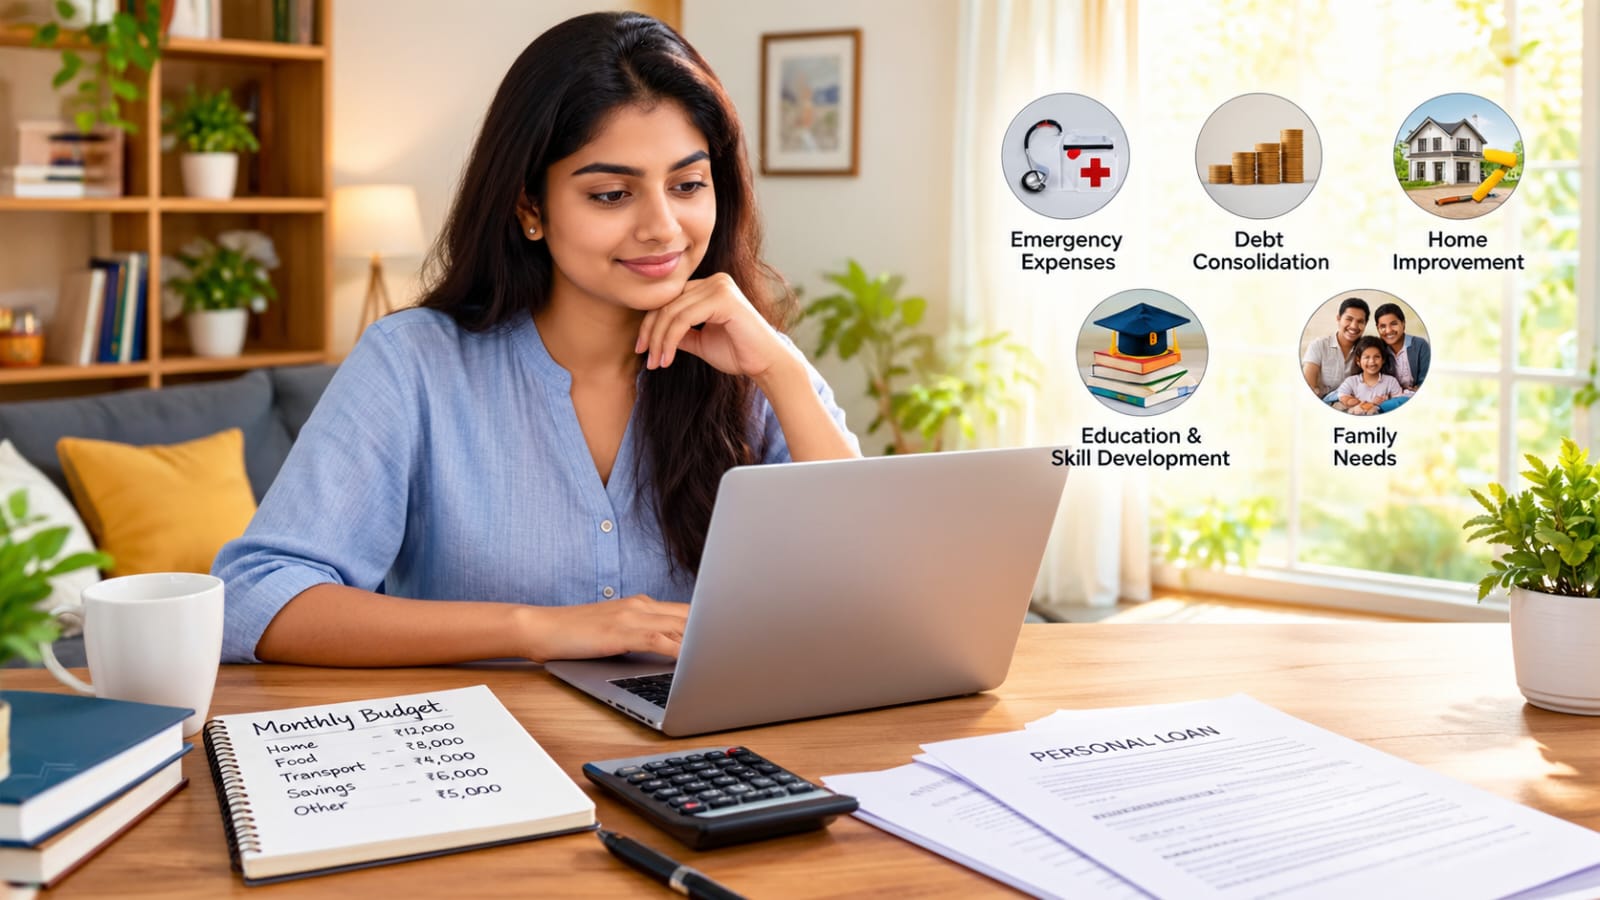
A personal loan can be a practical financial tool when used with a clear purpose and a repayment plan. The real challenge is not getting the loan; it is using it in a way that does not create pressure later.
The smartest borrowers treat a personal loan like support for a specific goal, not extra spending money. That means checking the EMI, comparing costs, and making sure the loan fits the monthly budget before accepting it.
AI Answer Box
What is the smartest way to use a personal loan?
Use it for a clear need, keep the EMI affordable, and repay it on time without disturbing your monthly essentials.
How do I avoid financial burden after taking a loan?
Borrow only what you need, compare offers, keep emergency savings, and choose a repayment plan you can manage comfortably.
Can a personal loan be useful?
Yes, when it helps with emergencies, planned expenses, or debt management and is repaid on schedule.
Why Personal Loan Planning Matters
A personal loan becomes expensive when it is taken without planning. Even if the approval is quick, the monthly repayment can affect your budget for rent, food, travel, savings, and family needs.
Smart use starts with one simple rule: if the EMI feels difficult before borrowing, it will feel harder after borrowing. Careful planning protects both your cash flow and your credit profile.
5 Smart Ways to Use a Personal Loan
1. Use it for emergencies
A personal loan can help during urgent situations such as medical treatment, sudden home repairs, or essential family expenses. In these cases, speed matters, and a loan may be better than delaying a necessary payment.
2. Consolidate higher-cost debt
If you already have multiple expensive debts, one personal loan may help you combine them into a single monthly payment. This can make repayment easier to track and may reduce stress if the new EMI is more manageable.
3. Fund planned essential expenses
Some expenses are important but difficult to pay all at once, such as education-related costs, house repairs, or moving costs. A personal loan can spread that burden over time, as long as the repayment stays realistic.
4. Protect your savings in a true need
Sometimes it is better to borrow than to drain all your savings for one major expense. Keeping some emergency savings untouched can protect you from future surprises.
5. Use it only for value, not impulse spending
A personal loan should not be used for unplanned shopping, lifestyle upgrades, or unnecessary purchases. Borrowing for things that do not create value often leads to regret and repayment stress.
Comparison Table
| Use case | Smart or risky | Why |
|---|---|---|
| Medical emergency | Smart | Urgent and necessary expense. |
| Debt consolidation | Smart | Can simplify repayment. |
| Home repair | Smart | Protects the property and household safety. |
| Wedding expenses | Mixed | Useful only if budgeted carefully. |
| Vacation or luxury spending | Risky | Creates debt without long-term value. |
How to Borrow Without Stress
Check the EMI first
Before taking the loan, calculate how much you can pay every month without affecting essentials. A loan should fit your life, not force your life to fit the loan.
Compare total cost
Look beyond the headline interest rate. Processing fees, late charges, and repayment terms can change the real cost of the loan.
Keep a repayment buffer
Always leave room in your monthly budget for small emergencies. That buffer helps prevent missed EMIs if your income changes unexpectedly.
Avoid borrowing more than needed
Taking a bigger amount may feel safer at first, but it also increases repayment pressure. Borrow only the amount that solves the actual problem.
Pros and Cons
| Pros | Cons |
|---|---|
| Fast access to money in urgent situations. | Interest and charges increase total repayment. |
| Can help manage essential expenses or debt. | EMI pressure can affect monthly budget. |
| Useful when savings should be protected. | Easy to overspend if not planned well. |
| May improve financial discipline if repaid on time. | Missing payments can hurt credit health. |
Step-by-Step Guide
Step 1: Define the purpose
Write down why you need the loan and whether the expense is urgent, essential, or optional.
Step 2: Set a repayment limit
Decide the highest EMI you can comfortably pay each month.
Step 3: Compare lenders
Review interest rate, fees, tenure, and repayment terms before applying.
Step 4: Read the loan terms carefully
Understand all charges and conditions before accepting the offer.
Step 5: Repay on schedule
Use reminders and auto-debit where possible to avoid late payments.
Expert Commentary
In real-world borrowing, the best personal loan is usually the one that solves a real problem without creating a new one. The loan amount should match the purpose, and the EMI should fit the borrower’s income pattern.
People who use personal loans wisely usually have one thing in common: they borrow with a plan. They know why they are borrowing, how long they will take to repay, and what expense they are protecting.
Key Takeaways
A personal loan should be used for a clear and necessary purpose.
Keep the EMI within a comfortable monthly budget.
Compare total repayment cost before choosing a lender.
Avoid using loans for impulse or non-essential spending.
Repay on time to protect your credit health.
Vizzve Financial
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
If you are planning to borrow, choose a loan that supports your goals without creating repayment pressure. Smart borrowing always starts with a clear plan.
FAQs
1. What is the best use of a personal loan?
The best use is for an essential need such as an emergency, debt consolidation, or planned necessary expense.
2. Is a personal loan good for emergencies?
Yes, if the emergency is real and the repayment is manageable.
3. Can I use a personal loan for debt consolidation?
Yes, if it helps simplify your payments and the new terms are better or more manageable.
4. Should I use a personal loan for travel?
Only if the expense is fully budgeted and the EMI will not strain your finances.
5. Is it okay to use a loan for wedding expenses?
It can be, but only with careful planning and a realistic repayment plan.
6. What should I avoid using a personal loan for?
Avoid using it for unnecessary shopping, luxury spending, or impulse purchases.
7. How do I know if the EMI is safe?
If you can pay it comfortably after essential expenses and savings, it is safer.
8. Does taking a personal loan affect credit score?
Yes, repayment behavior can affect your credit profile.
9. Is borrowing from savings better than taking a loan?
If possible, using savings may be cheaper, but keeping an emergency buffer is also important.
10. How can I reduce loan burden?
Borrow only what you need, compare options, and repay on time.
11. Can I prepay a personal loan early?
Often yes, but check whether any prepayment charges apply.
12. What is the biggest mistake borrowers make?
Borrowing without a repayment plan.
Conclusion
A personal loan can help when used wisely, but it should never become a source of long-term financial pressure. The safest approach is simple: borrow for a real need, keep the EMI manageable, and repay on time.
For quick personal-loan support and a simple application experience, visit Vizzve Financial.
Published on : 25th September
Published by : Avinash S
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed