

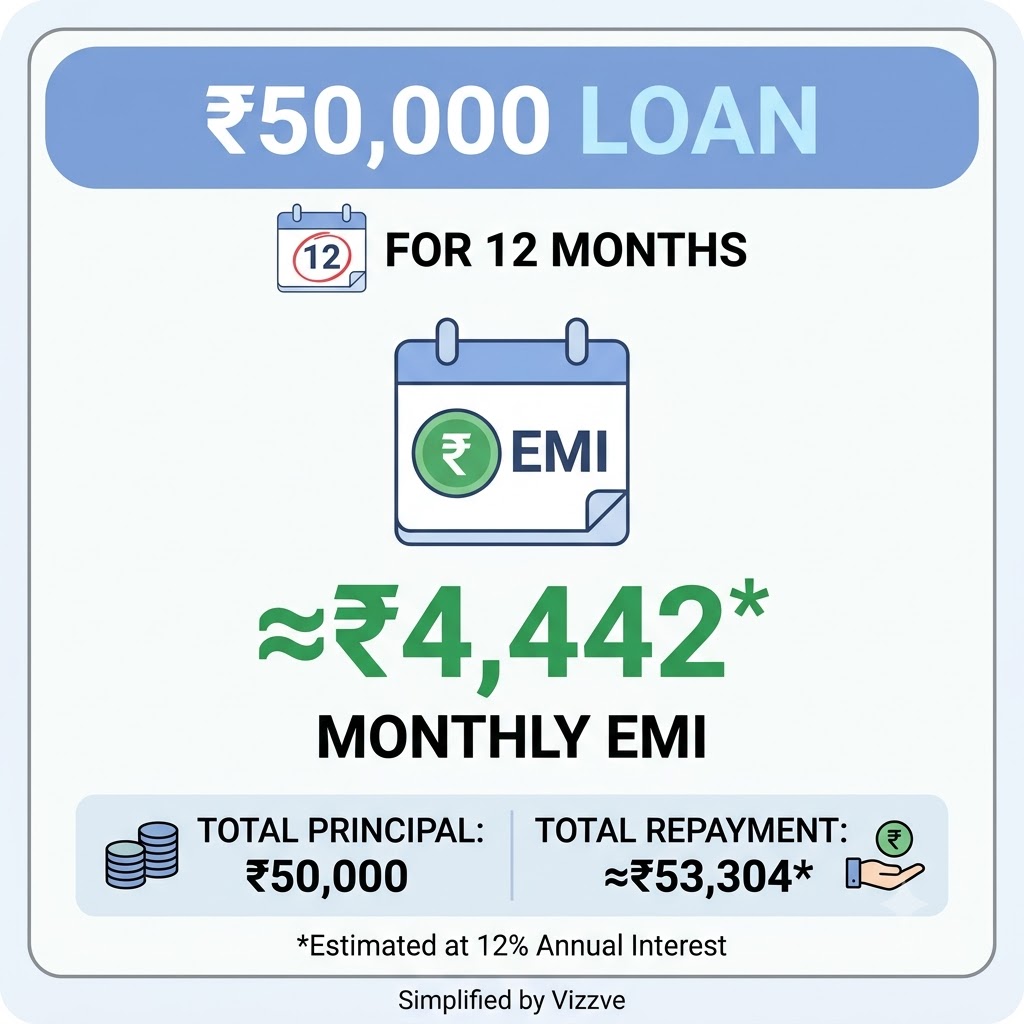
₹50,000 Loan EMI for 12 Months: Monthly Payment, Interest and Repayment Guide
A ₹50,000 personal loan can help cover emergency expenses, medical bills, education fees, home repairs, or other short-term financial needs. Before applying, it is important to understand the monthly EMI, interest rate, processing fees, and total repayment amount.
If you borrow ₹50,000 for 12 months, your EMI will depend on the interest rate offered by the lender. Comparing loan offers can help you choose a repayment plan that fits your monthly budget.
What Is the EMI for a ₹50,000 Loan for 12 Months?
The Equated Monthly Instalment (EMI) is the fixed monthly payment made towards repaying a loan. It includes both the principal amount and interest.
Here is an illustrative EMI comparison for a ₹50,000 loan with a 12-month repayment period.
| Annual Interest Rate | Approx. Monthly EMI | Total Repayment | Total Interest |
|---|---|---|---|
| 10% | ₹4,396 | ₹52,752 | ₹2,752 |
| 12% | ₹4,442 | ₹53,304 | ₹3,304 |
| 15% | ₹4,512 | ₹54,144 | ₹4,144 |
| 18% | ₹4,584 | ₹55,008 | ₹5,008 |
| 24% | ₹4,728 | ₹56,736 | ₹6,736 |
These figures are estimates based on monthly reducing-balance interest. Actual EMIs may vary depending on the lender's terms. Processing fees, taxes, and other charges are excluded.
How to Calculate the EMI for a ₹50,000 Loan
You can calculate your monthly EMI using the following formula:
EMI = P × r × (1 + r)ⁿ ÷ [(1 + r)ⁿ − 1]
Where:
-
P: Loan principal of ₹50,000
-
r: Monthly interest rate
-
n: Loan tenure of 12 months
For example, at an annual interest rate of 12%, the estimated monthly EMI is ₹4,442. Your total repayment over 12 months would be approximately ₹53,304.
Who Can Consider a ₹50,000 Personal Loan?
A ₹50,000 loan may be useful for people who need funds for:
-
Unexpected medical expenses
-
Education or tuition fees
-
Home maintenance and repairs
-
Vehicle repair costs
-
Rent or urgent household expenses
-
Other planned or emergency expenses
Borrow only what you need and ensure the monthly repayment is affordable.
Factors That Affect Your Loan EMI
Several factors determine your monthly EMI and the total cost of borrowing.
1. Interest Rate
A higher interest rate generally increases your EMI and total interest cost.
2. Loan Tenure
A 12-month tenure allows you to repay the loan within one year. A shorter tenure may increase the EMI, while a longer tenure may increase the total interest paid.
3. Credit Profile
Your credit history, income, existing EMIs, and lender eligibility criteria can influence the interest rate and loan approval decision.
4. Additional Charges
Processing fees, applicable taxes, and other permitted charges can increase the overall borrowing cost. Review the Key Facts Statement and loan agreement before accepting an offer.
How to Manage a ₹50,000 Loan Repayment
Follow these simple steps to manage your loan responsibly:
-
Check your monthly income and essential expenses.
-
Keep enough money in your account before the EMI due date.
-
Compare interest rates and the Annual Percentage Rate (APR).
-
Review processing fees and other charges.
-
Avoid taking another loan just to repay an existing EMI.
-
Maintain an emergency fund whenever possible.
Is a ₹50,000 Loan for 12 Months a Good Option?
A 12-month personal loan may be suitable if you have a clear repayment plan and can comfortably afford the monthly EMI. However, the right choice depends on your income, existing financial commitments, and the total borrowing cost.
Compare multiple offers, check the lender's credentials, and read the loan terms carefully before applying.
Frequently Asked Questions
1. What is the EMI for a ₹50,000 loan for 12 months?
At an annual interest rate of 12%, the estimated EMI is approximately ₹4,442.
2. Can I get a ₹50,000 personal loan for one year?
Eligibility depends on the lender's income, credit history, employment, and other requirements.
3. How much interest will I pay on a ₹50,000 loan?
At 12% annual interest on a reducing balance, the estimated total interest is ₹3,304 over 12 months, excluding fees.
4. Does the EMI include processing fees?
Usually, processing fees are charged separately or deducted from the disbursed amount. Check the lender's terms.
5. Can I repay my loan before 12 months?
Early repayment may be possible, subject to the lender's terms and any applicable charges.
6. Does a higher interest rate increase my EMI?
Yes. A higher interest rate generally increases both the monthly EMI and total interest cost.
7. Should I compare APR before applying?
Yes. APR helps you understand the annualised cost of borrowing, including applicable charges.
Conclusion
A ₹50,000 loan for 12 months can provide financial support when planned carefully. At an illustrative 12% annual reducing-balance interest rate, the monthly EMI is around ₹4,442. Compare lenders, review all applicable charges, and choose a repayment amount that fits your budget.
Published on : 27th October 2026
Published by : monisha
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed