

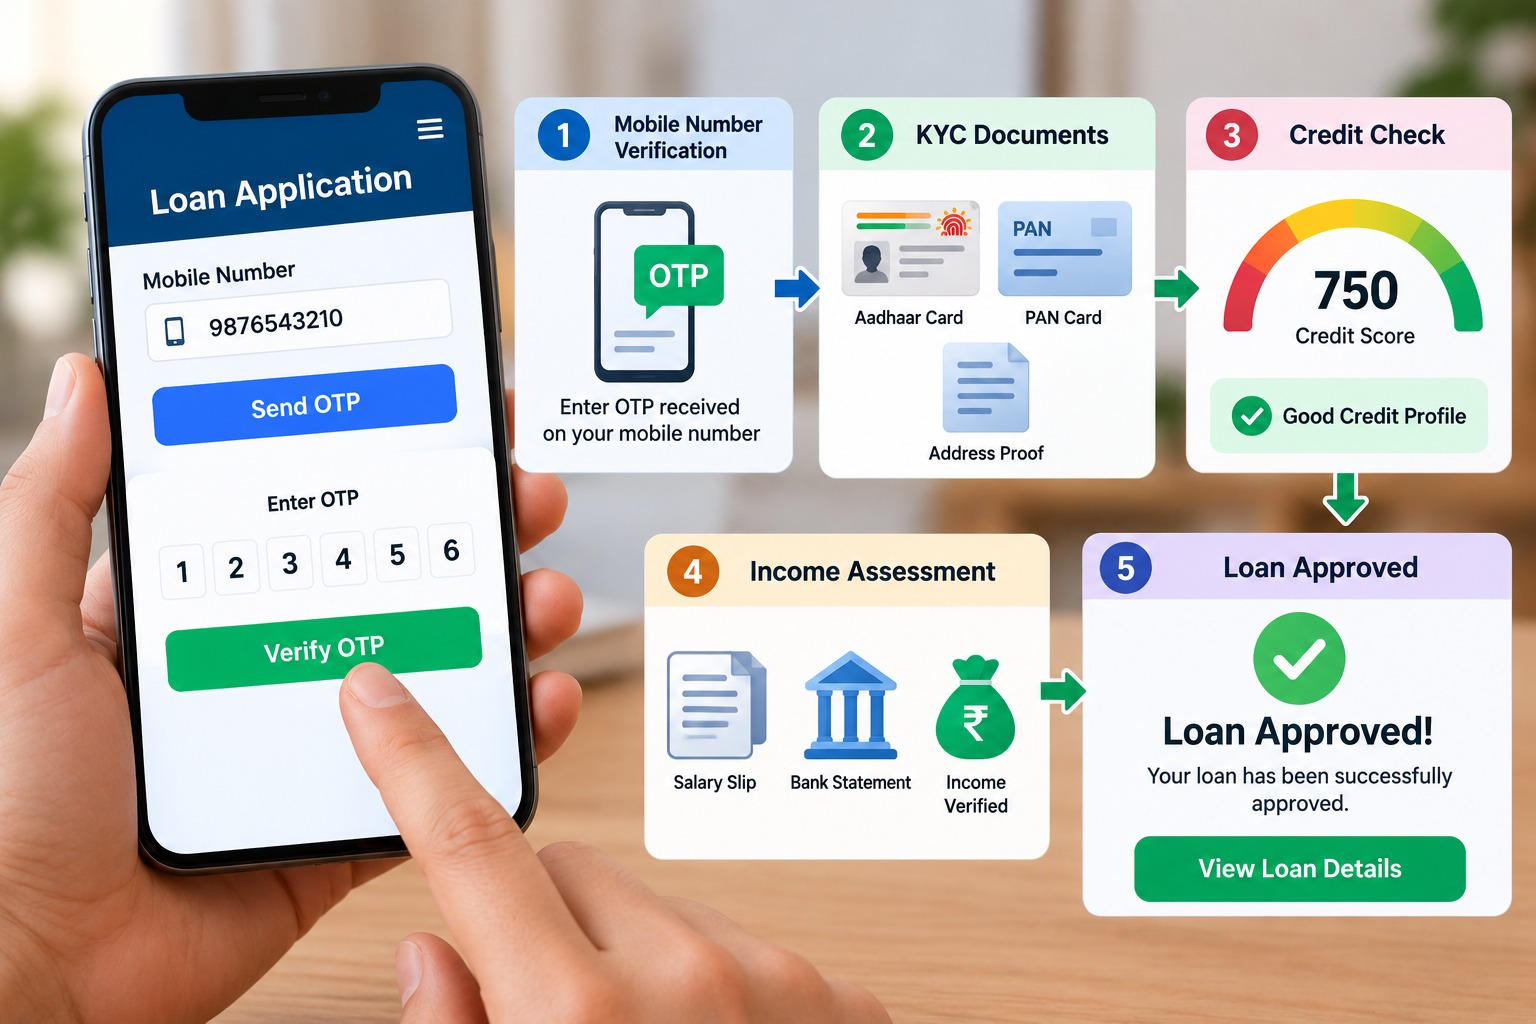
Many people search for loans that require only a mobile number. Some loan apps advertise quick applications with minimal paperwork, but a genuine lender generally cannot approve and disburse a loan using only your mobile number.
Your mobile number may help start the application or receive an OTP, but lenders usually need additional information to verify your identity, assess your creditworthiness and understand your repayment capacity.
Why Do Loan Apps Ask for Your Mobile Number?
A mobile number can be useful during several stages of a digital loan application.
1. OTP Verification
A lender may send an OTP to confirm that the applicant controls the registered mobile number.
However, OTP verification alone does not complete the entire KYC or loan approval process.
2. Application Communication
The lender may use your mobile number to send:
- Application updates
- Verification messages
- Loan approval or rejection information
- Repayment reminders
- Account alerts
- Important loan documents or links
3. Account Identification
Your mobile number may be linked to an existing customer profile or bank account. This can make the application process faster for some existing customers.
Even in such cases, the lender may still conduct additional checks before approving a new loan.
What Else Is Required for a Loan?
The exact requirements depend on the lender, loan amount and product. Common requirements may include:
- PAN or another identity document
- Aadhaar or another officially valid KYC document
- Address details
- Bank-account information
- Income or employment details
- Salary slips or bank statements
- ITRs or business records for self-employed applicants
- Credit history
- Existing loan and EMI details
- Consent for necessary verification
RBI's digital-lending framework requires regulated lenders to obtain information about a borrower's economic profile, including details such as age, occupation and income, to assess creditworthiness before extending a loan. <Cite refs={["turn683721search2"]} />
Can a Mobile Number Help You Get an Instant Loan?
A mobile number may help you begin an online loan application, but “instant” does not mean automatic or guaranteed approval.
A digital lender may still check:
- Your identity
- Your credit history
- Your income
- Your existing EMIs
- Your bank details
- Your repayment capacity
- Your submitted documents
- Fraud and security information
The lender may approve, reject or request additional information after completing these checks.
Mobile Number Loan vs Genuine Personal Loan
| Feature | Mobile-number-only claim | Genuine loan process |
|---|---|---|
| Mobile number | Usually requested | Usually required |
| OTP | May be requested | May be used for verification |
| KYC | Often unclear | Normally required |
| Income details | May be missing | May be assessed |
| Credit assessment | May be unclear | Usually conducted |
| Loan agreement | May be unavailable | Should be provided |
| Charges | May be hidden | Should be disclosed |
| Approval guarantee | High-risk warning sign | No guaranteed approval |
A claim that a loan is guaranteed with no identity verification, no income assessment and no written terms should be treated cautiously.
Is It Safe to Share Your Mobile Number With a Loan App?
Sharing a mobile number with a genuine lender may be part of the application process. However, you should verify the app and understand how your information will be used.
Before entering your number, check:
- The actual name of the lender
- Whether the lender is a bank or regulated NBFC
- The app's official website
- The privacy policy
- The permissions requested by the app
- The interest rate and fees
- The loan agreement and KFS
- The grievance-redressal details
RBI guidance requires digital lending data collection to be need-based and based on prior, explicit borrower consent. Digital lending apps should not unnecessarily access resources such as contact lists, call logs or personal files. <Cite refs={["turn683721search0","turn683721search2"]} />
Red Flags in Mobile-Number Loan Offers
Be careful if a loan app or agent:
- Promises guaranteed approval
- Claims that no KYC is required
- Requests an upfront payment before explaining the loan
- Does not clearly identify the actual lender
- Hides the interest rate or processing fee
- Refuses to provide a loan agreement
- Asks for OTPs, UPI PINs or banking passwords
- Requests unnecessary access to contacts or personal files
- Pressures you to accept the loan immediately
- Uses suspicious links or unofficial websites
RBI has warned consumers about unauthorized digital lending platforms and advised borrowers to verify the identity and credentials of entities offering loans through mobile apps. <Cite refs={["turn683721search14"]} />
What Is KFS in a Digital Loan?
KFS means Key Facts Statement. It presents important loan information in a clear and standardized format.
Before accepting an applicable digital loan, review the KFS for:
- Loan amount
- Interest rate
- APR
- EMI
- Tenure
- Processing fee
- Other applicable charges
- Repayment schedule
- Penal charges
- Cooling-off or look-up period
- Grievance-redressal details
RBI's digital-lending framework requires relevant loan costs and terms to be disclosed to borrowers through the applicable documentation, including the KFS. <Cite refs={["turn683721search10","turn683721search19"]} />
How to Apply for a Loan Safely
Follow these steps before submitting a loan application:
Step 1: Verify the Lender
Confirm the name of the bank or NBFC providing the loan.
Step 2: Use the Official App or Website
Avoid links sent by unknown agents through messages or social media.
Step 3: Complete Genuine KYC
Submit only the documents required through a verified process.
Step 4: Compare the Total Cost
Check the interest rate, APR, processing fee, EMI and total repayment amount.
Step 5: Read the Loan Agreement
Understand repayment dates, late charges, prepayment terms and other conditions.
Step 6: Protect Your Sensitive Information
Never share your OTP, UPI PIN, ATM PIN, card PIN or internet-banking password.
Can You Get a Loan Without a Salary Slip?
Some lenders may offer loans to self-employed borrowers or applicants whose income is verified through alternative documents. Depending on the product, they may review:
- Bank statements
- ITRs
- GST records
- Business registration
- Financial statements
- Business transactions
- Other income evidence
However, this does not mean that a mobile number alone is enough. The lender still needs to assess identity and repayment capacity.
Key Takeaways
- A mobile number alone is generally not enough for a legitimate loan.
- Your number may be used for OTPs, communication and application updates.
- Genuine lenders may require KYC, income, bank and credit information.
- Instant loan offers do not guarantee approval.
- Verify the actual lender before sharing personal information.
- Read the KFS, loan agreement, interest rate and fee details.
- Never share OTPs, PINs or banking passwords.
- Be cautious of apps promising loans without verification or documentation.
FAQs
1. Can I get a loan using only my mobile number?
Generally, no. A mobile number may start the application, but lenders usually require identity verification, credit assessment and other information.
2. Why do loan apps ask for my mobile number?
The number may be used for OTP verification, communication, application updates and account identification.
3. Is OTP verification enough to get a loan?
No. OTP verification only confirms access to a mobile number. It does not establish income, creditworthiness or full identity verification.
4. Can I get an instant loan without documents?
Some lenders may offer simplified or digital documentation, but legitimate lending normally involves appropriate verification and credit assessment.
5. Can self-employed people get loans without salary slips?
Some lenders may accept bank statements, ITRs, GST records or other business-income documents instead of salary slips.
6. Is a mobile-number-only loan offer safe?
It may be risky if the provider does not clearly identify the lender, explain the charges or conduct proper verification.
7. Can a loan app ask for my contacts?
You should be cautious about apps requesting unnecessary access to your contact list, call logs or personal files. Review permissions and privacy terms carefully.
8. What should I check before using a loan app?
Check the actual lender, official app or website, KFS, APR, fees, privacy policy, repayment terms and grievance process.
9. Can a loan app approve a loan without checking income?
Some products may use alternative information, but regulated lenders must assess the borrower's creditworthiness using relevant economic-profile information.
10. What should I do if a loan app asks for an upfront payment?
Do not pay immediately. Verify the lender, understand the charges and avoid suspicious or unauthorized loan providers.
Published on : 25th September 2026
Published by : Shibam Nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed