

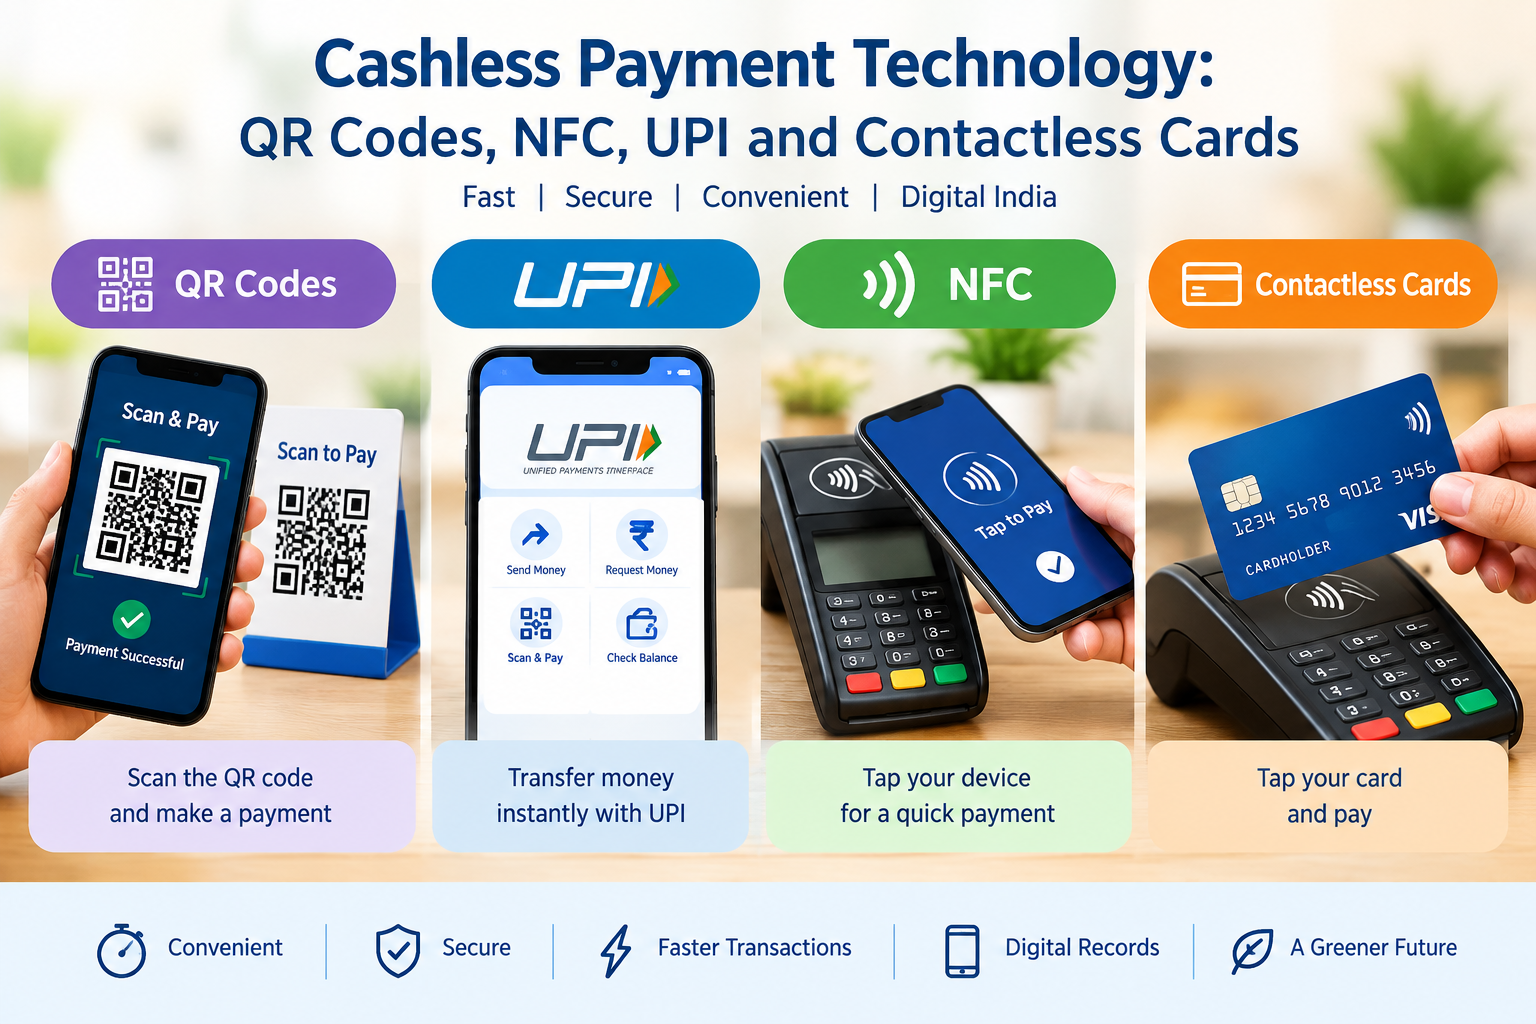
Cashless payment technology has changed the way people pay for products, services and bills. In India, consumers can make digital payments using QR codes, UPI, NFC-enabled devices and contactless cards. These technologies allow transactions without the need to exchange physical cash and are increasingly used by individuals, merchants and businesses.
Understanding how these payment technologies work can help users choose the right method while also following basic digital payment security practices.
What Is Cashless Payment Technology?
Cashless payment technology refers to systems that allow money to be transferred electronically without using physical notes or coins.
Common technologies include:
- QR-code payments
- UPI
- NFC payments
- Contactless debit and credit cards
- Mobile wallets
- Internet banking
- Mobile banking
- Electronic fund transfers
Each technology uses different methods to initiate and authenticate a transaction.
How QR-Code Payments Work
A QR code, or Quick Response code, can contain payment-related information that a customer can scan using a supported payment application.
Steps in a QR-Code Payment
- Open a supported payment application.
- Select the QR scanner.
- Scan the merchant's QR code.
- Check the displayed recipient and payment amount.
- Authorize the transaction using the required authentication method.
- Receive the transaction confirmation.
QR payments are widely used for merchant transactions because customers can initiate payments using smartphones.
What Is UPI?
Unified Payments Interface (UPI) enables users to make electronic payments between participating bank accounts through supported applications.
Depending on the service and transaction, users may initiate payments using:
- UPI IDs
- QR codes
- Mobile numbers where supported
- Other UPI-enabled features
UPI can be used for person-to-person transfers, merchant payments, bill payments and other eligible transactions.
What Is NFC Payment Technology?
Near Field Communication (NFC) is a short-range wireless communication technology. It allows compatible devices to exchange information when they are brought close together.
For payments, NFC technology can be used by compatible smartphones, wearables and payment cards at supported terminals.
How NFC Payments Work
A typical NFC payment involves:
- Bringing an NFC-enabled device or card close to a compatible payment terminal.
- Allowing the payment terminal to communicate with the device or card.
- Completing the required authentication.
- Processing the transaction electronically.
What Are Contactless Cards?
Contactless cards use technologies such as NFC to allow customers to make payments by tapping the card on a compatible payment terminal.
They can reduce the need to insert a card into a payment terminal for eligible transactions.
Depending on the transaction and issuer's security requirements, additional authentication may sometimes be required.
QR Code vs NFC vs UPI vs Contactless Cards
| Feature | QR Code | UPI | NFC | Contactless Card |
|---|---|---|---|---|
| Main technology | Optical scanning | Digital payment infrastructure | Near-field communication | NFC/contactless technology |
| Common device | Smartphone | Smartphone | Smartphone/wearable/card | Contactless card |
| Merchant terminal required | QR display is needed | Depends on payment method | Compatible NFC terminal | Compatible card terminal |
| Physical card required | No | No | No, if using phone/wearable | Yes |
| Typical use | Merchant payments | Transfers and payments | Tap-based payments | Tap-based card payments |
Benefits of Cashless Payment Technology
Convenience
Users can make payments without carrying or counting physical cash.
Speed
Tap-based and QR-based payments can make many everyday transactions quick and straightforward.
Digital Records
Electronic payments generally create transaction records that can help users monitor spending.
Wider Payment Options
Consumers can choose among smartphones, cards, wearables and other supported devices.
Merchant Convenience
Digital payment acceptance can provide merchants with electronic transaction records and additional payment options for customers.
Security Considerations
Cashless payments offer security features, but users should still take precautions.
For QR Payments
- Verify the recipient before approving a transaction.
- Do not scan unknown or suspicious QR codes.
- Remember that entering a UPI PIN is generally for authorizing a payment, not for receiving money.
For UPI
- Never share your UPI PIN or OTP.
- Check the payment request before approving it.
- Use official payment applications.
- Be cautious of unsolicited collect/payment requests.
For NFC and Contactless Cards
- Keep your card or device secure.
- Check transaction notifications regularly.
- Report a lost card or device promptly.
- Follow your bank or card issuer's security instructions.
Cashless Payment Technology in India
India's digital payment ecosystem includes multiple payment technologies and infrastructure layers. UPI supports account-to-account payments, while cards and NFC technologies support card-based and tap-to-pay transactions. QR codes provide a convenient way for customers to initiate digital payments using compatible applications.
The availability of these options allows consumers and merchants to select payment methods based on the device, banking service, merchant setup and transaction requirements.
Future of Cashless Payments
The cashless payment ecosystem continues to evolve with developments in:
- Smartphone-based payments
- Wearable payment devices
- Contactless cards
- QR-code payments
- Digital banking
- Payment security technologies
- Faster electronic payment infrastructure
As these technologies develop, security, reliability, accessibility and ease of use will remain important considerations.
Frequently Asked Questions
What is cashless payment technology?
Cashless payment technology enables people to make transactions electronically without exchanging physical cash.
Is UPI the same as NFC?
No. UPI is a digital payment system, while NFC is a short-range communication technology used for applications including contactless payments.
What is the difference between QR and NFC payments?
QR payments generally require scanning a code with a compatible device, while NFC payments use short-range wireless communication between compatible devices.
What is a contactless card?
A contactless card is a payment card that can communicate with a compatible terminal when tapped or held close to it.
Are contactless payments secure?
Contactless payments use security mechanisms, but users should still protect their cards and devices and monitor transactions for unauthorized activity.
Can UPI payments be made using QR codes?
Yes. QR codes can be used to initiate UPI payments through compatible applications.
Do NFC payments require the internet?
The requirements can vary depending on the payment method, device, issuer and transaction setup. Users should follow the instructions provided by their payment provider.
What should I do if my contactless card is lost?
Contact the card issuer or bank as soon as possible and follow its instructions for blocking or replacing the card.
Key Takeaways
- QR codes allow users to initiate digital payments by scanning payment information.
- UPI enables electronic payments between participating bank accounts.
- NFC enables short-range communication for compatible payment transactions.
- Contactless cards allow eligible card payments by tapping at compatible terminals.
- Users should verify transaction details and protect PINs, OTPs and other authentication credentials.
- Different cashless technologies can complement one another within India's digital payment ecosystem.
Conclusion
Cashless payment technology has made digital transactions more accessible through QR codes, UPI, NFC and contactless cards. While each technology works differently, they share the goal of making electronic payments convenient and efficient. Understanding how these systems work, along with following basic security practices, can help consumers and businesses use cashless payment methods more confidently.
Published on : 27th September
Published by : MONISHA
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed