

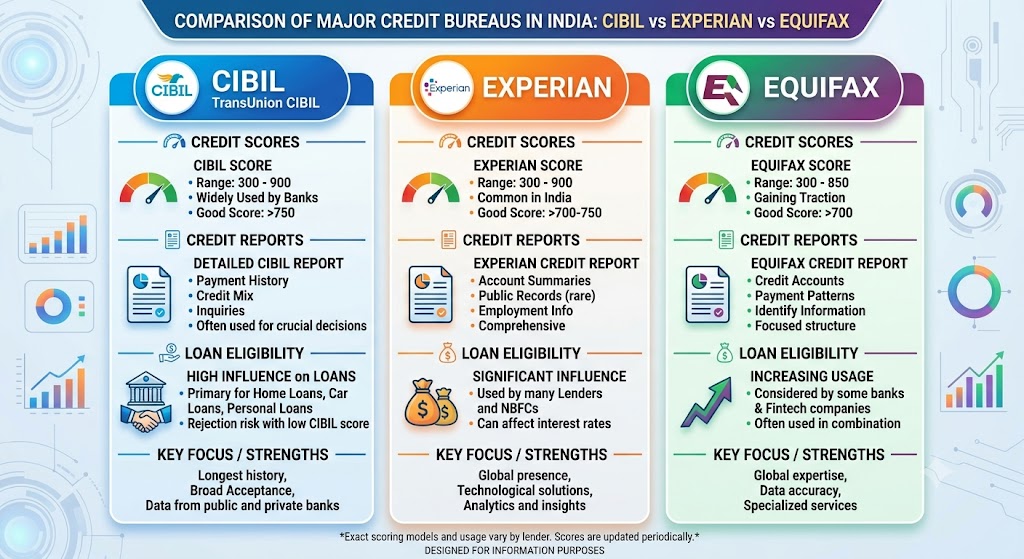
When applying for a personal loan, home loan, or credit card, your credit score can play an important role in the lender’s decision. In India, CIBIL, Experian, and Equifax are three major credit bureaus that collect credit-related information and generate credit reports and scores.
Although these bureaus serve a similar purpose, their scores may differ because of differences in the information they receive, reporting dates, and scoring methods. Understanding these differences can help borrowers monitor their credit health and prepare for future loan applications.
What Is a Credit Bureau?
A credit bureau is an organisation that collects and maintains information about a person's borrowing and repayment history. Banks and other eligible lending institutions use credit reports to assess a borrower's creditworthiness.
India has four major RBI-registered credit information companies: TransUnion CIBIL, Experian, Equifax, and CRIF High Mark. Each maintains its own credit information records and scoring systems. Source: RBI
1. What Is CIBIL?
TransUnion CIBIL is one of India's best-known credit bureaus. Its credit score helps lenders evaluate a borrower's credit history and repayment behaviour.
Key features of CIBIL:
-
Tracks loan and credit card repayment history.
-
Considers credit utilisation and outstanding balances.
-
Reflects reported defaults and overdue payments.
-
Helps lenders assess credit risk when reviewing applications.
A strong CIBIL score may improve your chances of qualifying for suitable credit products, but approval also depends on income, existing EMIs, employment stability, lender policies, and other eligibility requirements.
2. What Is Experian?
Experian is another RBI-registered credit information company operating in India. It provides credit reports and scores based on credit information reported by participating lenders.
Key features of Experian:
-
Maintains credit history and repayment information.
-
Helps borrowers monitor their credit profile.
-
Provides lenders with information for credit-risk assessment.
-
May display a different score from CIBIL for the same individual.
Experian scores can differ from CIBIL scores because the bureaus may receive or update information at different times and use different scoring models.
3. What Is Equifax?
Equifax Credit Information Services Private Limited is also an RBI-registered credit information company in India. It maintains credit information and generates reports that can help lenders evaluate borrowers.
Key features of Equifax:
-
Records credit-related information received from participating lenders.
-
Helps assess repayment patterns and outstanding credit.
-
Provides credit information for lending decisions.
-
May show a different credit score from other bureaus.
Borrowers should review their Equifax report for accuracy, particularly when checking loan balances, payment history, and account details.
CIBIL vs Experian vs Equifax: Key Differences
| Feature | CIBIL | Experian | Equifax |
|---|---|---|---|
| Main purpose | Credit reporting and scoring | Credit reporting and scoring | Credit reporting and scoring |
| Credit history | Maintains reported credit data | Maintains reported credit data | Maintains reported credit data |
| Score differences | Uses its own scoring model | Uses its own scoring model | Uses its own scoring model |
| Used by lenders | Depending on lender policy | Depending on lender policy | Depending on lender policy |
| Best use for borrowers | Monitor credit health | Cross-check credit information | Cross-check credit information |
Note: Availability of reports, score ranges, and services may vary. Check the respective bureau's official website for current details.
Why Are CIBIL, Experian, and Equifax Scores Different?
It is possible to have different scores across all three bureaus. This does not automatically mean that one score is incorrect.
Common reasons include:
-
Different reporting dates: A lender may update information with different bureaus at different times.
-
Different scoring models: Each bureau may calculate scores using its own methodology.
-
Differences in credit records: Some account information may not appear identically across reports.
-
Recent loan applications: Credit enquiries may be reflected differently depending on reporting and update timing.
-
Errors in credit reports: Incorrect balances, duplicate accounts, or wrongly reported late payments may affect a score.
If you notice a major difference, compare the underlying reports instead of focusing only on the numbers.
Which Credit Score Is Best for Loan Approval?
There is no single credit bureau that guarantees loan approval. The score a lender checks depends on its policies and credit assessment process.
CIBIL is widely recognised in India, but Experian and Equifax can also provide useful information about your credit profile.
Before applying for a loan, consider these steps:
-
Check which bureau or bureaus your lender uses.
-
Review your credit report for errors.
-
Pay EMIs and credit card bills on time.
-
Keep credit card utilisation under control.
-
Avoid unnecessary loan applications within a short period.
-
Maintain a manageable level of existing debt.
Remember, a good credit score does not guarantee approval. Lenders also assess repayment capacity, income, employment or business stability, and their own eligibility criteria.
How to Improve Your Credit Profile Across All Bureaus
To build a healthy credit history, follow these practical habits:
Pay on time: Make all loan and credit card payments by their due dates.
Reduce outstanding balances: High credit utilisation can negatively affect your credit profile.
Check your reports regularly: Review the information maintained by CIBIL, Experian, and Equifax.
Dispute incorrect information: If you find an error, raise a dispute with the relevant bureau and contact the lender that reported it.
Apply for credit carefully: Multiple applications in a short period can lead to additional hard enquiries and may affect your profile.
Maintain older accounts responsibly: A longer, well-managed credit history can be beneficial, depending on the scoring model.
Frequently Asked Questions (FAQs)
1. Is CIBIL better than Experian and Equifax?
Not necessarily. All three are credit information companies. The most relevant score depends on which bureau your lender checks and the accuracy of your credit report.
2. Why is my CIBIL score different from my Experian score?
Differences may arise from reporting dates, credit information, and scoring methodologies.
3. Do banks check Equifax scores?
Eligible lenders may use Equifax reports as part of their credit assessment, depending on their policies.
4. Which credit score should I check before applying for a personal loan?
Check the score and report used by your intended lender. Reviewing reports from multiple bureaus can help you identify inconsistencies.
5. Can I improve my credit score in one month?
Improvements depend on your credit history and the actions taken. Consistent repayments and correcting verified errors may help, but no specific increase or timeline is guaranteed.
6. Does checking my own credit score reduce it?
Checking your own credit report is generally a soft enquiry and does not lower your score.
Conclusion
CIBIL, Experian, and Equifax all help borrowers and lenders understand credit history and repayment behaviour. Their scores may differ, but a difference does not automatically mean that one bureau is wrong.
The best approach is to maintain timely repayments, manage existing debt, monitor your reports, and correct inaccurate information. A consistent and accurate credit history can help you prepare for future borrowing.
Published on : 17th October 2026
Published by : yogendra
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disburse