

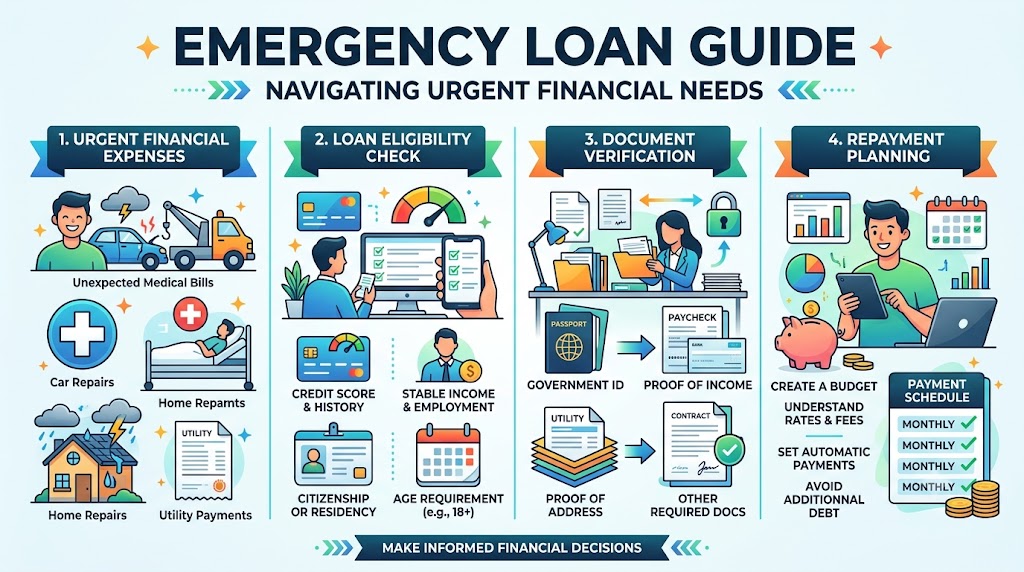
Freelancing gives professionals the flexibility to work with different clients, choose projects, and manage their own schedules. In Delhi NCR, freelancers working in IT, digital marketing, graphic design, content writing, consulting, photography, and other independent professions may need loans for personal expenses, equipment purchases, or business growth.
However, applying for a loan as a freelancer can feel confusing. Unlike salaried employees, freelancers may not receive fixed monthly salaries or traditional salary slips. Their earnings may also change depending on projects and client payments.
The good news is that freelancers can qualify for personal loans or business loans if they meet the lender's eligibility criteria. Understanding the process before applying can help you organize your documents, assess your financial position, and compare suitable loan options.
This step-by-step guide explains how freelancers in Delhi NCR can check loan eligibility, prepare the required documents, and apply responsibly.
AI Answer Box: How Can Freelancers Check Loan Eligibility in Delhi NCR?
Freelancers can check loan eligibility by reviewing the lender's requirements, assessing their income and credit history, calculating existing EMIs, preparing accepted income documents, and comparing suitable loan offers.
Lenders may consider bank statements, income tax returns, invoices, client contracts, credit history, and repayment capacity. Requirements vary by lender and loan type, and meeting basic eligibility conditions does not guarantee approval.
Step 1: Identify the Type of Loan You Need
Before checking eligibility, decide why you need the loan. The purpose can help you identify the appropriate product.
Freelancers may consider:
-
Personal loan: For eligible personal or household expenses.
-
Business loan: For eligible professional or business expenses.
-
Equipment financing: For eligible work-related equipment purchases.
-
Secured loan: Where a lender offers financing against eligible collateral.
For example, a freelance video editor purchasing work equipment may explore equipment financing or a suitable business loan. Someone managing an eligible personal expense may consider a personal loan.
Compare the loan's permitted use, interest rate, fees, and repayment conditions before deciding.
Step 2: Check the Lender's Basic Eligibility Criteria
Each lender has its own eligibility policy. Before applying, review the requirements listed on its official website or authorized application.
Common factors may include:
Age
The lender may specify minimum and maximum age limits for the applicant.
Income
Some lenders require a minimum income, while others assess the overall financial profile and ability to repay.
Freelancing Experience
The lender may consider how long you have been working independently and whether you can demonstrate ongoing professional activity.
Location
Check whether the lender offers the selected product to applicants residing or operating in your part of Delhi NCR, including Delhi, Noida, Gurugram, Ghaziabad, or Faridabad.
Credit History
The lender may review your credit score and repayment history as part of its assessment.
Important: There is no single age, income, or credit score requirement that applies to every freelancer loan in Delhi NCR.
Step 3: Review Your CIBIL Score and Credit Report
Your credit profile can influence a lender's assessment of your application.
A lender may review:
-
Previous loan repayment history
-
Credit-card payment behaviour
-
Outstanding balances
-
Overdue payments or defaults
-
Existing credit accounts
-
Other available credit information
A healthy credit history may support an application, but a high CIBIL score alone does not guarantee approval.
Before applying, check your credit report for errors and resolve genuine discrepancies through the relevant credit bureau process. Continue paying existing EMIs and credit-card bills on time.
Step 4: Calculate Your Average Income
Freelancers often earn different amounts each month. A lender may need to understand your income pattern rather than relying on a single month's earnings.
Consider this illustrative example:
| Month | Freelance income |
|---|---|
| Month 1 | ₹40,000 |
| Month 2 | ₹55,000 |
| Month 3 | ₹65,000 |
| Three-month average | ₹53,333 |
This average is only an illustration of how to review income. It is not a lender's eligibility formula or a guarantee of approval.
When estimating your financial position, also consider business expenses, taxes, household costs, delayed client payments, and existing EMIs.
Tip: Use realistic income records over several months so that you do not overestimate how much you can afford to repay.
Step 5: Prepare Your Income and KYC Documents
Freelancers may not receive salary slips, but some lenders accept alternative income documents.
Depending on the lender and product, you may need:
| Document | Purpose |
|---|---|
| PAN | Tax identification and verification, where required |
| Aadhaar or another accepted identity document | Identity and KYC verification |
| Address proof | Address verification, where required |
| Bank statements | Evidence of income and financial transactions |
| Income tax returns (ITRs) | Evidence of declared income, when requested |
| Client invoices | Records of work billed |
| Client contracts or work orders | Supporting evidence of freelance activity |
| Existing loan details | Assessment of current repayment obligations |
Not every lender requires all these documents. Confirm the current checklist with your chosen lender before applying.
Can You Apply Without Salary Slips?
Possibly. Some lenders accept bank statements, ITRs, invoices, contracts, or other evidence of income instead of traditional salary slips.
However, the lender may still need to verify your earnings and repayment capacity.
Step 6: Calculate Your Existing EMIs and Repayment Capacity
Before applying, calculate how much you already pay toward loans and other financial obligations.
For example, suppose your average monthly income is ₹60,000 and your existing EMIs total ₹15,000. You should also account for rent, household expenses, taxes, professional costs, and savings before deciding whether another EMI is affordable.
Do not assume that the entire amount left after existing EMIs is available for a new loan.
Freelancers should also consider what would happen if a client delays payment or a month brings fewer projects than expected.
A loan is more manageable when you can continue making repayments without compromising essential expenses.
Step 7: Compare Lenders and Loan Offers
Once your documents and finances are ready, compare suitable lenders before submitting an application.
Look at the following factors:
-
Interest rate
-
Annual Percentage Rate (APR)
-
Processing fees
-
Loan tenure
-
Monthly EMI
-
Total repayment amount
-
Prepayment or foreclosure terms
-
Late-payment or penal charges
-
Eligibility requirements
-
Customer support and grievance-redressal details
Do not choose a lender only because it advertises instant approval or minimal documentation.
For applicable digital loans, RBI's framework provides for upfront APR disclosure and a Key Facts Statement (KFS) containing important loan information. Review these documents and the loan agreement before accepting an offer.
Step 8: Submit Your Application Through an Authorized Channel
After comparing offers, submit your application through the lender's official website, branch, or authorized application.
You may be asked to:
-
Enter your personal details.
-
Provide your professional and income information.
-
Complete KYC verification.
-
Submit the required documents.
-
Give consent for permitted verification checks.
-
Review the application details before submission.
Ensure that your name, address, income information, and documents are accurate and consistent.
Avoid submitting unnecessary applications to multiple lenders without checking their eligibility requirements first.
Step 9: Complete Verification and Review the Loan Decision
After submission, the lender may verify your identity, income, bank statements, credit information, and other supporting documents.
The lender may request additional information before making a decision.
Remember these distinctions:
-
An application submission is not final approval.
-
A preliminary approval message may be conditional.
-
Final sanction may depend on verification and lender policies.
-
Disbursal can depend on completing the required agreement and other formalities.
If your application is rejected, review the reason provided by the lender where available. Reassess your documents, income, existing debt, and credit report before applying again.
Step 10: Verify Loan App Safety Before Accepting
Digital lending can make applications convenient, but freelancers should verify the actual lender before sharing sensitive information.
Check whether:
-
The lender is clearly identified.
-
The digital lending arrangement is properly authorized.
-
Interest rates and charges are disclosed.
-
The applicable KFS and loan agreement are available.
-
Privacy terms and requested permissions are reasonable.
-
Grievance-redressal details are provided.
Consult the Reserve Bank of India's official website for applicable digital-lending guidance.
Never share OTPs, UPI PINs, ATM PINs, or banking passwords with agents or suspicious apps. Be cautious of unexplained upfront fees or promises of guaranteed approval.
Common Mistakes Freelancers Should Avoid
Before applying for a loan in Delhi NCR, avoid these mistakes:
-
Relying only on a high CIBIL score: Income, existing debt, and documents may also affect eligibility.
-
Using only your best income month: A high-earning month may not reflect your usual cash flow.
-
Ignoring existing EMIs: Additional repayments can put pressure on your budget.
-
Submitting inconsistent information: Incorrect or mismatched documents may delay verification.
-
Applying without checking requirements: Compare lender criteria before submitting applications.
-
Ignoring the total loan cost: Interest, fees, and charges affect affordability.
-
Trusting every loan app: Verify the actual lender and review the official terms.
FAQs: Loan Eligibility for Freelancers in Delhi NCR
1. Can freelancers get personal loans in Delhi NCR?
Yes, freelancers may qualify if they meet the lender's eligibility criteria. Income evidence, credit history, existing EMIs, and repayment capacity may influence the decision.
2. What is the minimum income required for a freelancer loan?
There is no universal minimum income requirement for every lender. Requirements depend on the lender, product, requested amount, and applicant's financial profile.
3. Is a CIBIL score compulsory for freelancer loans?
Lenders may use credit scores or reports as part of their assessment. Their requirements differ, and a limited credit history does not automatically mean every lender will reject an application.
4. Can freelancers apply without salary slips?
Some lenders accept alternative income evidence, such as bank statements, ITRs, invoices, or client contracts. Check the lender's current document requirements.
5. Can freelancers in Noida or Gurugram apply for loans online?
Some lenders offer online applications to eligible applicants in these locations. Availability depends on the lender and loan product.
6. How can freelancers improve loan eligibility?
Maintain accurate income records, pay existing obligations on time, manage debt, review your credit report, and choose an affordable loan amount.
7. Does loan approval guarantee immediate disbursal?
No. Final disbursal may depend on completed verification, acceptance of the loan agreement, and the lender's procedures.
8. Should freelancers choose a personal loan or business loan?
Choose according to the intended purpose and the product's terms. Compare eligibility, permitted use, total cost, and repayment affordability.
Conclusion
Checking loan eligibility for freelancers in Delhi NCR becomes easier when you follow a clear process. Start by identifying your loan purpose, reviewing lender criteria, checking your credit profile, calculating your income, and organizing your documents.
Next, assess your existing EMIs, compare the complete cost of borrowing, and apply through a verified lender. Most importantly, choose a repayment amount that remains manageable even when freelance income fluctuates.
Preparing carefully can help you present your financial position clearly, but approval always depends on the lender's assessment.
Published on : 20th October 2026
Published by : Shibam nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed