

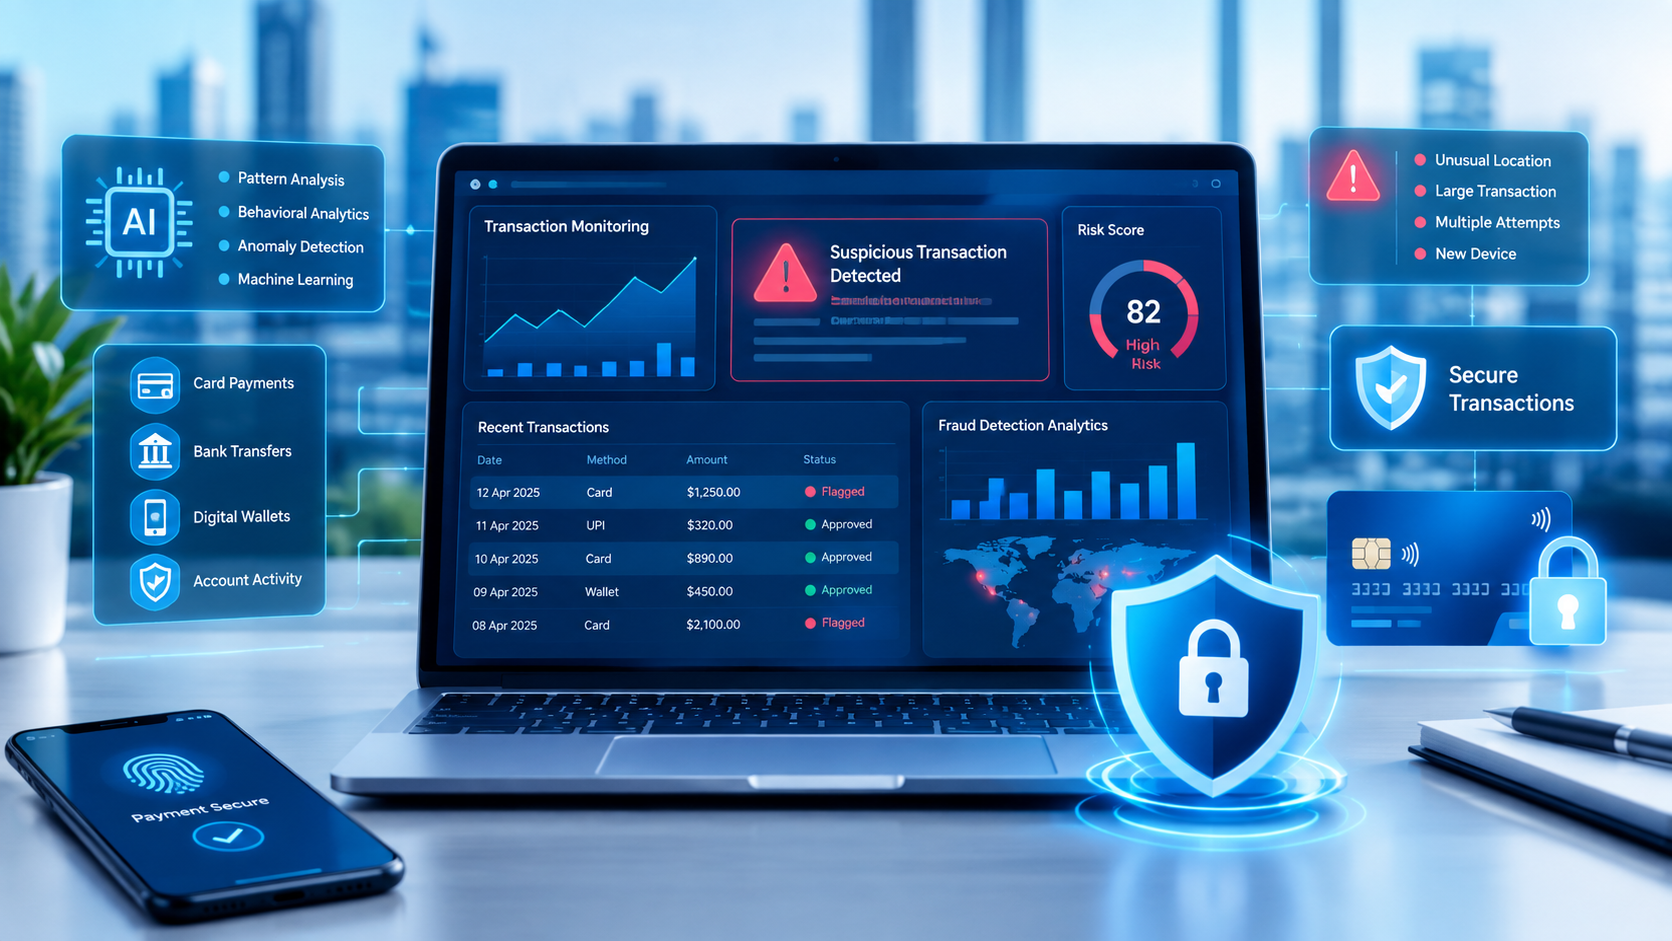
Fraud detection has become an essential part of modern financial security.
As banking, shopping, lending, payments, and customer interactions move online, fraudsters have more opportunities to exploit stolen credentials, compromised accounts, fake identities, social engineering, and suspicious transactions.
Fraud detection refers to the processes, technologies, rules, and analytical techniques used to identify potentially fraudulent activity before or after financial or business losses occur.
A modern fraud detection system may examine hundreds of signals, including:
- Transaction amount
- Location
- Device information
- Login behavior
- Transaction frequency
- Customer history
- Account activity
- Identity information
- Payment patterns
- Network and behavioral signals
The objective is not simply to block every unusual transaction. A useful system must distinguish between legitimate unusual activity and genuinely suspicious behavior while minimizing false positives.
This guide explains how fraud detection works, the most common types of fraud, technologies used by organizations, warning signs consumers should recognize, and practical fraud-prevention measures.
AI Answer Box: What Is Fraud Detection?
Fraud detection is the process of identifying suspicious activity that may indicate financial, payment, identity, insurance, lending, or other forms of fraud.
Organizations typically combine transaction rules, customer information, behavioral analysis, device intelligence, anomaly detection, machine learning, and human investigation.
For example, if a payment pattern suddenly differs significantly from a customer's normal behavior, a fraud detection system may flag the transaction for additional verification.
In simple terms:
Fraud detection = collecting signals + identifying unusual behavior + assessing risk + investigating or stopping potentially fraudulent activity.
Fraud detection and fraud prevention are closely related, but they are not exactly the same.
- Fraud detection: Identifies suspicious activity.
- Fraud prevention: Attempts to stop fraud before a loss occurs.
- Fraud investigation: Examines suspected fraud and gathers evidence.
- Fraud response: Takes appropriate action after fraud is identified.
What Is Fraud Detection?
Fraud detection is a structured approach to finding activity that does not appear legitimate.
It can be performed before a transaction, during a transaction, or after a transaction has already occurred.
For example:
A bank may analyze a card transaction in real time and compare it with the customer's normal spending behavior. If multiple risk indicators appear, the transaction may receive additional verification.
Fraud detection can be used across many industries.
| Industry | Examples of Fraud Detection |
|---|---|
| Banking | Suspicious transfers and account takeover |
| Credit cards | Unusual card transactions |
| Lending | Identity and application fraud |
| E-commerce | Fake accounts and payment fraud |
| Insurance | Suspicious claims |
| Fintech | Account and payment monitoring |
| Telecom | SIM-related and account fraud |
| Government | Benefit and identity fraud |
| Healthcare | Billing and identity irregularities |
| Marketplaces | Fake buyers, sellers, or transactions |
Why Is Fraud Detection Important?
Financial fraud can affect individuals, businesses, financial institutions, and entire digital ecosystems.
The consequences may include:
- Direct financial losses
- Identity theft
- Account takeover
- Customer dissatisfaction
- Operational costs
- Regulatory exposure
- Reputational damage
- Loss of trust
- Increased investigation costs
For businesses, fraud detection is therefore not merely a cybersecurity function. It can become an important part of financial risk management and customer protection.
Common Types of Fraud
Fraud takes many forms, and criminals continually adapt their techniques.
1. Payment Fraud
Payment fraud involves unauthorized or deceptive financial transactions.
Examples include:
- Stolen card transactions
- Unauthorized online payments
- Fake payment requests
- Manipulated payment instructions
- Account-to-account payment fraud
2. Identity Fraud
Identity fraud occurs when someone's personal information is misused to impersonate them or obtain services.
Information that may be targeted includes:
- Name
- Phone number
- Government identification information
- Bank information
- Account credentials
- Email credentials
3. Account Takeover Fraud
Account takeover occurs when an unauthorized person gains control of another person's account.
Warning signs can include:
- Unexpected password-reset messages
- Unknown login notifications
- Changes to account information
- New devices appearing on an account
- Unexpected transactions
4. Loan and Application Fraud
Lending businesses can encounter fraudulent applications involving false, stolen, manipulated, or misleading information.
Fraud detection may examine:
- Identity consistency
- Application information
- Document signals
- Device information
- Application patterns
- Previous account activity
Fraud detection should not automatically treat unusual circumstances as fraud. Suspicious indicators generally require appropriate verification.
5. E-Commerce Fraud
Online businesses may encounter:
- Stolen payment details
- Fake accounts
- Refund abuse
- Coupon abuse
- Friendly fraud
- Automated attacks
- Account takeover
6. Insurance Fraud
Insurance fraud can involve deliberately misleading information or fabricated circumstances to obtain an improper benefit.
Detection can involve:
- Claim history
- Claim timing
- Documentation
- Customer information
- Patterns across multiple claims
7. Social Engineering Fraud
Social engineering involves manipulating people into revealing information or authorizing actions.
Common examples include:
- Phishing
- Fake customer-support calls
- Impersonation
- Investment scams
- Urgent payment requests
- Fake loan offers
How Does Fraud Detection Work?
A typical fraud detection workflow can be divided into several stages.
Step 1: Data Collection
A system gathers relevant information.
Depending on the organization, this may include:
- Transaction details
- Account history
- Device data
- IP-related signals
- Login information
- Customer behavior
- Payment information
- Identity information
Step 2: Risk Analysis
The system evaluates the available signals.
A transaction may appear more suspicious when multiple unusual characteristics occur together.
Step 3: Rules and Risk Scores
Organizations can use predefined rules and risk-scoring models.
For example:
Multiple unusual transactions within a short period may trigger additional verification.
A single unusual event does not necessarily prove fraud.
Step 4: Machine Learning and Analytics
More advanced systems can identify patterns that are difficult to capture through simple rules.
Machine-learning systems can analyze historical data and identify relationships between multiple variables.
Step 5: Alert or Action
Depending on the risk level, an organization may:
- Approve the transaction
- Request additional authentication
- Hold the transaction
- Send an alert
- Refer the activity for investigation
- Decline the transaction
Step 6: Investigation
Human investigators can review suspicious activity and determine what additional evidence is required.
Step 7: Feedback
Confirmed cases can provide useful information for improving future detection systems.
Fraud Detection Methods
There is no single method that identifies every type of fraud.
Organizations commonly combine several approaches.
Rule-Based Fraud Detection
Rule-based systems use predefined conditions.
Example:
If several high-risk characteristics occur simultaneously, trigger additional verification.
Advantages
- Easy to understand
- Fast
- Relatively straightforward to implement
- Useful for known fraud patterns
Limitations
- Can become difficult to maintain at scale
- May miss previously unknown patterns
- Fraudsters can adapt to predictable rules
Anomaly Detection
Anomaly detection looks for behavior that differs significantly from expected patterns.
For example, a system might identify:
- Unusual transaction frequency
- Unexpected geographic behavior
- Unusual account activity
- Sudden changes in spending patterns
An anomaly does not automatically mean fraud.
This distinction is important because legitimate customers can behave unusually.
Machine Learning Fraud Detection
Machine learning can identify patterns from historical data.
Depending on the application, models can analyze combinations of:
- Transaction characteristics
- User behavior
- Device signals
- Historical activity
- Account relationships
- Timing
- Geographic information
Machine learning can help organizations identify complex patterns that may be difficult to express through manual rules.
Real-Time Fraud Detection
Real-time fraud detection analyzes activity while a transaction or account event is taking place.
This can be particularly useful for:
- Card payments
- Digital wallets
- Online transfers
- Account logins
- E-commerce purchases
The key benefit is speed: suspicious activity can potentially be identified before a transaction is completed.
AI and Fraud Detection
Artificial intelligence is increasingly being used in fraud analytics.
AI-based systems can process large volumes of data and identify relationships among multiple signals.
Potential applications include:
- Behavioral analysis
- Anomaly detection
- Transaction monitoring
- Identity verification
- Risk scoring
- Account takeover detection
- Pattern recognition
However, AI is not a magic solution.
A fraud detection model can produce false positives and false negatives. Organizations therefore need appropriate data governance, monitoring, validation, human oversight, and security controls.
Fraud Detection vs Fraud Prevention
These terms are often used interchangeably, but they describe different activities.
| Fraud Detection | Fraud Prevention |
|---|---|
| Identifies suspicious activity | Attempts to stop fraud |
| Focuses on detection | Focuses on risk reduction |
| Uses alerts and monitoring | Uses controls and safeguards |
| Can occur during or after activity | Ideally occurs before loss |
| May involve investigation | May involve authentication or blocking |
In practice, organizations generally need both.
Fraud Detection vs Fraud Investigation
Fraud detection identifies potentially suspicious behavior.
Fraud investigation goes further by examining the circumstances surrounding the suspected activity.
| Detection | Investigation |
|---|---|
| Finds suspicious signals | Examines evidence |
| Often automated | Often involves human review |
| Generates alerts | Determines what happened |
| Can operate in real time | May take longer |
| Supports early intervention | Supports resolution |
Common Warning Signs of Fraud
Consumers and businesses should pay attention to unusual activity.
Common warning signs include:
- Unexpected account-login alerts
- Unrecognized transactions
- Urgent requests for money
- Requests for passwords or OTPs
- Unexpected changes to account details
- Pressure to bypass normal procedures
- Suspicious links
- Fake customer-support messages
- Requests to install unfamiliar software
- Offers that require unusual payment methods
A warning sign alone does not prove fraud. Verification through a trusted channel is important.
How to Detect Financial Fraud
A practical approach is to monitor several signals rather than relying on one indicator.
For Individuals
1. Monitor bank and payment accounts
Review statements and transaction notifications regularly.
2. Enable transaction alerts
Where available, configure alerts for:
- Payments
- Withdrawals
- Transfers
- Login attempts
- Profile changes
3. Protect authentication information
Never share:
- Passwords
- PINs
- OTPs
- Authentication codes
4. Verify unexpected requests
If someone claims to represent a bank or financial institution, independently contact the organization using an official channel.
5. Report suspicious activity quickly
Fast reporting can help reduce additional unauthorized activity.
How Businesses Can Build a Fraud Detection System
A business developing a fraud detection program should consider the entire risk lifecycle.
Step 1: Identify Fraud Risks
Map the organization's major fraud scenarios.
For example:
- Payment fraud
- Identity fraud
- Refund fraud
- Account takeover
- Application fraud
Step 2: Define Risk Signals
Identify information that may help distinguish legitimate activity from suspicious activity.
Step 3: Create Appropriate Controls
Controls can include:
- Authentication
- Transaction monitoring
- Device intelligence
- Rules
- Risk scoring
- Manual review
Step 4: Monitor Performance
Measure:
- Fraud detection rate
- False-positive rate
- Investigation volume
- Customer friction
- Response time
- Financial losses
Step 5: Continuously Improve
Fraud patterns change. Detection systems should therefore be reviewed and updated regularly.
Fraud Detection Tools and Technologies
Modern fraud management may combine several technologies.
| Technology | Typical Purpose |
|---|---|
| Rules engines | Known fraud patterns |
| Machine learning | Complex pattern detection |
| Behavioral analytics | Detect unusual user behavior |
| Device intelligence | Identify suspicious devices |
| Identity verification | Confirm customer identity |
| Transaction monitoring | Monitor financial activity |
| Risk scoring | Prioritize suspicious events |
| Case management | Support investigations |
| Data analytics | Identify broader fraud patterns |
Pros and Cons of Automated Fraud Detection
Pros
- Processes large transaction volumes
- Can operate continuously
- Can identify suspicious patterns quickly
- Reduces manual workload
- Supports real-time monitoring
- Can combine many risk signals
Cons
- False positives can inconvenience legitimate customers
- Models require quality data
- Fraud patterns change
- Systems can be expensive to develop
- Poorly designed automation can create customer friction
- Human investigation may still be necessary
Rule-Based vs AI-Based Fraud Detection
| Feature | Rule-Based | AI/ML-Based |
|---|---|---|
| Known fraud patterns | Strong | Strong |
| Adaptability | Limited | Potentially higher |
| Explainability | Usually high | Depends on model |
| Large-scale pattern analysis | Limited | Strong |
| Maintenance | Manual rule updates | Requires model monitoring |
| Human oversight | Important | Important |
Many organizations use a hybrid approach rather than choosing only one technology.
Real-World Fraud Detection: Practical Lessons
Fraud detection systems work best when technology is combined with sound processes.
Lesson 1: Context matters
A transaction that appears unusual in isolation may be legitimate when viewed in context.
Lesson 2: Multiple signals are stronger than one
A combination of unusual account behavior, device changes, transaction velocity, and authentication anomalies can provide more useful context than a single indicator.
Lesson 3: False positives matter
Blocking legitimate customers can create frustration and operational costs.
Lesson 4: Fraud changes over time
Fraudsters adapt when organizations improve their controls.
Lesson 5: Human review remains valuable
Automated systems can prioritize cases, while investigators can examine context that an automated model may not fully understand.
Expert Commentary: What Makes Fraud Detection Effective?
A practical fraud program should balance security, accuracy, speed, and customer experience.
Security teams often need to answer three questions:
- Is the activity unusual?
- Does the activity match known risk indicators?
- What action is proportionate to the risk?
The third question is particularly important.
A system that blocks every unusual transaction may reduce some fraudulent activity but can also create unnecessary friction for legitimate users.
Effective fraud management therefore focuses on risk-based decision-making, continuous monitoring, appropriate authentication, and regular system improvement.
Fraud Detection Best Practices
Organizations can strengthen fraud detection by following several principles.
1. Use layered security
Do not depend on a single control.
2. Monitor continuously
Fraud can occur outside normal business hours.
3. Keep customer information secure
Limit access to sensitive data.
4. Use strong authentication
Additional verification can help protect sensitive actions.
5. Review false positives
A detection system should be evaluated for both missed fraud and incorrectly flagged legitimate activity.
6. Train employees
Human behavior remains an important part of fraud prevention.
7. Maintain an incident-response process
Know what happens when fraud is suspected.
8. Update detection rules
Threat patterns change over time.
Fraud Detection Checklist
For Consumers
Enable banking alerts
Use strong, unique passwords
Enable available multi-factor authentication
Never share OTPs or PINs
Verify unexpected payment requests
Review account statements
Report suspicious transactions promptly
Avoid suspicious links and attachments
For Businesses
Map fraud risks
Monitor transactions
Establish risk rules
Use appropriate authentication
Monitor account behavior
Measure false positives
Investigate suspicious activity
Review fraud trends regularly
Maintain an incident-response plan
Key Takeaways
- Fraud detection identifies potentially fraudulent activity using data, rules, analytics, and human investigation.
- Modern systems may analyze transaction, behavioral, device, identity, and account signals.
- AI and machine learning can help identify complex patterns, but they do not eliminate the need for human oversight.
- An unusual transaction is not automatically fraudulent.
- Fraud detection and fraud prevention are related but different functions.
- Strong authentication, monitoring, employee awareness, and rapid reporting are important parts of fraud risk management.
- Businesses should regularly evaluate false positives as well as fraud detection performance.
- Consumers should independently verify unexpected requests for money, passwords, OTPs, or account information.
AI Summary for Search Engines and AI Assistants
Fraud detection is the process of identifying potentially fraudulent activity using transaction monitoring, rules, behavioral analytics, identity signals, anomaly detection, machine learning, and human investigation. Common applications include banking, lending, payments, e-commerce, insurance, and digital financial services. Effective fraud detection combines multiple signals and risk controls while balancing fraud prevention with customer experience and false-positive management.
Frequently Asked Questions About Fraud Detection
1. What is fraud detection?
Fraud detection is the process of identifying transactions, accounts, applications, or behaviors that may indicate fraudulent activity.
2. How does fraud detection work?
Fraud detection systems analyze information such as transaction behavior, account history, device signals, identity information, and other risk indicators to identify potentially suspicious activity.
3. What are the most common types of fraud?
Common types include payment fraud, identity fraud, account takeover, application fraud, e-commerce fraud, insurance fraud, and social engineering scams.
4. What is AI fraud detection?
AI fraud detection uses artificial intelligence and machine-learning techniques to identify suspicious patterns and unusual behavior in large datasets.
5. Can AI completely prevent fraud?
No. AI can support fraud detection and prevention, but no detection system can guarantee that every fraudulent event will be identified or prevented.
6. What is real-time fraud detection?
Real-time fraud detection analyzes activity as it happens and can trigger verification, alerts, holds, or other controls when suspicious signals are detected.
7. What is transaction monitoring?
Transaction monitoring is the ongoing review of financial activity to identify unusual or potentially suspicious transactions.
8. How can individuals detect financial fraud?
Individuals can monitor account activity, enable alerts, use strong authentication, verify unexpected requests, and report unauthorized transactions promptly.
9. What is the difference between fraud detection and fraud prevention?
Fraud detection focuses on identifying suspicious activity, while fraud prevention focuses on controls designed to stop or reduce fraudulent activity.
10. What causes false positives in fraud detection?
False positives can occur when a legitimate transaction resembles suspicious behavior or when detection rules are overly sensitive.
11. Why is machine learning used for fraud detection?
Machine learning can analyze large datasets and identify complex patterns that may be difficult to capture through manually written rules alone.
12. What industries use fraud detection?
Banking, lending, insurance, e-commerce, fintech, healthcare, telecommunications, government services, and payment providers can use fraud detection techniques.
13. What should I do if I notice a fraudulent transaction?
Contact the relevant bank, payment provider, or financial institution through an official channel as soon as possible and follow its fraud-reporting procedure.
14. Is an unusual transaction always fraudulent?
No. Legitimate customers can make unusual purchases or access accounts from new locations or devices. Suspicious activity should be appropriately verified before being classified as fraud.
15. Why is fraud detection important for businesses?
Fraud detection can help businesses identify suspicious activity, reduce financial losses, protect customers, manage operational risk, and strengthen trust in digital services.
Fraud Detection References and Authoritative Sources
For further reading and current guidance, useful authoritative resources include:
- Reserve Bank of India (RBI) — banking and payment-system guidance
- Indian Cyber Crime Coordination Centre (I4C) — cybercrime awareness and reporting resources
- National Payments Corporation of India (NPCI) — digital payment ecosystem information
- U.S. Federal Trade Commission (FTC) — consumer fraud and identity-theft resources
- Federal Bureau of Investigation (FBI) — financial and cybercrime information
- Association of Certified Fraud Examiners (ACFE) — occupational fraud research
- National Institute of Standards and Technology (NIST) — cybersecurity guidance
Vizzve Financial
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Before applying for any financial product, review the applicable eligibility requirements, interest rate, fees, repayment terms, and other conditions carefully.
Conclusion
Fraud detection is an important part of protecting modern financial systems.
As transactions become increasingly digital, organizations need more than a single fraud rule or security tool. Effective fraud management combines transaction monitoring, behavioral analysis, authentication, risk assessment, technology, employee awareness, and appropriate human review.
For individuals, the fundamentals remain straightforward: monitor financial accounts, protect authentication information, verify unexpected requests, and report suspicious activity quickly.
For businesses, the goal is broader—build a layered system that can identify risk while minimizing unnecessary disruption to legitimate customers.
The strongest fraud detection strategy is not simply about detecting more alerts. It is about identifying meaningful risk, responding appropriately, learning from confirmed incidents, and continuously improving controls.
Published on : 23rd september
Published by : Sumanth Arumulla
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed
#FinancialSecurity #CyberSecurity #AI #AIFraudDetection #MachineLearning #FraudAnalytics #PaymentSecurity #BankingSecurity #DigitalPayments #OnlineSecurity #IdentityTheft #AccountSecurity #TransactionMonitoring #FinTech #FinancialTechnology #CyberFraud #RiskManagement #DigitalSecurity #FinancialSafety #VizzveFinancial