

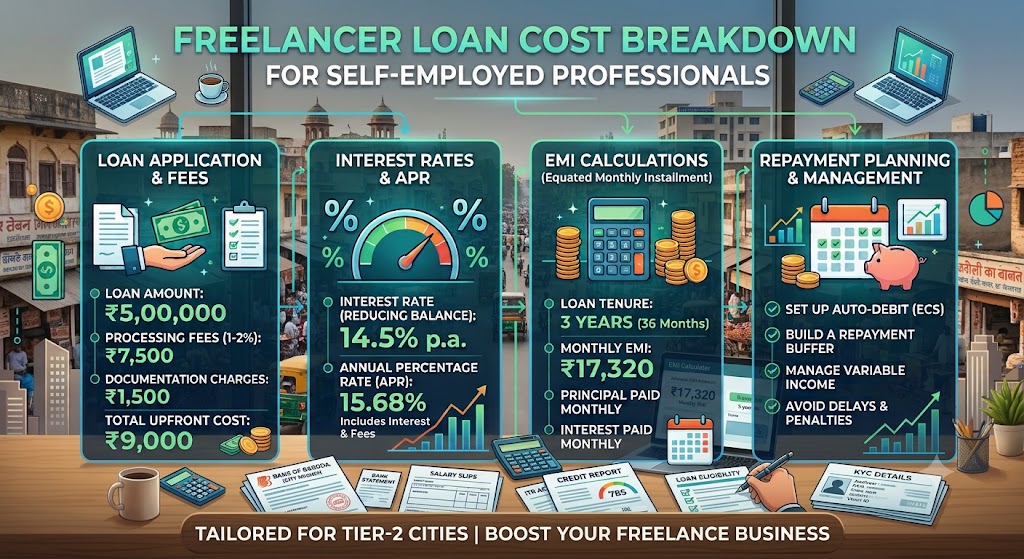
Freelancing is creating new income opportunities across India's Tier-2 cities. Content writers, graphic designers, software developers, digital marketers, consultants and other independent professionals can earn through client projects, retainers and online platforms.
However, getting a personal loan as a freelancer may require extra preparation. Unlike salaried employees who often receive regular monthly payslips, freelancers may have fluctuating income, multiple clients and irregular payment schedules. Lenders may review income records, credit history, existing EMIs and repayment capacity before making a decision.
Before applying, freelancers should understand the lender's eligibility requirements, prepare the necessary documents and compare the total cost of borrowing.
In this guide, Vizzve explains what freelancers in Tier-2 cities should check before applying for a personal loan and how to prepare for the application process.
AI Answer Box: What Should Freelancers Check Before Applying for a Loan?
Before applying for a personal loan, freelancers should check their credit report, income records, bank statements, existing EMIs, KYC documents and the lender's eligibility criteria. They should also calculate an affordable EMI, compare the interest rate and Annual Percentage Rate (APR), and review the Key Facts Statement (KFS) and loan agreement before accepting an offer.
Eligibility requirements vary by lender, loan product and borrower profile. Meeting the basic criteria does not guarantee loan approval.
1. Check Whether the Lender Accepts Freelancers
The first step is to confirm that the lender offers loans to freelancers or self-employed professionals.
Not every lender follows the same eligibility policy. Some may accept freelance income supported by bank statements, Income Tax Returns (ITRs), invoices or contracts. Others may have specific requirements related to work history, income consistency or business documentation.
Before applying, check:
-
Whether freelancers are eligible for the selected loan product
-
Whether the lender serves your city or location
-
The minimum age and income requirements
-
Any required work or business history
-
Accepted income documents
-
The lender's application and verification process
Do not assume that eligibility rules are identical across all lenders or Tier-2 cities.
2. Review Your CIBIL Score and Credit Report
Your credit history may be an important part of the lender's assessment. Before applying, review your credit report to identify potential issues.
Check for:
-
Late or missed EMI payments
-
Outstanding loan balances
-
Credit-card dues
-
Incorrect personal details
-
Accounts that do not belong to you
-
Unfamiliar credit enquiries
A healthy credit history can support your application, but a high score does not guarantee approval or a particular interest rate.
What to do: If you find an error, contact the relevant credit bureau or lender to dispute it. If you have outstanding dues, review your repayment plan before taking on another loan.
3. Organise Your Freelance Income Documents
Freelancers may receive money from multiple clients, and monthly earnings can vary. Keeping financial records organised can help you explain your income when the lender requests evidence.
Depending on the lender's requirements, useful documents may include:
-
Recent bank statements
-
ITRs, where applicable
-
Client invoices
-
Contracts or work orders
-
Payment receipts
-
Business income and expense records
-
Other documents specifically requested by the lender
Keep the information accurate and consistent. Do not inflate earnings or submit altered documents to improve your eligibility.
How to Demonstrate Income Consistency
If your income changes each month, maintain a record of your earnings over time. Track client payments, business expenses and periods when work is limited. This can help you understand your own repayment capacity, although the lender decides which income evidence it will accept.
4. Calculate Your Existing EMI Burden
Before applying, calculate how much of your income is already committed to debt repayments.
Existing personal loans, vehicle loans and credit-card obligations may affect the amount you can comfortably repay. Freelancers should also consider taxes, household expenses, business costs and months when client payments are delayed.
For example, suppose your average monthly income is ₹50,000 and you already pay ₹12,000 in EMIs. You would have ₹38,000 remaining before accounting for other expenses and savings. A new EMI must fit within your actual budget, not just your income figure.
Before applying:
-
Calculate average monthly income.
-
List all existing EMIs and debt payments.
-
Estimate the EMI for the proposed loan.
-
Deduct essential personal and business expenses.
-
Check whether repayments remain manageable in a low-income month.
Avoid borrowing the maximum amount offered if it could make your finances difficult to manage.
5. Check Your KYC Documents
Know Your Customer (KYC) verification helps lenders establish your identity and verify the information in your application.
Depending on the lender and product, you may be asked for PAN, accepted identity and address proof, bank-account information and other supporting documents.
Before submitting your application, make sure:
-
Your name matches across documents
-
Your address and contact details are current
-
Your bank-account information is correct
-
Required documents are readable and valid
-
Information in the application matches the supporting records
Only submit documents through the lender's official or authorised channels. Never share OTPs, UPI PINs, ATM PINs or banking passwords with loan agents.
6. Compare Interest Rates, APR and Other Charges
Do not choose a loan based only on its advertised interest rate. The overall cost may also include processing fees, applicable taxes on fees and other disclosed charges.
Compare these details across suitable offers:
| Loan detail | What to check |
|---|---|
| Interest rate | Whether the rate is fixed or variable, where applicable |
| APR | The disclosed annualised cost of borrowing |
| Processing fee | Fee and any applicable taxes |
| EMI | Amount payable each month |
| Loan tenure | How long repayments continue |
| Total repayment | Overall amount payable under the offer |
| Late-payment charges | Charges if a payment is overdue |
| Prepayment terms | Conditions and any applicable charges |
| Net disbursal | Amount you will actually receive |
For digital loans covered by applicable RBI requirements, the lender should provide a Key Facts Statement (KFS) with important loan terms and costs, including APR. Review the document before accepting the loan. RBI digital-lending guidance provides further regulatory information.
7. Verify the Actual Lender and Loan App
Freelancers looking for quick funding may encounter apps that advertise instant or guaranteed approval. Treat such claims cautiously.
Before applying, confirm the name of the bank or Non-Banking Financial Company (NBFC) actually providing the loan. Review the lender's official website, loan terms, privacy policy and grievance redressal details.
Watch out for warning signs such as:
-
The actual lender is not identified
-
Interest rates and fees are hidden
-
Guaranteed approval is promised without proper assessment
-
Unexplained upfront payments are demanded
-
The app requests unnecessary access to personal information
-
Someone asks for your OTP, PIN or banking password
RBI's regulatory framework addresses borrower creditworthiness, disclosures and safeguards in covered digital-lending arrangements. Read the RBI digital-lending directions.
8. Check Whether the Loan Amount Is Affordable
Choose a loan amount based on your actual financial needs and repayment capacity.
Freelancers may experience slow business periods, delayed invoices or changes in client demand. A high EMI can become difficult to manage if income falls unexpectedly.
Consider these factors before choosing the amount:
-
Average and lowest monthly earnings
-
Existing EMIs
-
Essential household expenses
-
Business costs and taxes
-
Emergency savings
-
Total interest and fees
-
Expected loan tenure
A smaller loan with a manageable repayment schedule may be more appropriate than a larger loan that puts pressure on your monthly budget.
9. Understand the Loan Agreement Before Signing
An approval message is not a reason to accept an offer without reviewing the terms.
Read the KFS and loan agreement carefully. Confirm that the amount, EMI, interest rate and charges match the offer you intended to accept.
Pay attention to:
-
Sanctioned amount and net disbursal
-
APR and applicable fees
-
EMI amount and due dates
-
Late-payment terms
-
Prepayment conditions
-
Loan tenure
-
Grievance redressal contact details
Ask the lender for clarification if any term is unclear. Keep a copy of the loan documents for future reference.
10. Avoid Applying to Too Many Lenders at Once
Submitting several loan applications in a short period may result in multiple formal credit enquiries. These enquiries may affect your credit profile, depending on the circumstances.
Instead, compare lenders before applying. Check whether they accept freelancers, what documentation they require and whether their criteria match your profile.
Apply selectively and avoid unnecessary repeat applications, especially if you have not addressed the reason for an earlier rejection.
Freelancer Loan Readiness Checklist
Use this checklist before submitting your application.
-
Confirm that the lender accepts freelancers.
-
Review your credit report.
-
Organise bank statements and income records.
-
Prepare the required KYC documents.
-
Calculate existing EMIs and other obligations.
-
Estimate an affordable new EMI.
-
Compare APR, fees and total repayment.
-
Verify the actual lender and its official channels.
-
Read the KFS and loan agreement.
-
Keep copies of submitted documents and the final loan offer.
How Freelancers in Tier-2 Cities Can Prepare Better
Good preparation can make the application process more organised, although approval remains the lender's decision.
Maintain clear financial records: Keep invoices, payment receipts, contracts and bank records organised.
Pay existing debts on time: Timely repayments can help maintain a positive credit history.
Keep documents updated: Make sure your identity, address and financial information are accurate.
Build emergency savings: Savings can help cover essential expenses during periods of irregular income.
Borrow responsibly: Choose an amount and tenure that fit your budget, and compare the full borrowing cost rather than relying on promotional claims.
FAQs: Loan Eligibility for Freelancers in Tier-2 Cities
1. Can freelancers in Tier-2 cities apply for personal loans?
Yes. Some lenders accept freelancers and self-employed professionals. Eligibility depends on the lender's policies, income evidence, credit history and repayment capacity.
2. What should a freelancer check before applying for a loan?
Check lender eligibility, credit history, income documents, KYC details, existing EMIs, affordability, APR, fees and the loan agreement.
3. Can freelancers apply without salary slips?
Some lenders may accept bank statements, ITRs, invoices, contracts or other income evidence instead of salary slips. Requirements vary by lender.
4. Is a CIBIL score enough to get a personal loan?
No. Credit score is only one part of the assessment. Lenders may also consider income, existing debt, documentation and their own eligibility criteria.
5. What income proof may a freelancer need?
Depending on the lender, acceptable documents may include bank statements, ITRs, invoices, client contracts, payment receipts and financial records.
6. Can irregular income affect loan eligibility?
It can affect how a lender assesses repayment capacity. Some lenders may review income history and supporting records, but their requirements differ.
7. Should freelancers check existing EMIs before applying?
Yes. Existing EMIs and other debt obligations can affect how much additional repayment a borrower can manage.
8. What is APR on a personal loan?
APR stands for Annual Percentage Rate. It represents the annualised cost of borrowing under the applicable framework and helps borrowers compare loan offers.
9. What is a KFS?
KFS means Key Facts Statement. It sets out important loan information, including applicable costs and terms, before the loan contract is executed where required.
10. How can freelancers avoid fraudulent loan apps?
Verify the actual lender, review the loan terms and privacy policy, and avoid apps that hide fees or ask for OTPs, PINs or banking passwords.
11. Does living in a Tier-2 city guarantee loan approval?
No. Location alone does not guarantee eligibility. Approval depends on the lender's criteria and the applicant's financial profile.
12. What should a freelancer do if a loan application is rejected?
Review the reason, check the credit report, correct documentation issues and reassess affordability before applying again. Avoid submitting repeated applications without understanding the problem.
Conclusion
Before applying for a personal loan, freelancers in Tier-2 cities should check lender eligibility, review their credit history, organise income documents, calculate existing EMIs and understand the total cost of borrowing.
Careful preparation can help freelancers make more informed decisions and avoid preventable application issues. However, no checklist can guarantee approval.
Published on : 23rd October 2026
Published by : Shibam nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed