

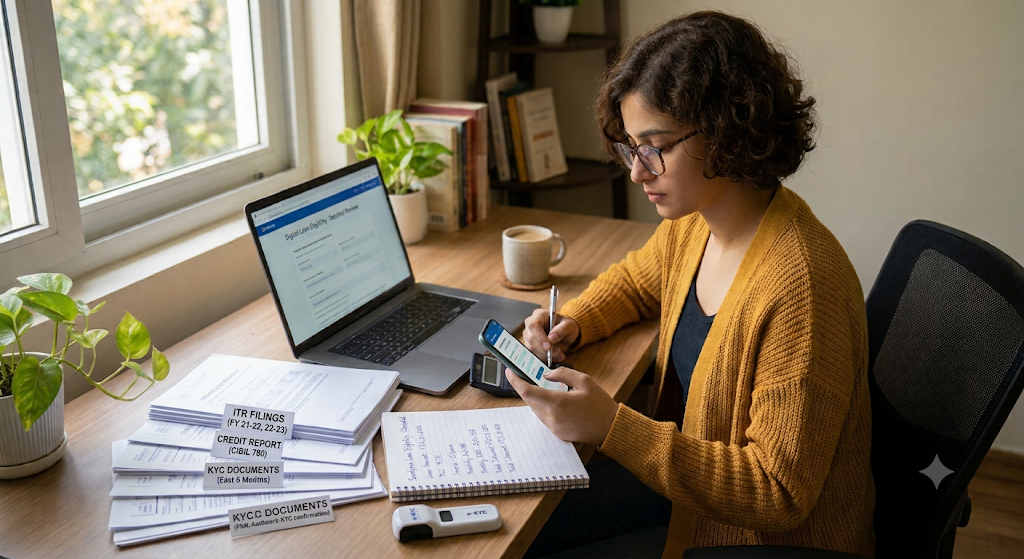
Applying for a loan through a smartphone can make the borrowing process more convenient for freelancers. Mobile-first loan applications allow applicants to review eligibility conditions, submit documents, complete digital KYC and track application updates online.
However, completing an application does not automatically mean a loan will be approved. Lenders may assess freelance income, credit history, ITR, bank statements, existing EMIs, KYC details and repayment capacity before making a decision.
A clear eligibility checklist can help freelancers understand what to prepare before applying and identify areas that may need attention.
AI Answer Box: What Is the Loan Eligibility Checklist for Freelancers?
Freelancers applying for a mobile loan should check their credit history, documented income, bank statements, ITR, identity documents, existing EMIs and repayment capacity. They should also review the lender's eligibility conditions, verify the actual lending institution and compare the APR, fees and total repayment before accepting an offer. Exact requirements vary by lender and loan product.
Freelancer Loan Eligibility Checklist
Use this checklist before starting a mobile loan application.
1. Age and Basic Eligibility
<text> </text>
-
I meet the lender's minimum age requirement.
-
I have valid identity and address information.
-
I meet the lender's residential eligibility conditions.
-
I have an active mobile number for application communication and verification.
-
I have reviewed the loan product's basic eligibility criteria.
Lenders may have different age limits, location requirements and other conditions. Check the official eligibility details before applying.
2. Freelance Income Verification
Freelancers may earn through consulting, design, writing, development, marketing, online platforms, professional services or project-based assignments.
Since freelance income may not arrive as a fixed monthly salary, lenders can review financial records to understand the applicant's earnings.
-
I can explain my main sources of freelance income.
-
I have records of payments received from clients.
-
I can provide bank statements if required.
-
I have kept invoices and payment receipts.
-
I can demonstrate my income pattern over time.
-
My declared income is consistent with my supporting documents.
Tip: Do not report an unusually high earning month as your regular income. Use accurate figures supported by your financial records.
3. ITR and Financial Documents
Income Tax Returns can help demonstrate reported earnings and provide additional information about a freelancer's financial position.
Before applying, check whether you have the documents requested by the lender.
| Document | Eligibility checklist |
|---|---|
| PAN | [ ] Available and accurate |
| ITR | [ ] Available, if required |
| Bank statements | [ ] Updated and readable |
| Client invoices | [ ] Organized |
| Work contracts | [ ] Available, if applicable |
| Payment records | [ ] Available |
| GST records | [ ] Available, where applicable |
Not every lender requires all these documents. Confirm the accepted documents for the particular loan product.
4. Credit Score and Repayment History
Your credit history can be an important part of the lender's assessment.
Review the following before submitting an application:
-
I have checked my credit report.
-
I have reviewed my previous loan repayment history.
-
I have checked my credit-card payment records.
-
I know my outstanding loan balances.
-
I have reviewed recent credit enquiries.
-
I have identified any incorrect entries in my credit report.
-
I am paying existing EMIs on time.
A good credit history may support an application, but no single credit-score figure guarantees approval from every lender.
5. Existing Loans and EMI Obligations
Lenders may consider your existing financial commitments when assessing whether you can manage another loan.
Check whether you have:
-
Personal loan EMIs
-
Home loan EMIs
-
Vehicle loan EMIs
-
Credit-card repayments
-
Other regular debt obligations
For example, if your dependable monthly income is ₹45,000 and your existing EMIs total ₹10,000, you should consider your remaining living expenses and business costs before taking on another EMI.
The example is illustrative. Lenders may use their own methods to evaluate income and repayment capacity.
6. Digital KYC and Identity Verification
Mobile-first loan applications may allow applicants to complete identity verification digitally.
Before starting KYC, check:
-
My PAN details are correct.
-
My Aadhaar or other accepted identity document is valid, if required.
-
My name and date of birth match my documents.
-
My address information is accurate.
-
My bank-account details are correct.
-
I am completing KYC through the genuine lender's authorized channel.
Important safety reminder: Never share OTPs, UPI PINs, ATM PINs, card PINs or internet-banking passwords with an agent or suspicious app. Do not upload sensitive documents through unverified links.
7. Mobile Application Readiness
A mobile-first application may require you to enter personal and financial information and upload documents.
Check the following:
-
I am using the official lender website or authorized application.
-
I have reviewed the app's permissions.
-
I understand why the lender needs the requested information.
-
My documents are clear and readable.
-
I have a reliable internet connection.
-
I have reviewed the privacy and consent information.
-
I know how to contact the lender's official customer-support team.
Convenience should not replace verification. Confirm the actual lender before sharing financial information.
8. Loan Amount and Repayment Capacity
Before applying, decide how much you actually need.
Consider:
-
I have calculated my actual borrowing requirement.
-
I have estimated the monthly EMI.
-
I have considered income fluctuations.
-
I have included regular household expenses.
-
I have considered business-related expenses.
-
I can manage repayments during lower-income months.
-
I have avoided borrowing more than necessary.
Freelancers should be especially careful about taking on fixed monthly repayments when their income changes from month to month.
9. Interest Rate, APR and Other Charges
Do not compare loan offers only by their advertised interest rates.
Before accepting an offer, check:
| Loan detail | What to verify |
|---|---|
| Interest rate | Applicable rate and calculation method |
| APR | Overall annualized borrowing cost |
| Processing fee | Amount and applicable taxes |
| EMI | Monthly repayment amount |
| Tenure | Repayment duration |
| Late-payment charges | Applicable penalties or charges |
| Prepayment terms | Conditions for early repayment |
| Total repayment | Overall amount payable |
For applicable digital loans, the Key Facts Statement (KFS) provides important information about loan costs and terms. Read it carefully before accepting the loan agreement.
Quick Freelancer Loan Eligibility Self-Assessment
The following table can help you identify what to review before applying.
| Eligibility area | What a prepared applicant should have |
|---|---|
| Basic details | Accurate personal information |
| Freelance income | Documented and explainable earnings |
| ITR | Available if requested |
| Bank statements | Relevant financial records |
| Credit history | Reviewed for errors and repayment issues |
| Existing debt | Current EMIs and obligations calculated |
| KYC | Valid and consistent identity details |
| Repayment capacity | Affordable EMI based on dependable income |
| Loan costs | APR, fees and total repayment reviewed |
| Lender verification | Actual lender and authorized app confirmed |
This is a preparation checklist, not an official eligibility score or guarantee of approval.
What If You Cannot Tick Every Eligibility Box?
Not having every document immediately available does not always mean you are ineligible. The requirements depend on the lender and loan product.
Consider these practical steps:
If you do not have a salary slip: Check whether the lender accepts ITR, bank statements, invoices or other income records.
If your income is irregular: Organize payment records and review your earnings over several months.
If your credit report has errors: Raise a dispute with the relevant credit bureau.
If your existing EMIs are high: Review your budget and avoid taking on repayments you cannot comfortably manage.
If KYC information does not match: Correct genuine errors through the relevant official process before applying.
If you are unsure about an app: Verify the actual lender and its authorized lending arrangements before sharing information.
Common Eligibility Mistakes Freelancers Should Avoid
-
Providing unsupported income figures: Always use accurate information that can be verified.
-
Ignoring existing EMIs: Consider all current repayment obligations.
-
Submitting unclear documents: Upload complete and readable records.
-
Applying without checking credit history: Review your report first.
-
Choosing the maximum loan amount: Borrow according to your actual need and affordability.
-
Ignoring APR and fees: Compare the complete borrowing cost.
-
Trusting instant approval messages: Preliminary eligibility is not final sanction.
-
Using unverified loan apps: Confirm the lender before sharing personal and financial information.
Final Checklist Before Submitting a Mobile Loan Application
-
I meet the lender's basic eligibility conditions.
-
I can document my freelance income.
-
I have organized my bank statements and ITR, if required.
-
I have reviewed my credit report.
-
I know my existing EMI obligations.
-
My KYC information is accurate.
-
I have selected a realistic loan amount.
-
I can manage the expected EMI.
-
I have checked the interest rate and APR.
-
I have reviewed the processing fee and other charges.
-
I have verified the actual lender.
-
I have read the KFS and loan agreement.
Key Takeaways
-
Freelancers can explore mobile-first loan applications, subject to lender-specific eligibility requirements.
-
Documented freelance income, ITR and bank statements may help lenders assess earnings.
-
Credit history, existing EMIs and repayment capacity can influence loan decisions.
-
Digital KYC should be completed only through genuine and authorized channels.
-
Compare APR, fees, EMI and total repayment before accepting an offer.
-
A completed checklist or preliminary eligibility result does not guarantee final approval.
-
Always verify the actual lender and read the loan documents carefully.
FAQs
1. What documents do freelancers need for mobile loan eligibility?
Depending on the lender, freelancers may need PAN, accepted KYC documents, bank statements, ITR, client invoices, contracts and payment records.
2. Can freelancers apply for a personal loan without a salary slip?
Yes, some lenders may accept alternative income documents such as ITR, bank statements, invoices and contracts. Requirements vary.
3. Is ITR compulsory for freelancer loans?
Not for every loan product. However, some lenders may request ITR as evidence of reported income.
4. Does freelance income need to be regular for loan approval?
Not necessarily, but lenders may assess income patterns and supporting financial records to understand repayment capacity.
5. Can a freelancer with existing EMIs apply for another loan?
A freelancer may apply, but existing repayment obligations can affect the lender's assessment of affordability and eligibility.
6. Does a good credit score guarantee freelancer loan approval?
No. Credit history is only one part of the assessment. Income, documentation, existing debt and lender-specific requirements may also matter.
7. Is digital KYC required for mobile loan applications?
Many digital loan processes involve identity verification. The exact method and documents depend on the lender.
8. How can freelancers check whether a loan app is genuine?
Identify the actual lender, verify its regulated status and confirm that the app or service provider is authorized to act on its behalf. Review the loan terms and privacy information before sharing documents.
9. What should freelancers check before accepting a loan?
Review the lender's identity, interest rate, APR, EMI, tenure, fees, total repayment, KFS and loan agreement.
10. Does completing a loan eligibility checklist mean the loan will be approved?
No. A checklist helps applicants prepare, but the lender makes the final decision after its verification and credit assessment.
Published on : 4th November 2026
Published by : Shibam nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed