

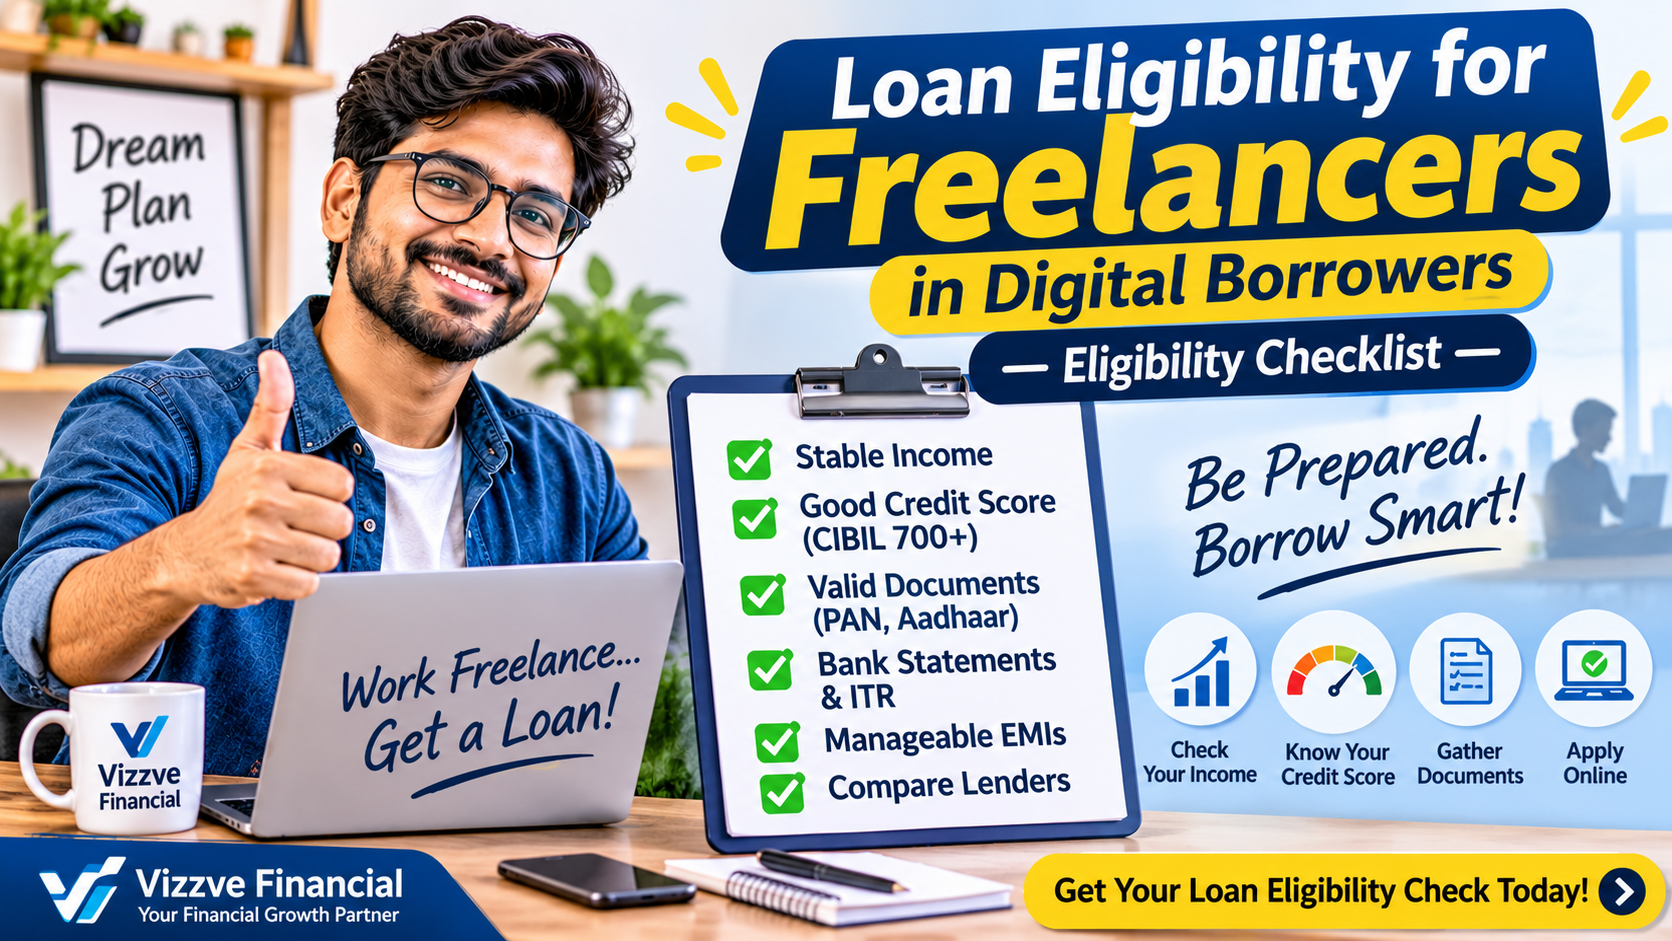
Freelancing gives professionals the freedom to choose projects, work with different clients and earn independently. From content writers and graphic designers to software developers, consultants, digital marketers and online tutors, many Indians now depend on freelance work as their primary source of income.
But when a freelancer needs financial assistance, one important question often comes up: Am I eligible for a personal loan without a regular salary slip?
The answer is yes. Freelancers can apply for personal loans from eligible banks and NBFCs, provided they meet the lender's requirements and can demonstrate their repayment capacity.
However, the eligibility process may look different from that of a salaried employee. Lenders may review freelance earnings, bank statements, tax records, credit history and existing financial commitments.
This guide provides a practical loan eligibility checklist for freelancers in India so you can prepare before submitting an application.
Quick Answer: What Do Freelancers Need to Qualify for a Loan?
Freelancers generally need to demonstrate that they have a reliable source of income and can repay the loan.
Depending on the lender, the main eligibility factors may include:
-
Meeting the lender's age requirements.
-
Having sufficient and verifiable income.
-
Demonstrating reasonable income consistency.
-
Maintaining a suitable credit history.
-
Managing existing EMIs responsibly.
-
Providing valid identity and address documents.
-
Submitting acceptable income proof.
-
Meeting the lender's other internal requirements.
There is no single eligibility standard followed by every bank or NBFC. Requirements vary according to the lender, loan product and applicant profile.
1. Check Your Basic Personal Eligibility
Before applying, review the basic personal details that lenders may consider.
Personal eligibility checklist
-
I meet the lender's minimum age requirement.
-
I meet the lender's maximum age requirement at loan maturity.
-
I have valid identity documents.
-
I can provide acceptable address proof.
-
My personal details are consistent across documents.
-
I can complete the lender's verification process.
Age limits and accepted documents differ between lenders. Check the latest conditions before applying.
2. Check Your Freelance Income
Income is one of the most important parts of a freelancer's loan application.
Unlike salaried employees, freelancers may receive different amounts every month. Some months may bring several projects, while others may have fewer assignments.
Lenders may therefore examine income records over a period to understand your earning pattern.
Income eligibility checklist
-
I know my average monthly freelance income.
-
I receive payments through traceable channels.
-
I maintain bank statements showing income credits.
-
I have invoices or receipts for completed projects.
-
I can provide client agreements where available.
-
I maintain records of payments received through freelance platforms.
-
My declared income is consistent with my available financial records.
How to calculate average monthly income
Use this simple formula:
Average Monthly Income = Total Income Over a Period ÷ Number of Months
For example, suppose your freelance earnings over six months are:
| Month | Freelance income |
|---|---|
| January | ₹35,000 |
| February | ₹45,000 |
| March | ₹50,000 |
| April | ₹40,000 |
| May | ₹55,000 |
| June | ₹45,000 |
| Total | ₹2,70,000 |
Average monthly income:
₹2,70,000 ÷ 6 = ₹45,000
Your average monthly freelance income is ₹45,000.
This is a personal budgeting calculation. A lender may use a different method and may consider business expenses, income stability, taxes and other commitments.
3. Review Your Credit Score and Credit History
Your credit profile can influence how a lender assesses your application.
In India, credit information companies such as TransUnion CIBIL maintain credit records. The CIBIL Score generally ranges from 300 to 900.
A healthy credit history may support your application, but a high score alone does not guarantee loan approval.
Credit score checklist
-
I have checked my latest credit report.
-
I pay existing loan EMIs on time.
-
I pay credit card bills by their due dates.
-
I avoid unnecessary credit applications.
-
I keep my credit utilisation under control.
-
I have checked for incorrect entries in my credit report.
-
I have addressed overdue payments, if any.
What if you have no credit history?
Some freelancers may have never used a credit card or taken a formal loan. This can result in a limited credit history.
A lender may consider other financial information as part of its assessment, depending on its policies. Check whether the lender accepts alternative income and financial records.
4. Prepare Your Income Documents
Freelancers usually do not receive traditional salary slips. Instead, they may use other documents to demonstrate earnings.
Income document checklist
-
Recent bank statements.
-
Income Tax Returns, where required.
-
Freelance invoices.
-
Client contracts or work agreements.
-
Payment platform statements.
-
Receipts for completed projects.
-
Other income or business records requested by the lender.
Why are bank statements important?
Bank statements can help demonstrate how regularly you receive payments and how you manage your finances.
For example, regular credits from multiple clients may help explain your freelance income pattern.
However, bank statements alone may not be sufficient for every lender. Additional documents may be requested.
5. Check Your Existing Loans and EMI Commitments
Your existing financial obligations can affect how much you may be able to borrow.
Before applying, calculate the total amount you pay every month towards existing loans and other debt commitments.
Existing EMI checklist
-
I know the total amount of my current EMIs.
-
I have checked my outstanding loan balances.
-
I understand my credit card repayment obligations.
-
I have considered rent, household costs and business expenses.
-
I can manage another EMI without financial stress.
-
I have considered what happens if my freelance income decreases.
Example of repayment capacity
Suppose your average monthly freelance income is ₹50,000.
| Financial detail | Amount |
|---|---|
| Average monthly income | ₹50,000 |
| Existing loan EMI | ₹5,000 |
| Monthly business expenses | ₹7,000 |
| Other essential expenses | ₹18,000 |
| Amount remaining before a new EMI | ₹20,000 |
This example helps you understand your personal budget. It does not represent a lender's eligibility formula.
A new EMI should leave enough room for essential expenses, savings and unexpected income fluctuations.
6. Keep Your Identity and Address Documents Ready
Identity verification is a standard part of many loan application processes.
Identity and address checklist
-
PAN Card or other accepted identity document.
-
Aadhaar or another accepted address document, where applicable.
-
Current residential address details.
-
Active mobile number.
-
Email address.
-
Bank account details.
-
Any additional KYC documents requested by the lender.
Make sure your details are accurate and consistent. Do not upload altered or misleading documents.
7. Check Your Freelance Work History
Your professional experience can help explain the nature of your income.
Lenders may have different requirements regarding the length of self-employment or freelance activity.
Work history checklist
-
I can explain my freelance occupation clearly.
-
I have records of completed projects.
-
I maintain a client list or portfolio where appropriate.
-
I have records of repeat clients.
-
I can provide work agreements or orders if requested.
-
I can explain gaps or major changes in my income.
A longer work history may provide more evidence of earning continuity, but approval still depends on the lender's complete assessment.
8. Check the Loan Amount You Actually Need
Before applying, decide how much you need and whether the repayment amount fits your income.
Avoid choosing a loan amount simply because a lender or advertisement displays a large possible limit.
Loan amount checklist
-
I have calculated the exact amount I need.
-
I have compared different repayment tenures.
-
I understand the interest rate and APR.
-
I have checked the processing fee and other charges.
-
I know the total repayment amount.
-
I can manage the EMI during a low-income month.
A smaller, affordable loan may be more suitable than taking on a large repayment obligation.
9. Compare Lenders Before Applying
Different banks and NBFCs may have different eligibility requirements for freelancers.
Compare more than just the advertised interest rate.
Lender comparison checklist
-
The lender is a legitimate bank or regulated NBFC.
-
Freelancer or self-employed applicants are accepted.
-
The income documentation requirements are clear.
-
The interest rate is disclosed.
-
The APR is available.
-
Processing fees and other charges are explained.
-
Prepayment and foreclosure conditions are clear.
-
The grievance-redressal process is available.
-
The loan agreement can be reviewed before acceptance.
Do not submit applications to several lenders unnecessarily. Multiple formal credit enquiries over a short period may affect your credit profile.
10. Digital Lending Safety Checklist
Digital loan applications can make the process more convenient, but borrowers should verify the lender and understand how their information is handled.
Before using a digital lending platform, check the following:
-
I have verified the actual bank or NBFC providing the loan.
-
I am using an official website or verified application.
-
I have read the privacy policy.
-
I understand what personal information is collected.
-
I have reviewed the interest rate and APR.
-
I have read the Key Facts Statement, where applicable.
-
I have checked all fees and charges.
-
I have not shared my OTP, PIN or banking password.
-
I have avoided suspicious advance-payment requests.
-
I know how to contact the lender for complaints or support.
The RBI's Digital Lending Directions, 2025 provide a regulatory framework for digital lending by regulated entities. Borrowers should still verify the lender and read all disclosures before accepting credit.
11. Common Reasons Freelancers May Not Meet Loan Eligibility
Even if you are earning regularly, your application may not meet a lender's requirements.
| Possible issue | What you can do |
|---|---|
| Irregular income | Maintain clear records of earnings over time |
| Insufficient income proof | Organise bank statements, invoices and tax records |
| Low credit score | Review your credit report and improve repayment habits |
| High existing EMIs | Reduce outstanding debt where practical |
| Short freelance history | Build a consistent record of work and payments |
| Incomplete documents | Check the lender's document list before applying |
| Incorrect application details | Verify all information before submission |
If your application is declined, review the reason and address the issue before applying again.
12. Final Freelancer Loan Eligibility Checklist
Use this quick checklist before submitting your application.
Personal details
-
I meet the lender's age requirements.
-
My identity and address documents are valid.
-
My contact details are up to date.
Income and work
-
I have calculated my average monthly income.
-
I can provide bank statements.
-
I have invoices or payment records.
-
I have supporting work documents where available.
-
I can explain my income pattern.
Credit and repayment
-
I have reviewed my credit report.
-
I pay existing EMIs on time.
-
I know my current debt commitments.
-
I can comfortably manage the proposed EMI.
Loan and lender
-
I have compared suitable lenders.
-
I have checked the interest rate and APR.
-
I understand all applicable fees.
-
I have reviewed the repayment schedule.
-
I have verified the actual lender.
-
I have read the loan terms before accepting.
If you cannot tick every item, do not panic. Some documents may not apply to every applicant. Check the specific lender's requirements and prepare the missing information before proceeding.
Frequently Asked Questions (FAQs)
1. Can freelancers apply for personal loans in India?
Yes. Freelancers can apply for personal loans from eligible banks and NBFCs if they meet the lender's income, credit and documentation requirements.
2. Is a salary slip compulsory for freelancer loans?
Not necessarily. Freelancers may provide alternative income evidence, such as bank statements, ITRs, invoices and client contracts, depending on the lender's policy.
3. What documents should freelancers prepare for a loan?
Commonly requested documents may include PAN, accepted identity and address proof, bank statements, ITRs, invoices and client agreements.
4. Is a CIBIL Score important for freelancers?
Yes. Lenders may review your credit score and repayment history when assessing a loan application. Other factors, including income and existing debt, also matter.
5. Can a freelancer with irregular income get a personal loan?
It may be possible. The lender may review income records over time to understand earning patterns and repayment capacity.
6. What is the minimum income required for a freelancer loan?
There is no universal minimum income requirement. Each lender sets its own eligibility conditions.
7. Can gig workers use this eligibility checklist?
Yes. Delivery partners, online service providers, independent consultants and other gig workers can use it to organise their financial records before applying.
8. Are ITR documents necessary for freelancer loans?
Some lenders may request ITRs, while others may accept alternative income documents. Confirm the requirements directly with the lender.
9. Does having an existing loan affect freelancer loan eligibility?
It can. Lenders may consider your existing EMIs and outstanding debt when evaluating your ability to repay another loan.
10. How can I improve my freelancer loan eligibility?
Maintain a healthy credit profile, organise income records, reduce unnecessary debt, pay EMIs on time and apply for an amount that fits your repayment capacity.
11. Can I check freelancer loan eligibility online?
Many lenders provide online eligibility checks or application facilities. A preliminary result does not guarantee final loan approval.
12. Is instant loan approval guaranteed for digital borrowers?
No. Online applications may simplify submission, but final approval depends on verification and the lender's credit assessment.
13. Can I use freelance platform earnings as income proof?
Some lenders may accept platform payment statements or transaction records. Acceptance depends on the lender's documentation policy.
14. Should I apply to multiple lenders at once?
Avoid unnecessary applications. Multiple formal credit enquiries within a short period may affect your credit profile.
15. What should I check before accepting a personal loan?
Review the Key Facts Statement, APR, interest rate, processing fees, repayment schedule, late-payment charges and prepayment conditions.
Key Takeaways
-
Freelancers can apply for personal loans in India.
-
Salary slips are not the only way to demonstrate income.
-
Bank statements, invoices and tax records may support income verification.
-
Credit history and existing EMIs can affect eligibility.
-
Requirements differ across banks and NBFCs.
-
Compare APR, fees and repayment terms before accepting a loan.
-
Verify digital lenders and protect your personal information.
-
Borrow only an amount you can comfortably repay.
Conclusion: Be Loan-Ready Before You Apply
A little preparation can make the loan application process easier to understand. Freelancers should focus on maintaining clear income records, checking their credit history, organising documents and calculating affordable repayments.
This eligibility checklist can help digital borrowers identify what they need before approaching a lender. While meeting the checklist does not guarantee approval, it can help you submit a more complete and accurate application.
Want to learn more about responsible digital borrowing? Visit Vizzve Financial for financial information and borrowing awareness.
Disclaimer: This article is for educational purposes only and does not guarantee loan eligibility or approval. Eligibility criteria, documentation, interest rates and charges vary by lender. Verify all terms directly with the relevant bank or NBFC before applying.
Published on : 4th November 2026
Published by : Shanlee JV
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed