

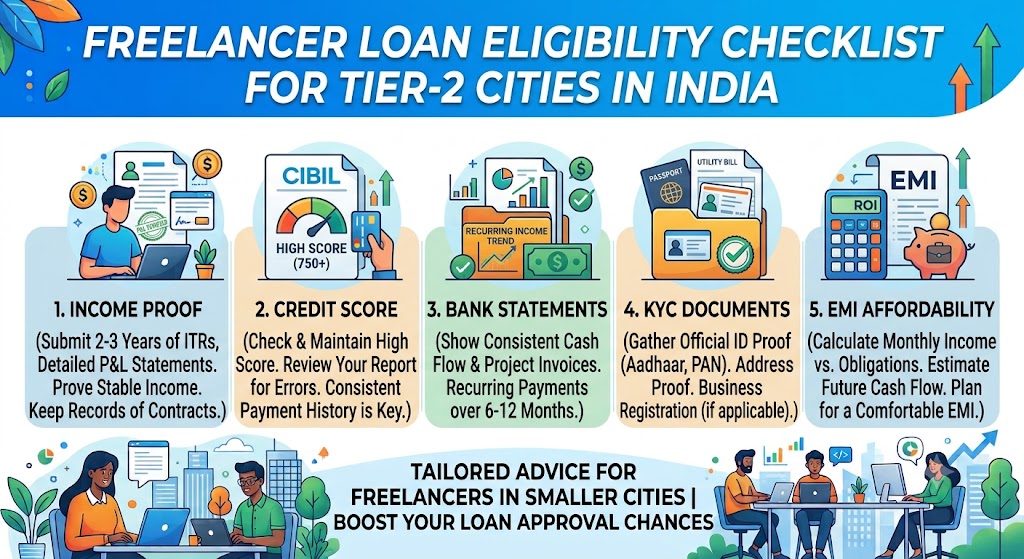
Introduction
Freelancing is creating new income opportunities across India's Tier-2 cities. Content writers, graphic designers, software developers, digital marketers, consultants and other independent professionals can work with clients across India and abroad.
However, getting a personal loan as a freelancer may require additional preparation. Unlike salaried employees, freelancers may not receive fixed monthly salaries or traditional salary slips. Lenders may instead assess bank statements, tax records, client payments, credit history and repayment capacity.
Understanding loan eligibility for freelancers in Tier-2 cities can help you prepare the right documents, check your financial readiness and avoid common application mistakes.
This Vizzve guide provides a practical eligibility checklist for freelancers who are considering a personal loan.
What Is Loan Eligibility for Freelancers?
Loan eligibility refers to the conditions a lender uses to assess whether an applicant qualifies for a loan.
For freelancers, these conditions may include:
-
Minimum and maximum age requirements
-
Documented income and earnings stability
-
Credit score and repayment history
-
Existing loans and monthly EMIs
-
Freelance or self-employment history
-
KYC and income verification
-
The lender's service availability in the applicant's location
Requirements vary by lender and loan product. Living in a Tier-2 city does not automatically guarantee or prevent loan approval.
Freelancer Loan Eligibility Checklist
1. Check the Lender's Eligibility Criteria
Before applying, confirm that the bank or non-banking financial company (NBFC) accepts freelancers and self-employed professionals.
Check whether you meet its stated requirements for age, income, professional experience, location and documentation.
Do not rely only on advertisements promising instant or guaranteed approval. Review the lender's official eligibility conditions before proceeding.
2. Review Your Freelance Income
Freelance income may change from month to month because of project availability, seasonal demand or delayed client payments.
Review your earnings over several months and calculate how much money remains after business expenses, taxes and essential household costs.
For example, if you earn ₹35,000 in one month, ₹50,000 in another and ₹40,000 in the third, your average monthly income across those three months is approximately ₹41,667 before expenses and taxes.
This is only an illustration. A lender may use a different period or method to assess income.
Checklist:
-
I have reviewed my recent income.
-
I can demonstrate where my earnings come from.
-
I have considered business expenses and taxes.
-
I can manage repayments during a low-income month.
3. Prepare Valid Income Documents
Freelancers may not have salary slips, but other documents can help demonstrate their earnings.
Depending on the lender's requirements, these may include:
-
Recent bank statements
-
Income Tax Returns (ITRs), where applicable
-
Client invoices and payment receipts
-
Freelance contracts or work orders
-
Relevant tax or professional income records
-
Additional documents requested by the lender
Keep all records genuine, accurate and up to date. Never submit fabricated invoices or alter financial documents to increase your apparent income.
4. Check Your CIBIL Score and Credit History
Your credit history can influence a lender's assessment of your application. A record of timely repayments may support your credit profile, while defaults, overdue accounts or high outstanding balances may create difficulties.
Before applying:
-
Review your credit report.
-
Check for incorrect personal or account details.
-
Identify outstanding dues and missed payments.
-
Pay existing EMIs and credit-card bills on time.
-
Raise a dispute if you find an error.
There is no single CIBIL score that guarantees approval from every lender. Income, debt obligations and lender-specific requirements also matter.
5. Calculate Existing EMIs and Repayment Capacity
If you already pay EMIs for a personal loan, vehicle loan or other credit facility, those obligations may reduce the amount you can comfortably borrow.
Calculate your monthly budget before applying. Include essential living costs, business expenses, taxes, existing repayments and emergency savings.
Checklist:
-
I know my total existing EMI commitments.
-
I have estimated my disposable income.
-
The proposed EMI fits my budget.
-
I can manage repayment if a client pays late.
Avoid borrowing the maximum amount offered if the resulting EMI would put pressure on your finances.
6. Keep KYC Documents Ready
Know Your Customer (KYC) verification helps lenders establish your identity.
Depending on the lender, you may need:
-
PAN
-
An accepted identity document
-
Address proof
-
Bank account details
-
Additional verification documents
Submit documents only through verified channels. Never disclose your OTP, password, UPI PIN or card security code to an agent claiming to process your application.
7. Check Your Work History
Some lenders may require a minimum period of freelance or self-employed activity. Others may assess income records and other factors according to their product rules.
Maintain contracts, invoices and payment records to demonstrate your professional activity where requested.
If you have recently started freelancing, check the lender's requirements before submitting an application.
8. Compare Loan Costs Before Applying
Eligibility is only one part of a borrowing decision. You should also understand how much the loan will cost.
Compare these factors:
| Factor | What to check |
|---|---|
| Interest rate | Understand the rate offered |
| Annual Percentage Rate (APR) | Review the overall annualised borrowing cost |
| Processing fee | Check the fee and applicable taxes |
| Loan tenure | Compare repayment periods |
| EMI | Make sure the monthly instalment is affordable |
| Late-payment charges | Understand the consequences of missed payments |
| Prepayment terms | Check any applicable conditions or charges |
| Total repayment | Calculate the total amount payable |
For applicable digital loans, review the Key Facts Statement (KFS) and other required disclosures. Read the loan agreement carefully before accepting the offer.
9. Verify the Lender and Digital App
If you apply online, confirm the identity of the actual bank or NBFC providing the loan. Check its official website and verify the app's association with the lender.
Be cautious if an agent demands an unexplained advance payment, promises guaranteed approval or asks for sensitive credentials. Do not install remote-access applications at the request of an unknown loan agent.
A legitimate-looking website or app is not sufficient proof that an offer is safe.
Quick Freelancer Loan Eligibility Checklist
Use this checklist to assess your readiness before applying.
| Eligibility factor | Ready to apply when… |
|---|---|
| Lender criteria | You have checked the requirements and location coverage |
| Income | Your earnings are documented |
| Income proof | Required financial records are available |
| Credit report | You have reviewed your credit history |
| Existing debts | You understand your current EMI commitments |
| Repayment capacity | The proposed EMI is affordable |
| KYC | Your identity and address documents are ready |
| Work history | You meet any applicable experience requirements |
| Loan costs | You understand APR, fees and total repayment |
| Safety | You have verified the lender and read the agreement |
This is a general readiness checklist, not a guarantee of eligibility or approval.
Common Mistakes Freelancers Should Avoid
-
Applying without checking whether the lender accepts freelancers.
-
Assuming that a salary slip is mandatory for every loan product.
-
Providing inconsistent or false income information.
-
Ignoring existing debts when choosing a loan amount.
-
Applying to many lenders without comparing their criteria.
-
Selecting a loan based only on the advertised EMI.
-
Trusting offers that promise guaranteed approval.
-
Sharing sensitive financial information through unverified links.
Preparing carefully can help you understand your options and make a more informed application.
Frequently Asked Questions (FAQs)
1. Can freelancers in Tier-2 cities get a personal loan?
Yes, some lenders accept eligible freelancers and self-employed professionals. Approval depends on income evidence, credit history, repayment capacity and the lender's requirements.
2. Is a salary slip required for a freelancer loan?
Not always. Some lenders accept bank statements, ITRs, invoices or other income documents instead. Confirm the requirements for the specific loan product.
3. Which documents are needed for a freelancer loan?
Depending on the lender, documents may include PAN, identity and address proof, bank statements, ITRs where applicable, invoices and client contracts.
4. Does CIBIL score affect freelancer loan eligibility?
Yes, a lender may review your credit score and repayment history. However, no single score guarantees approval across all lenders.
5. Can a new freelancer apply for a personal loan?
A new freelancer can explore available options, but some lenders may require a minimum period of professional activity or documented income history.
6. Does living in a Tier-2 city affect loan eligibility?
Your location alone does not determine eligibility. The lender's service availability and its assessment of your financial profile may affect the outcome.
7. How can freelancers improve their loan eligibility?
Maintain clear income records, pay existing dues on time, review your credit report, reduce unnecessary debt and apply for an affordable loan amount.
8. Can freelancers apply for a loan online?
Some lenders offer online applications. Verify the lender, review the privacy terms and compare loan costs before submitting your documents.
9. Is loan approval guaranteed if all documents are ready?
No. Complete documentation helps the lender evaluate your application, but approval depends on its eligibility rules and final assessment.
10. How much should a freelancer borrow?
Borrow only what you need and can repay comfortably. Base your decision on realistic income estimates, existing obligations, essential expenses and the total cost of the loan.
Conclusion
Understanding loan eligibility for freelancers in Tier-2 cities begins with checking lender requirements, reviewing income records, assessing your credit history and calculating repayment capacity.
Use this checklist to identify gaps before applying. Compare loan costs, verify the lender and choose an EMI that remains manageable even when freelance earnings fluctuate.
Responsible borrowing is not just about qualifying for a loan. It is also about making sure the repayment plan works for your financial situation.
Published on : 22nd October 2026
Published by : Shibam nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed