

Introduction
Freelancing offers flexibility and independence, but managing finances can sometimes be challenging. Freelancers in Delhi NCR, including Delhi, Noida, Gurugram, Ghaziabad and Faridabad, may experience fluctuating income, delayed client payments and difficulty providing traditional salary documents when applying for a personal loan.
Before applying, it is important to understand not only your loan eligibility but also how to protect yourself from misleading offers, hidden charges and fraudulent lending apps.
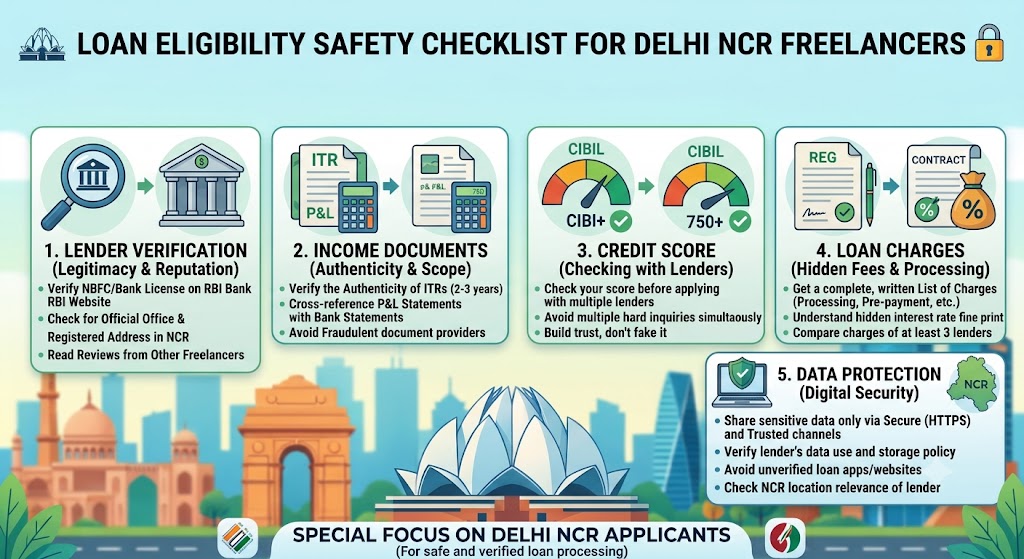
This loan eligibility safety checklist for freelancers in Delhi NCR explains what to verify before applying, which documents to prepare, how to review loan terms and what warning signs to avoid.
What Is Loan Eligibility for Freelancers?
Loan eligibility is the assessment a lender uses to determine whether an applicant meets its requirements for borrowing. For freelancers, the assessment may include income stability, bank statements, credit history, existing EMIs, identity verification and work-related income records.
Unlike salaried employees, freelancers may not have a fixed monthly salary slip. Depending on the lender, alternative documents such as Income Tax Returns (ITRs), invoices, client contracts and bank statements may help demonstrate income.
Eligibility requirements vary between banks, non-banking financial companies (NBFCs) and loan products. Meeting the basic criteria does not guarantee approval.
Freelancer Loan Safety Checklist: What to Verify Before Applying
1. Verify the Lender's Identity
Before submitting a loan application, identify the actual bank or NBFC providing the loan.
-
Check the lender's official website.
-
Confirm the lender's legal name and contact details.
-
If using a loan app or digital platform, verify its association with the regulated lender.
-
Check the Reserve Bank of India's Digital Lending Apps directory where applicable.
-
Avoid relying only on advertisements, social media posts or WhatsApp messages.
A professional-looking website or app does not automatically prove that a lending service is genuine.
2. Check Your Loan Eligibility Honestly
Review the lender's eligibility requirements before applying. These may include:
-
Minimum and maximum age limits
-
Minimum income requirements
-
Freelance or self-employment history
-
Credit score or credit history
-
Accepted income documents
-
Existing EMI obligations
-
Residential location and KYC requirements
Do not exaggerate your earnings or submit false employment details to qualify for a loan. Incorrect information may lead to rejection or other complications.
3. Prepare Genuine Income Documents
Freelancers should maintain organised records to support their loan application. Depending on the lender's requirements, useful documents may include:
-
Recent bank statements
-
ITRs or other relevant tax records
-
Client invoices and payment receipts
-
Contracts or work orders
-
PAN and accepted identity documents
-
Address proof
-
Other professional or business records requested by the lender
Ensure that the information is accurate and consistent. Never edit bank statements or create fake invoices to make your income appear higher.
4. Review Your Credit Report
Your credit profile can influence loan eligibility, interest rates and available loan options.
Before applying:
-
Review your credit report for incorrect information.
-
Check for overdue payments or outstanding debts.
-
Pay existing EMIs and credit-card bills on time.
-
Avoid making multiple unnecessary credit applications within a short period.
-
Raise a dispute if you identify an error in your report.
A good credit history can support your application, but approval also depends on income, repayment capacity and lender-specific criteria.
5. Understand the Total Cost of the Loan
Do not select a loan based only on an advertised interest rate or EMI.
Before accepting an offer, review:
-
Interest rate and whether it is fixed or floating
-
Annual Percentage Rate (APR)
-
Processing and other disclosed fees
-
Applicable taxes
-
Repayment tenure and EMI amount
-
Late-payment and penal charges
-
Foreclosure or prepayment conditions
-
Total amount payable over the loan term
For covered digital lending arrangements, RBI requirements include disclosures designed to help borrowers understand the loan's cost and terms. Read the Key Facts Statement (KFS), where applicable, and compare the offer with alternatives before signing.
6. Never Pay Suspicious Upfront Fees
Be cautious if an unknown agent or app asks you to transfer money to a personal bank account or digital wallet to guarantee loan approval.
Warning signs include:
-
Claims of guaranteed approval regardless of eligibility
-
Pressure to pay immediately to unlock a loan
-
Requests for an unexplained security deposit
-
No clear lender identity or written loan agreement
-
Communication only through unverified phone numbers
-
Requests for OTPs, UPI PINs, passwords or remote access to your device
Legitimate charges should be clearly disclosed and handled through the proper process. Verify any payment request directly with the lender using its official contact details.
7. Protect Your Personal and Financial Data
A loan application may require sensitive information, but you should understand why the information is needed and how it will be used.
Follow these precautions:
-
Download apps from trusted sources and verify the lender.
-
Read the privacy policy before sharing information.
-
Grant only necessary permissions.
-
Do not share OTPs, passwords, UPI PINs or card security codes.
-
Avoid uploading documents through suspicious links.
-
Do not install remote-access applications at the request of an unknown loan agent.
-
Keep copies of the loan agreement and official communications.
If an app demands unrelated access to your contacts, photos or other personal information, pause and review the request carefully.
8. Check the EMI Against Your Freelance Income
Freelancers should calculate repayment capacity using realistic income estimates rather than their best-earning month.
For example, a freelancer may earn ₹60,000 in one month and ₹35,000 in another. If the EMI is affordable only during the higher-income month, the loan could become difficult to manage.
Before applying, account for:
-
Essential household expenses
-
Business and software costs
-
Taxes
-
Existing loan repayments
-
Delayed client payments
-
Emergency savings
Choose a loan amount and tenure that leave sufficient room for necessary expenses. If repayments would depend on receiving every client payment on time, consider borrowing less or postponing the application.
9. Read the Loan Agreement Before Accepting
Never accept a loan without understanding its terms.
Confirm the lender's name, sanctioned amount, interest rate, APR, repayment schedule, fees and complaint-handling process. Keep the digitally signed agreement and related documents sent to your registered email or other official channel.
For digital loans, check whether a cooling-off or look-up period applies and understand the conditions for using it. Do not assume every loan has identical cancellation or exit terms.
10. Know Where to Report Suspected Fraud
If you suspect a fake loan app, unauthorised transaction or financial cybercrime:
-
Contact your bank or payment provider promptly if money has been transferred.
-
Report cybercrime through the official National Cyber Crime Reporting Portal.
-
In India, call 1930 promptly for assistance with financial cybercrime reporting.
-
Keep screenshots, transaction IDs, messages and other evidence.
-
Contact the lender's official grievance officer for loan-related complaints.
Use official reporting channels rather than paying someone who claims they can recover your money for an advance fee.
Quick Safety Checklist for Freelancers
Use this checklist before submitting your application.
| Safety check | What to confirm |
|---|---|
| Lender verification | The actual lender is identified and verifiable |
| Eligibility | The criteria match your situation |
| Income proof | Documents are genuine and up to date |
| Credit report | Important details are accurate |
| Loan cost | APR, fees and repayment terms are clear |
| App permissions | Data requests are relevant and understood |
| Payment requests | No suspicious payment is required to guarantee approval |
| EMI affordability | Repayments fit conservative income estimates |
| Loan agreement | You have read and saved the terms |
| Complaint process | Official support and grievance details are available |
Common Loan Safety Mistakes to Avoid
Freelancers can reduce borrowing risks by avoiding these common mistakes:
Applying without checking eligibility: This can waste time and may result in unnecessary credit enquiries.
Choosing the lowest advertised EMI: A longer tenure may reduce the monthly instalment while increasing the overall interest paid.
Ignoring the APR and fees: The interest rate alone may not show the full borrowing cost.
Trusting guaranteed approval claims: No genuine lender can promise approval without an assessment of its requirements.
Sharing OTPs or UPI PINs: These credentials should never be disclosed to an agent claiming to process a loan.
Borrowing more than necessary: A larger loan can create repayment pressure, especially when freelance income fluctuates.
Ignoring the loan agreement: Unread terms can lead to surprises about charges, repayment dates or cancellation conditions.
Frequently Asked Questions (FAQs)
1. Can freelancers in Delhi NCR safely apply for personal loans?
Yes, freelancers can explore loan products from legitimate lenders that accept self-employed applicants. They should verify the lender, review the costs and check repayment affordability before applying.
2. How can I check whether a loan app is genuine?
Identify the actual bank or NBFC behind the loan and verify its association with the app through official lender information and the RBI's Digital Lending Apps directory, where applicable. The directory helps verify reported associations but is not a guarantee of every aspect of an app's conduct.
3. Which documents should freelancers prepare for a loan?
Depending on the lender, documents may include PAN, address proof, bank statements, ITRs, invoices, client contracts and other income records. Requirements vary by product.
4. Is a high CIBIL score enough to guarantee loan approval?
No. A credit score is only one factor. Lenders may also assess income, existing debts, employment or freelance history, documents and repayment capacity.
5. Should I pay an agent to guarantee loan approval?
No. Be highly cautious of anyone demanding a suspicious advance payment in exchange for guaranteed approval. Verify all legitimate fees directly with the lender and use official payment channels.
6. What should I check before accepting a digital loan?
Review the lender's identity, APR, KFS where applicable, EMI, tenure, charges, privacy policy, loan agreement and grievance redressal details. Make sure you understand the repayment obligations.
7. What should I do if I suspect a fraudulent loan app?
Contact your bank promptly if a transaction has occurred, preserve the evidence and report the incident through official cybercrime channels. In India, call 1930 promptly for financial cybercrime reporting assistance.
8. Can irregular freelance income affect loan eligibility?
Yes. Fluctuating earnings may affect how a lender evaluates repayment capacity. Maintain clear income records and calculate affordability using conservative estimates.
9. How can freelancers protect their documents during the application process?
Submit documents only through verified channels, read the privacy policy, avoid suspicious links and never share OTPs, passwords or UPI PINs. Keep a record of the documents submitted.
10. Where can I learn more about digital lending safety?
Start with the official Reserve Bank of India website and its digital lending directions. These explain borrower disclosures, data-related safeguards and grievance-handling requirements for covered digital lending arrangements.
Conclusion
Understanding loan eligibility is important, but protecting your money, documents and personal information is equally essential. Freelancers in Delhi NCR should verify lenders, prepare genuine income records, compare loan costs and ensure that EMIs remain affordable even during low-income months.
A careful safety check can help you avoid suspicious offers and make a more informed borrowing decision. Before applying, take time to read the agreement, verify the digital platform and understand your repayment obligations.
Published on : 21st October 2026
Published by : Shibam nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed