

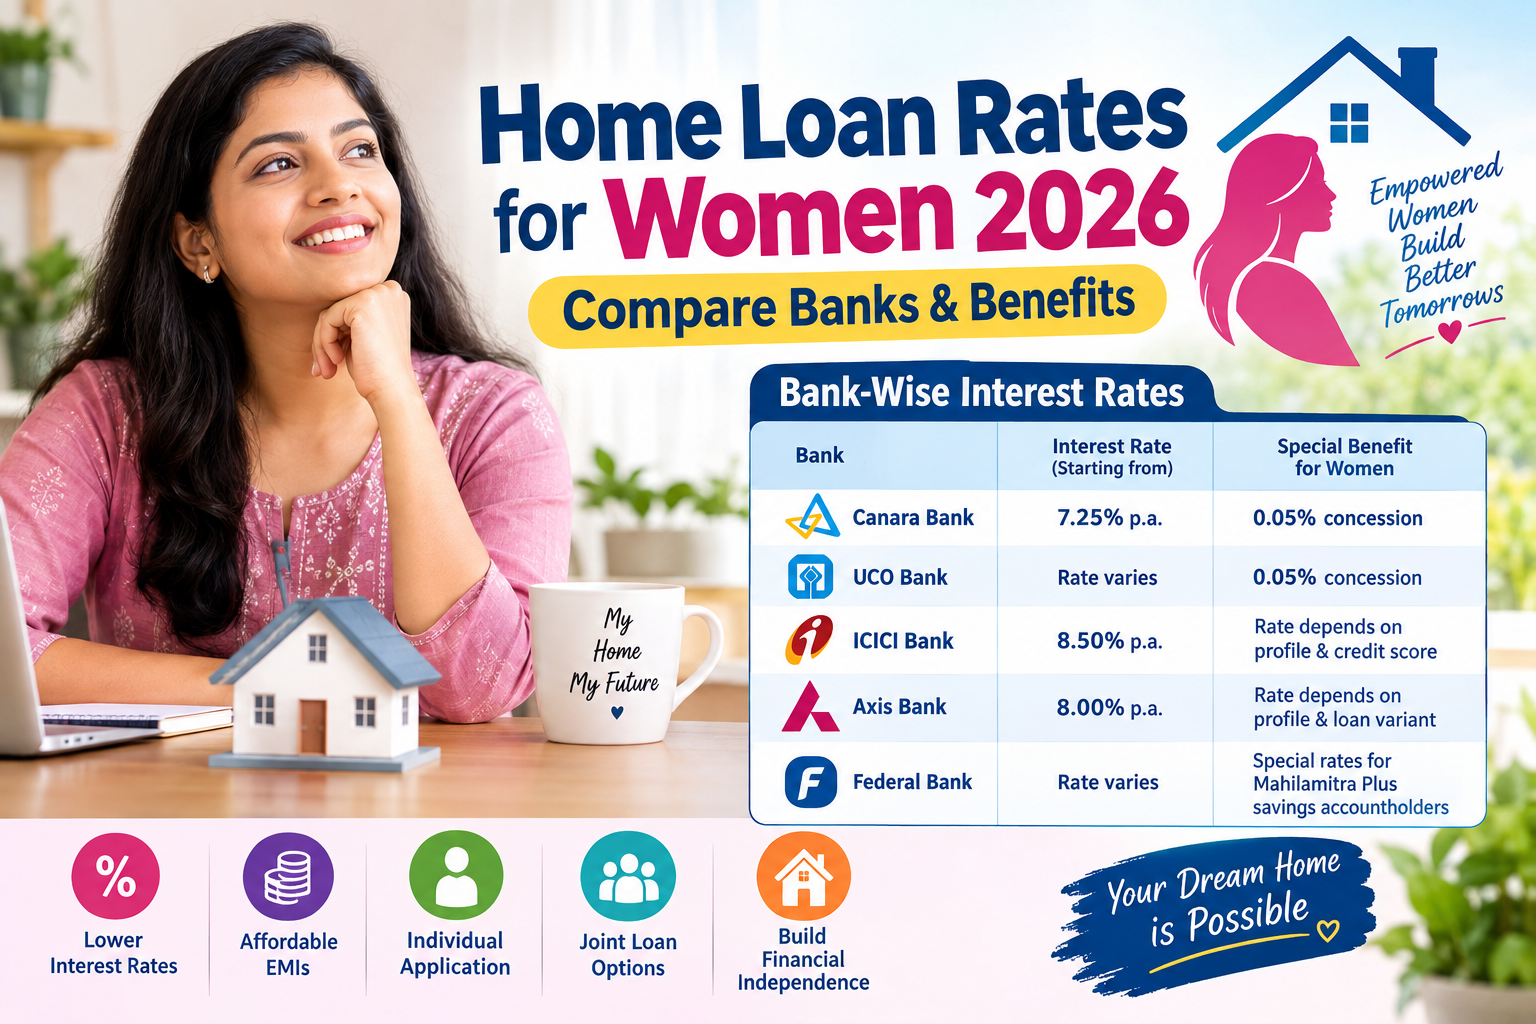
Home Loan Interest Rates for Women in India 2026: Compare Banks, Benefits and Eligibility
Buying a home is a major financial milestone, and choosing the right home loan can make a significant difference to your long-term budget. For women borrowers in India, certain banks offer special home loan interest concessions that may help reduce monthly EMIs and overall borrowing costs.
In 2026, women can apply for home loans from public sector banks, private banks and housing finance companies. Some lenders provide a lower interest rate for women borrowers, while others determine the rate mainly through credit score, income, loan amount and repayment capacity.
This guide covers home loan interest rates for women in India, bank-wise comparisons, eligibility requirements, documents and tips to reduce borrowing costs.
Key Takeaways
- Some Indian banks offer special interest rate concessions to women home loan borrowers.
- The concession may be around 0.05% or vary according to the lender's scheme and eligibility conditions.
- A strong CIBIL score and stable income can help applicants qualify for better interest rates.
- Women can apply individually or jointly, subject to the lender's eligibility criteria.
- Compare the interest rate, processing fees, loan tenure and total repayment amount before applying.
- Interest rates are subject to change and the final rate depends on the bank's assessment.
Home Loan Interest Rates for Women in India: September 2026
Home loan interest rates vary between banks and borrower categories. The following rates are indicative published rates, not guaranteed offers for every woman applicant.
| Bank | Published home loan rate / pricing | Special benefit for women |
|---|---|---|
| Canara Bank | 7.25% p.a. for eligible prime borrowers under the specified scheme | Published 0.05 percentage-point concession for women |
| UCO Bank | Rate depends on the applicable loan scheme | Additional 0.05 percentage-point concession |
| ICICI Bank | 8.50% p.a. onwards for listed standard home loan categories | Final rate depends on credit score and borrower profile |
| Axis Bank | 8.00% p.a. onwards for eligible floating-rate categories | Rate depends on CIBIL score, loan variant and risk factors |
| Federal Bank | Rate depends on the applicable home loan scheme | Special rates for eligible Mahilamitra Plus savings accountholders |
Important: These are not directly equivalent offers. The banks use different eligibility criteria, loan categories and pricing structures. Confirm the applicable women's concession and final sanctioned rate with the lender before applying.
What Is a Home Loan Interest Concession for Women?
A home loan interest concession is a reduction in the applicable interest rate offered by a lender to eligible borrowers.
For example, if a bank offers a 0.05 percentage-point concession, a standard rate of 8.00% could become 7.95% for an eligible woman borrower, assuming all other pricing conditions remain unchanged.
Even a small reduction may generate savings over a long repayment period. However, the actual benefit depends on the loan amount, tenure, outstanding principal and future interest rate changes.
Not every bank offers a separate women's concession, and the concession may be subject to specific conditions.
Benefits of Taking a Home Loan as a Woman
1. Lower Interest Rate
Some lenders provide women borrowers with a small interest rate concession. This can reduce the EMI or total interest payable over the loan tenure.
2. Affordable Monthly EMIs
A lower interest rate can make monthly repayments slightly more affordable, helping borrowers manage their household budgets.
3. Individual Home Loan Application
A woman can apply for a home loan independently if she meets the bank's income, credit and repayment eligibility requirements. Marriage or a male co-applicant is not a universal requirement.
4. Joint Home Loan Benefits
Women can apply jointly with a spouse or another eligible co-applicant. Depending on the lender's rules, combined income may improve loan eligibility.
5. Homeownership and Financial Independence
Owning a home can provide long-term housing security and an opportunity to build personal assets.
Eligibility Criteria for Women Home Loan Applicants
Although eligibility requirements vary between lenders, applicants generally need to meet the following conditions:
| Eligibility Factor | General Requirement |
|---|---|
| Age | Usually 18 years or older, subject to the bank's rules |
| Income | Regular and verifiable income |
| Employment | Salaried or self-employed |
| Credit Score | A good credit history is beneficial |
| Repayment Capacity | Sufficient income after existing obligations |
| Property | Property must meet the lender's legal and technical requirements |
| Nationality | Indian residents and eligible NRI applicants, subject to scheme rules |
Meeting the minimum eligibility criteria does not guarantee loan approval or a specific interest rate.
Documents Required for a Women's Home Loan
Women applying for a home loan may need the following documents:
Identity and Address Proof
- Aadhaar card
- PAN card
- Passport or other accepted identity proof
- Address proof
Income Documents for Salaried Applicants
- Latest salary slips
- Bank statements
- Form 16 or income tax returns, as applicable
- Employment details
Documents for Self-Employed Applicants
- Income tax returns
- Business financial statements
- Bank statements
- Business registration documents, where applicable
Property Documents
- Sale agreement or title documents
- Approved building plan, where required
- Property tax receipts, where applicable
- Other documents requested by the lender
The exact documentation list depends on the bank, employment type and property.
How to Apply for a Home Loan as a Woman
Follow these steps to apply for a home loan in India:
- Compare interest rates offered by different banks.
- Check your credit score and repayment capacity.
- Calculate the loan amount and EMI you can comfortably afford.
- Select a suitable lender and home loan scheme.
- Complete the online or branch application.
- Submit identity, income and property documents.
- Complete the lender's credit and property verification.
- Review the sanction letter, interest rate, fees and repayment terms before accepting the loan.
Tips to Get a Lower Home Loan Interest Rate
- Maintain a healthy credit score and repay existing loans on time.
- Compare offers from multiple banks rather than focusing only on advertised starting rates.
- Ask whether a women-specific interest concession is available.
- Consider a joint application if the co-applicant's income improves repayment eligibility.
- Choose a suitable loan tenure based on your monthly budget.
- Review processing fees and other charges before selecting a lender.
- Negotiate with the bank if you have a strong credit profile or a competing offer.
Home Loan EMI Example for Women Borrowers
The following example illustrates how interest rates can affect home loan repayments.
Assumptions:
- Loan amount: ₹30 lakh
- Loan tenure: 20 years
- Interest rates: 8.00% and 7.95%
- Interest rate remains unchanged throughout the tenure
| Particulars | At 8.00% | At 7.95% |
|---|---|---|
| Loan Amount | ₹30,00,000 | ₹30,00,000 |
| Tenure | 20 years | 20 years |
| Approximate Monthly EMI | ₹25,093 | ₹25,000 |
| Approximate Total Interest | ₹30.22 lakh | ₹30.00 lakh |
Under these assumptions, the 0.05 percentage-point reduction saves approximately ₹93 per month, or around ₹22,000 in total interest over 20 years.
This is an illustrative calculation, not a bank quotation. Actual EMIs may change if the interest rate is floating or the loan terms differ.
Fixed vs Floating Home Loan Interest Rates
| Feature | Fixed Interest Rate | Floating Interest Rate |
|---|---|---|
| Interest Rate | Remains fixed for the agreed period or tenure, depending on the product | Changes according to the applicable benchmark and lender's terms |
| EMI Predictability | Generally more predictable during the fixed period | EMI or tenure may change |
| Market Rate Changes | Less immediate impact during the fixed period | May benefit from rate reductions or be affected by increases |
| Suitable For | Borrowers who prefer predictable repayments | Borrowers comfortable with interest rate fluctuations |
Check whether a fixed-rate product is fixed for the full tenure or only for a specified period.
Frequently Asked Questions (FAQs)
1. Do women get lower home loan interest rates in India?
Some banks offer a special interest rate concession to eligible women borrowers. The benefit and conditions vary by lender.
2. Which bank offers a home loan concession for women?
Canara Bank and UCO Bank publish additional interest concessions for women borrowers. Applicants should verify the current terms with the bank.
3. What is the home loan interest rate for women in 2026?
There is no single rate applicable to all women borrowers. Rates depend on the lender, credit profile, loan amount and applicable scheme.
4. Can an unmarried woman apply for a home loan?
Yes. An unmarried woman can apply independently, subject to the bank's eligibility and repayment criteria.
5. Is a male co-applicant compulsory for a woman home loan applicant?
No. A male co-applicant is not universally compulsory. Individual applications are permitted subject to the lender's criteria.
6. What CIBIL score is required for a home loan?
Banks have different credit assessment standards. A higher credit score can improve the chances of approval and may help secure better pricing.
7. Can a housewife get a home loan?
A housewife without independent income may face difficulty qualifying for a home loan individually. A joint application with an eligible earning co-applicant may be an option, subject to the lender's rules.
8. Can a woman apply for a joint home loan with her husband?
Yes. Eligible spouses can apply jointly. The lender will assess income, credit history and repayment capacity.
9. Does a woman receive a lower EMI automatically?
No. A lower EMI depends on the sanctioned interest rate, loan amount, tenure and repayment structure.
10. Can a woman get a home loan without a CIBIL score?
Some lenders may consider applicants with limited credit history, but approval and pricing depend on their credit assessment policies.
11. What is the maximum home loan tenure available to women?
The maximum tenure depends on the bank, applicant's age, income and loan scheme. Some lenders offer tenures of up to 30 years.
12. Can a woman get tax benefits on a home loan?
Eligible borrowers may claim applicable home loan tax benefits under prevailing tax laws, subject to ownership, repayment and tax-regime conditions.
13. Is a home loan concession available for every woman borrower?
No. A concession may be restricted to specific loan schemes or borrower categories. Confirm the eligibility conditions with the bank.
14. Can a woman transfer her home loan to another bank?
Yes. Eligible borrowers may apply for a home loan balance transfer, subject to the new lender's approval and applicable charges.
15. How can women compare home loan offers?
Compare the effective interest rate, EMI, total repayment, processing charges, prepayment terms and eligibility conditions before choosing a lender.
Conclusion
Home loan interest concessions can help women borrowers reduce their borrowing costs, but the actual savings depend on the lender's scheme and the applicant's financial profile.
Before applying, compare bank-wise interest rates, check your eligibility and ask the lender to confirm any women-specific concession in writing. A carefully selected home loan can make long-term repayments more manageable and support your homeownership goals.
Published on : 22st September
Published by : MONISHA
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed