

Introduction
Choosing the right loan tenure is an important step when applying for a personal loan, home loan, education loan or vehicle loan. Loan tenure determines how long you will repay the loan and how much interest you may pay over time.
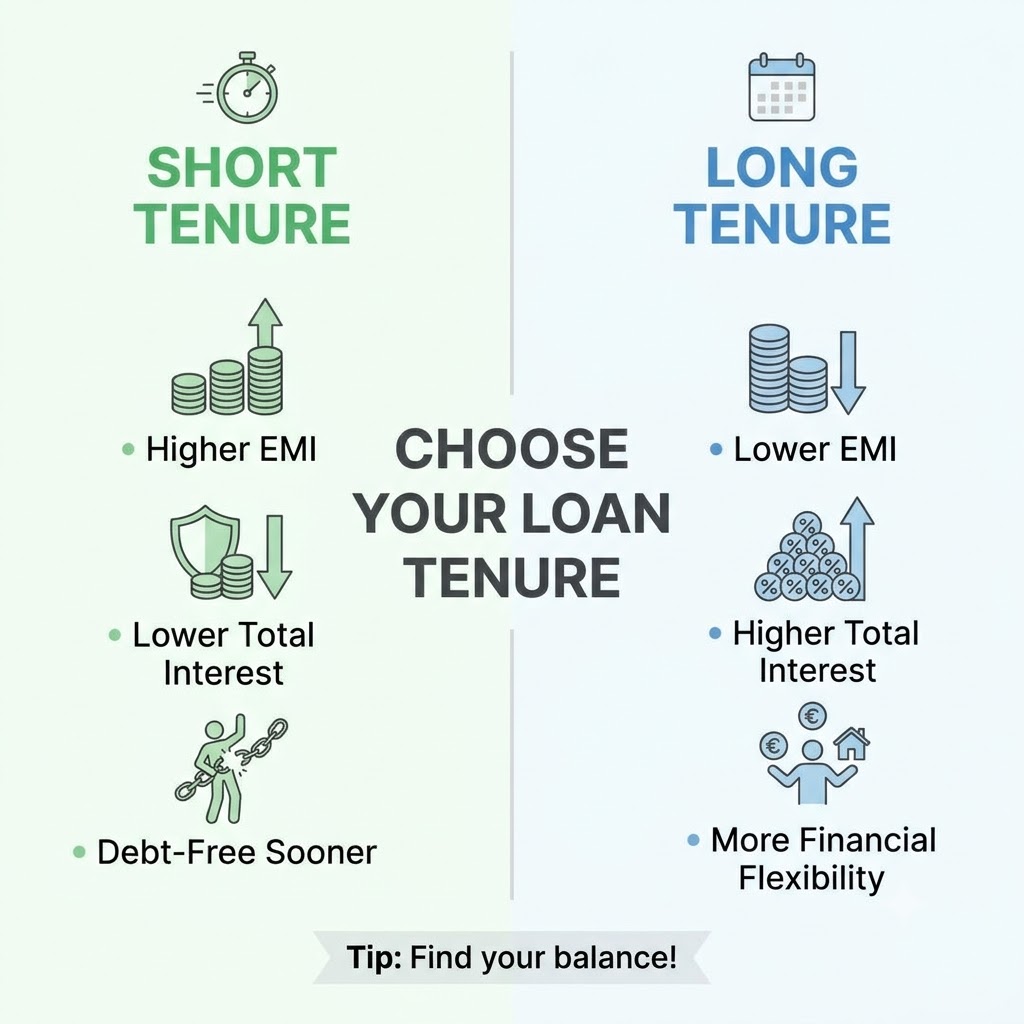
A shorter tenure usually means higher monthly Equated Monthly Instalments (EMIs) but lower total interest. A longer tenure generally offers smaller EMIs but can increase the overall borrowing cost. The right choice depends on your income, expenses, financial goals and repayment capacity.
In this guide, you will learn how to choose a loan tenure that balances affordable EMIs with lower interest costs.
What Is Loan Tenure?
Loan tenure is the total period given to a borrower to repay a loan. It can be expressed in months or years.
For example, if you borrow money for three years, you must repay the loan through scheduled instalments over 36 months, according to the loan agreement.
Loan tenure varies depending on the loan type, lender policies, loan amount and borrower eligibility.
Why Is Choosing the Right Loan Tenure Important?
Selecting a suitable loan tenure can help you:
-
Manage monthly expenses more effectively.
-
Keep EMI payments within your budget.
-
Reduce the total interest paid.
-
Avoid unnecessary financial pressure.
-
Plan future savings and investments.
-
Repay the loan within a suitable timeframe.
Short-Term vs Long-Term Loan Tenure
| Factor | Shorter Tenure | Longer Tenure |
|---|---|---|
| Monthly EMI | Higher | Lower |
| Total interest | Usually lower | Usually higher |
| Repayment period | Shorter | Longer |
| Monthly budget pressure | Higher | Lower |
| Debt-free sooner | Yes | No |
Neither option is automatically better. Your decision should depend on what you can comfortably afford and the total cost of borrowing.
7 Factors to Consider When Choosing a Loan Tenure
1. Evaluate Your Monthly Income
Start by calculating your monthly take-home income. Subtract essential expenses, household costs, existing EMIs and other financial commitments.
The remaining amount will help you understand how much you can comfortably allocate to a new EMI.
2. Calculate Your Affordable EMI
Do not select a loan tenure simply because the lender offers a low EMI. Make sure the payment fits your monthly budget while leaving enough money for emergencies and savings.
A longer tenure may be useful if a shorter one creates unnecessary financial pressure.
3. Compare Total Interest Costs
Always compare the total repayment amount, not just the monthly EMI. A longer tenure may reduce your monthly payment but increase the amount of interest paid throughout the loan.
Use an EMI calculator to compare different repayment periods before making a decision.
4. Consider Your Existing Loans
If you already have a home loan, credit card dues or other EMIs, consider your combined repayment obligations.
Taking another loan with a high EMI can put pressure on your finances. Choose a tenure that allows you to manage all repayments responsibly.
5. Check Your Income Stability
If your income is stable and you have sufficient savings, a shorter tenure may be suitable. If your income varies from month to month, a manageable EMI can provide greater financial flexibility.
Avoid choosing a tenure based on the assumption that your salary will increase in the future.
6. Review Prepayment and Foreclosure Terms
Check whether your lender permits early repayment and whether any applicable charges or conditions apply.
If you receive a bonus or additional income, making an eligible part-prepayment may help reduce your outstanding principal and interest costs, depending on the loan terms.
7. Match the Tenure to Your Financial Goals
Consider your future plans, including education expenses, home purchases, family responsibilities and retirement savings.
Your loan repayment should support your financial goals rather than prevent you from meeting essential needs.
Example: How Loan Tenure Affects EMI
Consider an illustrative personal loan of ₹5,00,000 at an annual interest rate of 12%.
| Tenure | Approx. Monthly EMI | Approx. Total Interest |
|---|---|---|
| 2 years | ₹23,537 | ₹64,900 |
| 3 years | ₹16,607 | ₹97,900 |
| 5 years | ₹11,122 | ₹1,67,300 |
These figures are estimates based on a reducing-balance interest calculation. Actual amounts may vary with lender terms and applicable charges.
The example shows that a longer tenure can make monthly repayments more affordable, but it can also substantially increase total interest costs.
Common Mistakes to Avoid
-
Choosing the longest tenure only to get a lower EMI.
-
Selecting a short tenure without checking affordability.
-
Ignoring processing fees and other loan charges.
-
Forgetting existing financial commitments.
-
Assuming that early repayment will always be free.
-
Borrowing more money than you actually need.
Tips for Choosing the Best Loan Tenure
-
Compare at least two or three available tenure options.
-
Calculate the EMI for each option.
-
Review the total interest and repayment amount.
-
Keep an emergency fund for unexpected expenses.
-
Read the loan agreement and Key Facts Statement where applicable.
-
Choose the shortest tenure that remains comfortably affordable.
-
Check prepayment conditions before accepting the offer.
Frequently Asked Questions (FAQs)
1. What is the best loan tenure?
The best loan tenure is one that keeps your EMI affordable while limiting the total interest you pay.
2. Is a shorter loan tenure better?
A shorter tenure generally reduces total interest but requires higher monthly EMIs.
3. Is a longer loan tenure a good option?
It can be helpful when you need smaller monthly payments, although the total borrowing cost may increase.
4. Does loan tenure affect EMI?
Yes. For the same loan amount and interest rate, extending the tenure generally reduces the monthly EMI.
5. Does a longer tenure increase total interest?
Generally, yes. Interest is paid over a longer period, increasing the total interest cost.
6. Can I change my loan tenure later?
Possibly. Some lenders may permit restructuring or tenure changes, subject to their policies and applicable conditions.
7. How do I calculate the right loan tenure?
Use an EMI calculator to compare different tenures, monthly payments and total interest costs.
8. Should I choose a lower EMI or lower total interest?
Choose the balance that suits your financial situation. A lower total interest cost is beneficial only if the higher EMI remains manageable.
9. Can I repay a loan before the tenure ends?
Early repayment may be possible, depending on your loan agreement and applicable rules. Check any relevant charges or restrictions.
10. Does loan tenure affect loan eligibility?
It can influence affordability assessments because the tenure affects the EMI. Final eligibility depends on the lender's criteria and your financial profile.
Key Takeaways
-
Loan tenure affects both monthly EMI and total interest.
-
Shorter tenures generally save interest but require higher EMIs.
-
Longer tenures provide monthly flexibility but can increase borrowing costs.
-
Your income, expenses, existing debt and future goals should guide your decision.
-
Compare the total repayment amount before selecting a loan offer.
Conclusion
Choosing the right loan tenure is about balancing affordability with the total cost of borrowing. Before accepting a loan, compare different repayment periods, calculate your EMIs and review the complete loan terms.
A carefully selected tenure can help you manage monthly expenses, reduce unnecessary interest costs and maintain better financial stability throughout the repayment period.
Published on : 21st October 2026
Published by : monisha
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed