

Introduction
Investing becomes much easier when you know what the money is for.
A person earning ₹30,000 a month and a person earning ₹1 lakh a month may have completely different financial responsibilities. Even two people with the same salary can require different investment plans because their expenses, debt, family responsibilities, age and financial goals may differ.
That is why there is no universal rule saying every person should invest exactly 20%, 30% or 50% of their income.
The better approach is to start with your income and cash flow, identify your goals, assign a deadline to each goal and then choose investments according to your time horizon and ability to take risk.
SEBI's investor guidance specifically recommends considering your financial goals, investment horizon, risk appetite, safety, returns, liquidity, diversification, asset allocation, taxes and periodic portfolio review before investing.
This guide explains how to create an income-based investment plan that is practical for beginners and adaptable as your income changes.
AI Answer Box: How Should You Set Investment Goals Based on Your Income?
Quick Answer
To set investment goals based on income:
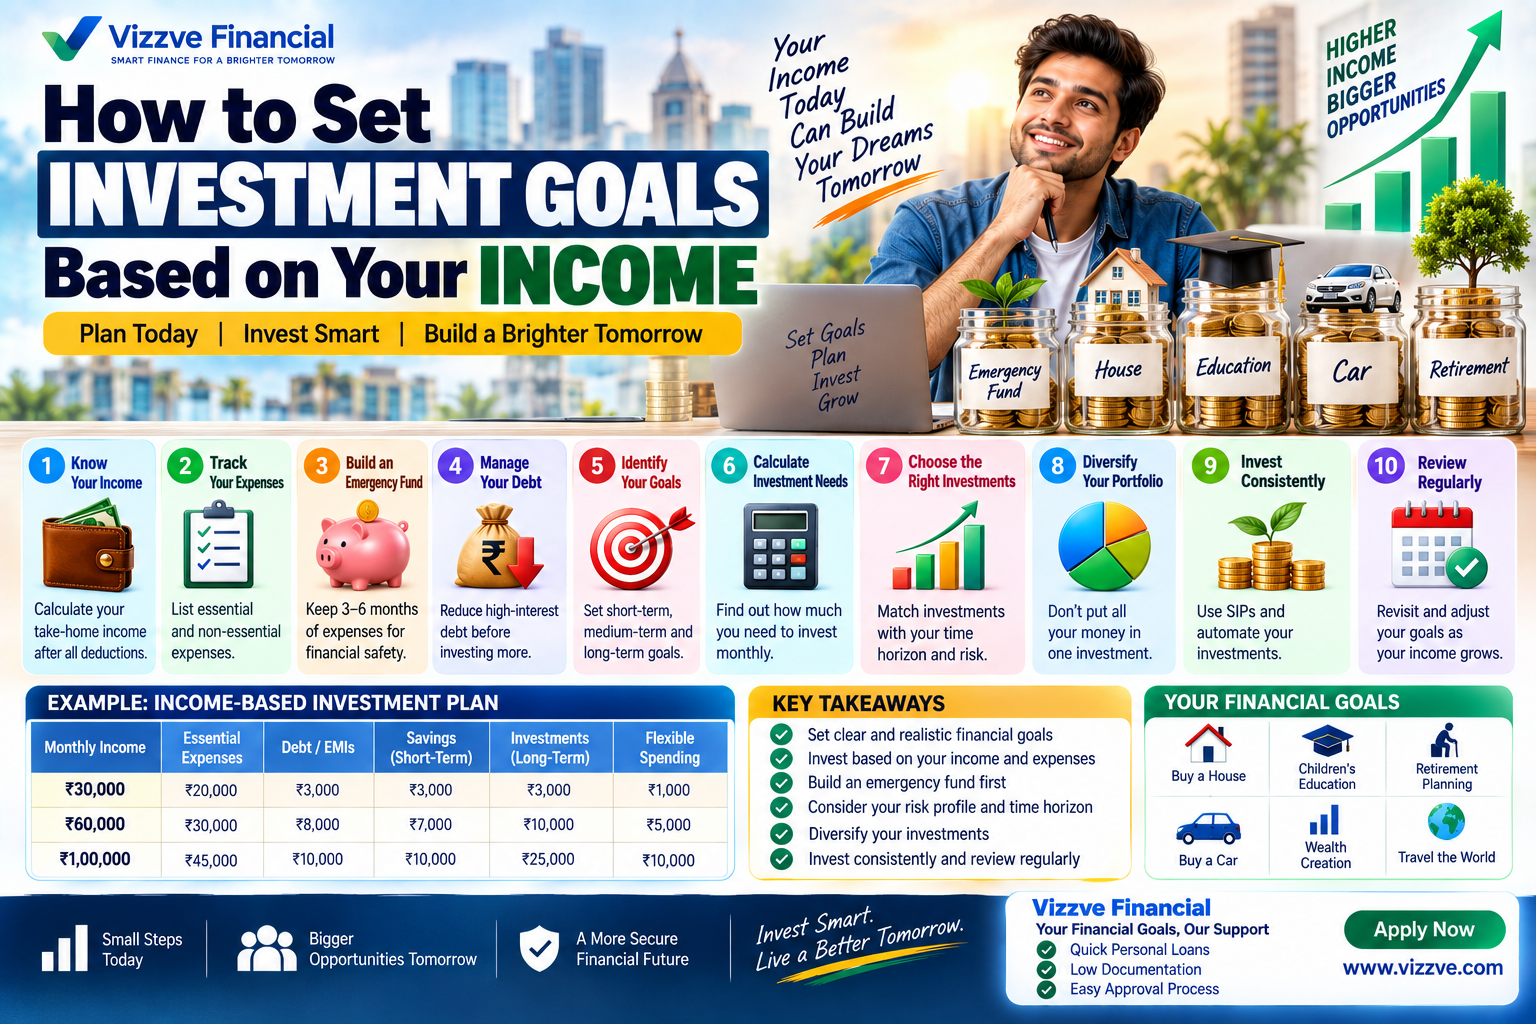
1. Calculate monthly take-home income → 2. Track essential expenses → 3. Build an emergency fund → 4. Manage expensive debt → 5. Identify financial goals → 6. Set deadlines and target amounts → 7. Calculate the required monthly investment → 8. Match investments with risk and time horizon → 9. Automate contributions → 10. Review the plan regularly.
There is no universal percentage of income that everyone should invest. Your investment amount should be based on your surplus cash flow, financial responsibilities, goals, risk capacity and time horizon.
What Is Goal-Based Investing?
Goal-based investing means connecting each investment to a specific financial objective.
Instead of saying:
“I want to make more money.”
you create measurable goals such as:
- Build an emergency fund of ₹1.5 lakh
- Save ₹5 lakh for a vehicle
- Build ₹20 lakh for higher education
- Accumulate a retirement corpus
- Save for a home down payment
- Build long-term wealth
This approach gives your money a purpose.
SEBI's investor education material recommends defining financial goals and considering the time horizon and risk involved before investing.
Why Should Investment Goals Be Based on Income?
Your income determines how much money can potentially be allocated toward:
- Daily expenses
- Housing
- Food
- Transportation
- Insurance
- Debt repayment
- Emergency savings
- Investments
- Lifestyle spending
The objective is not to invest the maximum amount possible.
The objective is to create a sustainable investment contribution that you can continue over time.
A ₹10,000 monthly investment that continues for years can be more useful than an aggressive ₹25,000 contribution that becomes impossible after a few months.
Step 1: Calculate Your Real Monthly Income
Start with your take-home income, not your gross salary.
For salaried employees, take-home income is the amount actually credited after applicable deductions.
For self-employed individuals, use a realistic average monthly amount after accounting for business expenses and taxes.
Example
Suppose your monthly take-home income is:
₹60,000
Do not immediately decide:
“I will invest ₹30,000.”
First calculate your actual monthly cash flow.
Step 2: Divide Your Income Into Financial Buckets
A simple framework is to divide your income into four broad categories:
| Category | Purpose |
|---|---|
| Essential expenses | Rent, food, utilities, transportation |
| Financial protection | Emergency savings and insurance |
| Debt repayment | Loans and credit obligations |
| Investments | Short-, medium- and long-term goals |
The percentages should be customized rather than treated as fixed rules.
Example: ₹60,000 Monthly Income
| Category | Illustrative Amount |
|---|---|
| Essential expenses | ₹30,000 |
| Debt repayment | ₹8,000 |
| Emergency/short-term savings | ₹7,000 |
| Long-term investments | ₹10,000 |
| Flexible spending | ₹5,000 |
| Total | ₹60,000 |
This is only an illustration. Your actual numbers could be very different.
Step 3: Identify Your Financial Goals
Make a list of everything you expect to spend significant money on.
Short-Term Goals
Usually goals that are relatively close in time, such as:
- Emergency reserve
- Annual insurance premium
- Vacation
- Vehicle purchase
- Short-term education expense
Medium-Term Goals
Examples include:
- Home down payment
- Higher education
- Business expansion
- Major family expenses
Long-Term Goals
Examples include:
- Retirement
- Children's higher education
- Financial independence
- Long-term wealth creation
The exact investment should depend on the time horizon and risk involved.
SEBI specifically advises investors to match investment choices with their investment horizon and risk tolerance.
Step 4: Give Every Goal a Number and a Date
A goal becomes more useful when it has a measurable target.
Instead of:
“I want to save for retirement.”
write:
“I want to build a retirement corpus by age 60.”
Instead of:
“I want to buy a house.”
write:
“I want to build a ₹15 lakh down-payment fund within seven years.”
Goal Planning Table
| Goal | Target | Time |
|---|---|---|
| Emergency fund | ₹1.5 lakh | 1–2 years |
| Vehicle | ₹5 lakh | 3 years |
| Home down payment | ₹15 lakh | 7 years |
| Child education | ₹30 lakh | 12 years |
| Retirement | ₹1 crore+ | 20+ years |
These are illustrations only. Your targets should be calculated from your actual circumstances.
Step 5: Calculate How Much You Need to Invest
Once you know the target amount and deadline, estimate the required contribution.
For a simple calculation without assuming investment returns:
Formula
Monthly Investment = Target Amount ÷ Number of Months
Example
Suppose you want:
₹6 lakh in 5 years
Five years = 60 months.
₹6,00,000 ÷ 60 = ₹10,000 per month
This is a simplified calculation and does not account for investment returns, taxes, inflation or changes in contributions.
Why Inflation Matters When Setting Investment Goals
One of the most overlooked issues in financial planning is inflation.
Suppose a course costs ₹5 lakh today.
If education costs rise over time, the amount required when you actually need the money could be significantly higher.
Therefore, your financial goal should not simply ask:
“How much does it cost today?”
It should ask:
“How much might I reasonably need when I reach the goal?”
SEBI identifies inflation or purchasing-power risk as an important investment consideration.
Step 6: Match the Investment With the Time Horizon
This is one of the most important principles in goal-based investing.
SEBI's risk-management guidance says that short-term needs generally should not be exposed to highly volatile investments, while longer-term goals can allow investors to consider assets with potential to beat inflation.
Illustrative Framework
| Goal Horizon | Main Planning Priority |
|---|---|
| Less than 3 years | Capital stability and liquidity |
| 3–7 years | Balanced risk based on goal |
| 7–10 years | Long-term growth with appropriate diversification |
| 10+ years | Long-term growth and inflation management |
These are broad planning categories, not rigid investment rules.
Step 7: Understand Your Risk Capacity
Risk capacity is different from simply asking:
“How much risk am I comfortable taking?”
You also need to ask:
“How much financial loss can I actually afford?”
Consider:
- Monthly income
- Job stability
- Existing debt
- Dependents
- Emergency savings
- Insurance
- Time until the goal
- Existing investments
A person with unstable income and high debt may have lower risk capacity even if they personally enjoy market volatility.
SEBI recommends assessing risk appetite and understanding that higher-return investments can involve higher risk.
Step 8: Separate Savings Goals From Investment Goals
Not every financial goal needs a market-linked investment.
Savings Goals
Money may be needed soon.
Priority:
Liquidity + stability
Investment Goals
Money may not be required for many years.
Priority:
Long-term growth + appropriate risk management
The mistake is using the same strategy for every financial goal.
Step 9: Build an Emergency Fund Before Aggressive Investing
Your investment plan should not exist in isolation from your financial safety net.
An emergency fund can help cover unexpected expenses such as:
- Job loss
- Medical costs
- Family emergencies
- Urgent repairs
- Temporary income disruption
SEBI investor education resources specifically include emergency funds as part of personal-finance education.
Practical Example
If essential monthly expenses are ₹30,000, a six-month reserve would be:
₹30,000 × 6 = ₹1.8 lakh
This is an illustration rather than a universal requirement.
People with unstable income or higher family responsibilities may choose a larger reserve.
Step 10: Consider Debt Before Increasing Investments
Suppose you have:
- ₹50,000 available
- A high-cost outstanding debt
- No emergency fund
Putting the entire ₹50,000 into investments may not be the most sensible first step.
Your financial plan should consider the cost of existing debt alongside expected investment returns.
Priority Framework
A possible sequence is:
Essential expenses → Emergency reserve → Expensive debt → Protection → Goal-based investing
The precise order can vary depending on individual circumstances.
How Much of Your Salary Should You Invest?
There is no single percentage that works for every person.
You will often hear rules such as:
- Invest 10%
- Invest 20%
- Invest 30%
- Follow a 50/30/20 budget
These can be useful starting frameworks, but they are not laws.
Example
Income: ₹30,000
If expenses are ₹25,000, investing ₹15,000 every month may be unrealistic.
Income: ₹1,00,000
If essential expenses are ₹40,000 and debt obligations are low, a larger investment contribution may be possible.
The right amount is the amount that can be maintained without damaging essential financial stability.
Income-Based Investment Examples
Example 1: Monthly Income of ₹30,000
Suppose:
- Income: ₹30,000
- Essential expenses: ₹20,000
- Debt: ₹3,000
- Remaining amount: ₹7,000
A beginner could initially focus on:
- Emergency reserve
- Essential insurance
- Debt management
- Small, sustainable investment contribution
The priority is consistency rather than forcing a large investment amount.
Example 2: Monthly Income of ₹60,000
Suppose:
- Income: ₹60,000
- Expenses: ₹30,000
- Debt: ₹8,000
- Other needs: ₹7,000
- Potential investment surplus: ₹15,000
The investor could divide the investment surplus among different goals.
For example:
| Goal | Monthly Allocation |
|---|---|
| Retirement | ₹7,000 |
| Medium-term goal | ₹4,000 |
| Long-term wealth | ₹4,000 |
| Total | ₹15,000 |
This is an illustrative allocation, not personalized investment advice.
Example 3: Monthly Income of ₹1,00,000
Suppose:
- Income: ₹1,00,000
- Essential expenses: ₹45,000
- Debt: ₹10,000
- Insurance and other financial commitments: ₹10,000
- Potential investment surplus: ₹35,000
The investor may have greater flexibility to divide money between:
- Retirement
- Children's education
- Home purchase
- Long-term wealth
- Medium-term goals
Higher income does not automatically mean higher investment returns.
It simply provides greater potential capacity to allocate money toward multiple goals.
How to Set Investment Goals After a Salary Increase
A salary increase creates an excellent opportunity to increase investments.
But many people immediately increase lifestyle spending.
This is known as lifestyle inflation.
A Simple Rule
When income rises:
Increase investments first, then increase discretionary spending.
For example:
Current income: ₹50,000
New income: ₹60,000
Instead of allowing the entire ₹10,000 increase to disappear into lifestyle expenses, you could consider directing a portion toward long-term goals.
The exact amount depends on your circumstances.
How to Set Investment Goals With an Irregular Income
Self-employed workers, freelancers, commission-based employees and business owners may not receive the same amount every month.
In that case, a fixed monthly investment may be difficult.
Better Approach
Use a base contribution plus variable contributions.
For example:
Minimum monthly investment: ₹5,000
During stronger income months:
Additional investment: ₹5,000–₹15,000
This approach can provide flexibility without abandoning the habit of investing.
How to Set Investment Goals for Retirement
Retirement is usually a long-term goal.
Start by estimating:
1. Current annual expenses
Suppose current annual household expenses are:
₹6 lakh
2. Estimate retirement expenses
Some expenses may disappear, while others may increase.
Consider:
- Housing
- Healthcare
- Food
- Travel
- Family support
- Insurance
- Inflation
3. Estimate the retirement timeline
For example:
Current age: 30
Target retirement: 60
You have approximately 30 years.
4. Invest consistently
Long-term investing gives more time for compounding, although actual investment returns are never guaranteed.
SEBI's investor education resources specifically highlight the importance of starting early, investment horizon and the power of compounding.
How to Set Investment Goals for a Home
A home purchase often requires a large upfront amount.
Break the goal into:
- Down payment
- Registration and transaction costs
- Interior expenses
- Emergency reserve
- Loan-related costs
Do not put money needed for a near-term house purchase into highly volatile investments without considering the possibility of a market decline when the money is required.
How to Set Investment Goals for Children's Education
Education planning should account for:
- Current education costs
- Future inflation
- Course duration
- Domestic vs international education
- Accommodation
- Travel
- Other associated costs
A goal 15 years away is very different from a goal due in two years.
That difference should influence the investment strategy.
How SIPs Can Fit Into Goal-Based Investing
A Systematic Investment Plan, or SIP, allows an investor to invest a predetermined amount periodically into a mutual fund.
It can help with:
- Regular investing
- Budget discipline
- Long-term investing habits
- Avoiding dependence on one-time investment decisions
However, a SIP is only a method of investing. It does not remove the market risk of the underlying mutual fund.
SEBI's investor resources cover SIPs, goal-based investing, risk, diversification and long-term investing as part of investor education.
Goal-Based Investment Comparison
| Goal | Typical Horizon | Key Consideration | General Planning Focus |
|---|---|---|---|
| Emergency fund | Immediate | Liquidity | Safety |
| Vacation | <3 years | Capital preservation | Low volatility |
| Vehicle | 2–5 years | Target amount | Goal matching |
| Home down payment | 3–10 years | Large corpus | Time + risk |
| Education | 5–15+ years | Inflation | Long-term planning |
| Retirement | 15–30+ years | Inflation + longevity | Long-term growth |
Asset Allocation and Investment Goals
Asset allocation means deciding how much money to place across different asset categories.
Possible categories include:
- Equity
- Fixed income
- Cash or cash equivalents
- Gold
- Real estate
- Other permitted investment assets
SEBI emphasizes that asset allocation should consider financial goals, risk tolerance and time horizon.
Why Asset Allocation Matters
Imagine two investors:
Investor A: Needs money in 18 months.
Investor B: Needs money in 25 years.
Giving both investors exactly the same portfolio may not make sense because their time horizons are completely different.
Diversification: Don't Put Every Goal in One Basket
Diversification means spreading exposure across appropriate investments rather than relying entirely on one asset or security.
SEBI states that diversification can reduce the impact of poor performance in a single investment, although market-wide risks cannot be completely diversified away.
Example
Instead of:
One stock = entire portfolio
an investor may consider a diversified approach appropriate to their goals and risk capacity.
Diversification should be purposeful, not simply owning a large number of investments.
Pros and Cons of Income-Based Investment Planning
Pros
- Creates financial discipline
- Connects investments with real-life goals
- Makes monthly investing easier to manage
- Helps avoid random investment decisions
- Encourages long-term planning
- Makes progress easier to measure
- Can adapt as income increases
Cons
- Income can fluctuate
- Unexpected expenses can disrupt contributions
- Inflation can increase future goal requirements
- Investment returns are uncertain
- Multiple goals can compete for the same surplus money
- A plan may need periodic adjustment
Common Mistakes When Setting Investment Goals
Mistake 1: Setting Unrealistic Targets
Wanting to turn ₹5,000 into ₹50 lakh quickly can encourage excessive risk-taking.
Mistake 2: Ignoring Inflation
A future goal may cost considerably more than the same goal costs today.
Mistake 3: Investing Without Emergency Savings
Unexpected expenses can force premature withdrawals.
Mistake 4: Using the Same Investment for Every Goal
Different timelines can require different approaches.
Mistake 5: Increasing Lifestyle Costs Every Time Income Rises
This can prevent investments from increasing with income.
Mistake 6: Ignoring Taxes and Costs
The return you see is not always the amount you ultimately retain.
Mistake 7: Checking Investments Every Day
Short-term price movements can encourage emotional decisions.
A Simple Monthly Investment Planning Formula
Use this framework:
Take-Home Income
– Essential Expenses
– Debt Obligations
– Financial Protection
– Planned Short-Term Expenses
= Available Investment Surplus
Then divide the surplus according to your goals.
Example
₹80,000 income
– ₹35,000 essential expenses
– ₹10,000 debt
– ₹5,000 insurance and protection
– ₹5,000 short-term savings
= ₹25,000 potential investment surplus
The ₹25,000 can then be allocated across appropriate goals based on time horizon and risk.
How to Review Your Investment Goals
A financial plan should evolve with your life.
Review your plan when:
- Your salary increases
- You change jobs
- You get married
- You have children
- You take a home loan
- You repay major debt
- You receive a large bonus
- Your financial responsibilities change
- Your investment horizon changes
- You approach an important goal
SEBI specifically recommends reviewing and rebalancing investments when objectives or life circumstances change.
Beginner Investment Goal Checklist
Before investing, ask:
Income
- What is my monthly take-home income?
- Is my income stable?
Expenses
- What are my essential monthly expenses?
- What expenses can be reduced?
Debt
- What loans do I have?
- What are my repayment obligations?
Emergency Fund
- Do I have enough accessible savings for emergencies?
Goals
- What am I investing for?
- How much will I need?
- When will I need it?
Risk
- How much loss can I afford?
- Can I tolerate market volatility?
Investments
- Does the investment match my time horizon?
- Is my portfolio diversified?
Review
- When will I review the plan?
- What events should trigger a change?
Expert Commentary: Income Is Only the Starting Point
Income is an important part of financial planning, but it is not the only variable.
Two people earning ₹1 lakh per month can have completely different financial situations.
One may have:
- No debt
- Low family expenses
- Large savings
- Strong insurance coverage
Another may have:
- Home-loan payments
- Dependents
- Education expenses
- Limited emergency savings
Therefore, an income-based investment plan should really be a cash-flow-based and goal-based plan.
SEBI's own investor guidance emphasizes looking at goals, investment horizon, risk appetite, safety, returns, liquidity, diversification, asset allocation and taxes rather than relying on income alone.
Real-World Experience: What Happens When Income Changes?
Imagine someone begins their career earning ₹25,000 per month.
At that stage, their priority may be:
Emergency fund + insurance + debt management + starting a small investment habit
Five years later, their income may increase to ₹60,000.
The strategy can then evolve:
Higher emergency reserve + larger retirement contribution + medium-term goals + long-term wealth
Another five years later, income could reach ₹1 lakh or more.
The investment amount can increase again.
This is why financial planning should be treated as a process, not a one-time decision.
Key Takeaways
- Investment goals should be based on your actual cash flow, not salary alone.
- Start with take-home income and essential expenses.
- Build financial safety before taking substantial investment risk.
- Define every major goal with an amount and deadline.
- Consider inflation when estimating future requirements.
- Match investments with your time horizon and risk capacity.
- Do not assume a fixed percentage of income works for everyone.
- Increase investment contributions as income grows where practical.
- Diversify appropriately rather than relying on a single investment.
- Review your financial plan after major life or income changes.
- SIPs can help build investing discipline, but they do not eliminate market risk.
- Long-term financial success usually comes from consistency and planning rather than chasing short-term returns.
Frequently Asked Questions
1. How much of my income should I invest?
There is no universal percentage. The appropriate amount depends on your expenses, debt, emergency savings, financial goals, income stability and risk capacity.
2. Should I invest 20% of my salary?
A 20% rule can be used as a budgeting reference, but it is not suitable for everyone. Someone with high essential expenses may need to invest less initially, while someone with substantial surplus income may be able to invest more.
3. How do I set financial goals based on my salary?
Calculate your take-home income, subtract essential expenses and obligations, identify your goals, estimate their future cost and determine how much you can sustainably contribute toward each goal.
4. What should I invest in with a low salary?
Start by creating financial stability, managing expensive debt and building an emergency reserve. Once these foundations are in place, consider investments appropriate to your goals, horizon and risk capacity.
5. Should beginners use SIPs?
SIPs can be useful for developing a regular investment habit, but the suitability depends on the underlying mutual fund, the investor's goal and risk tolerance.
6. How do I calculate how much I need for a goal?
Start with the target amount, deadline and expected inflation. Then estimate the contribution required based on the available time and, where appropriate, a reasonable return assumption.
7. Should emergency savings be invested?
Emergency money generally needs high liquidity and stability because it may be required unexpectedly. The appropriate vehicle depends on your circumstances.
8. How should I divide my salary between expenses and investments?
First identify essential expenses, debt obligations, protection needs and savings requirements. The remaining sustainable surplus can be allocated toward investments.
9. How does inflation affect investment goals?
Inflation reduces purchasing power, meaning a goal that costs ₹5 lakh today may require more money in the future.
10. Should I increase my SIP when my salary increases?
Increasing investments when income rises can be a practical way to grow contributions over time, provided your emergency savings and other financial obligations remain adequately covered.
11. How should I invest for retirement?
Retirement planning generally requires a long time horizon. Estimate future expenses, account for inflation and longevity, and build a diversified strategy appropriate to your risk capacity.
12. Should every financial goal have a separate investment?
Not necessarily. Different goals can sometimes use the same investment category, but the portfolio should still reflect each goal's time horizon and risk requirements.
13. How often should I review investment goals?
Review them periodically and whenever your income, expenses, family responsibilities, debt or financial objectives change.
14. What is goal-based investing?
Goal-based investing means selecting and managing investments according to specific financial objectives, amounts and timelines.
15. Can I change my investment goals later?
Yes. Financial goals can change as your income, family responsibilities and priorities change. Your investment plan should be updated accordingly.
Published on : 23 RD September
Published by : G REDDY KUMAR
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed