

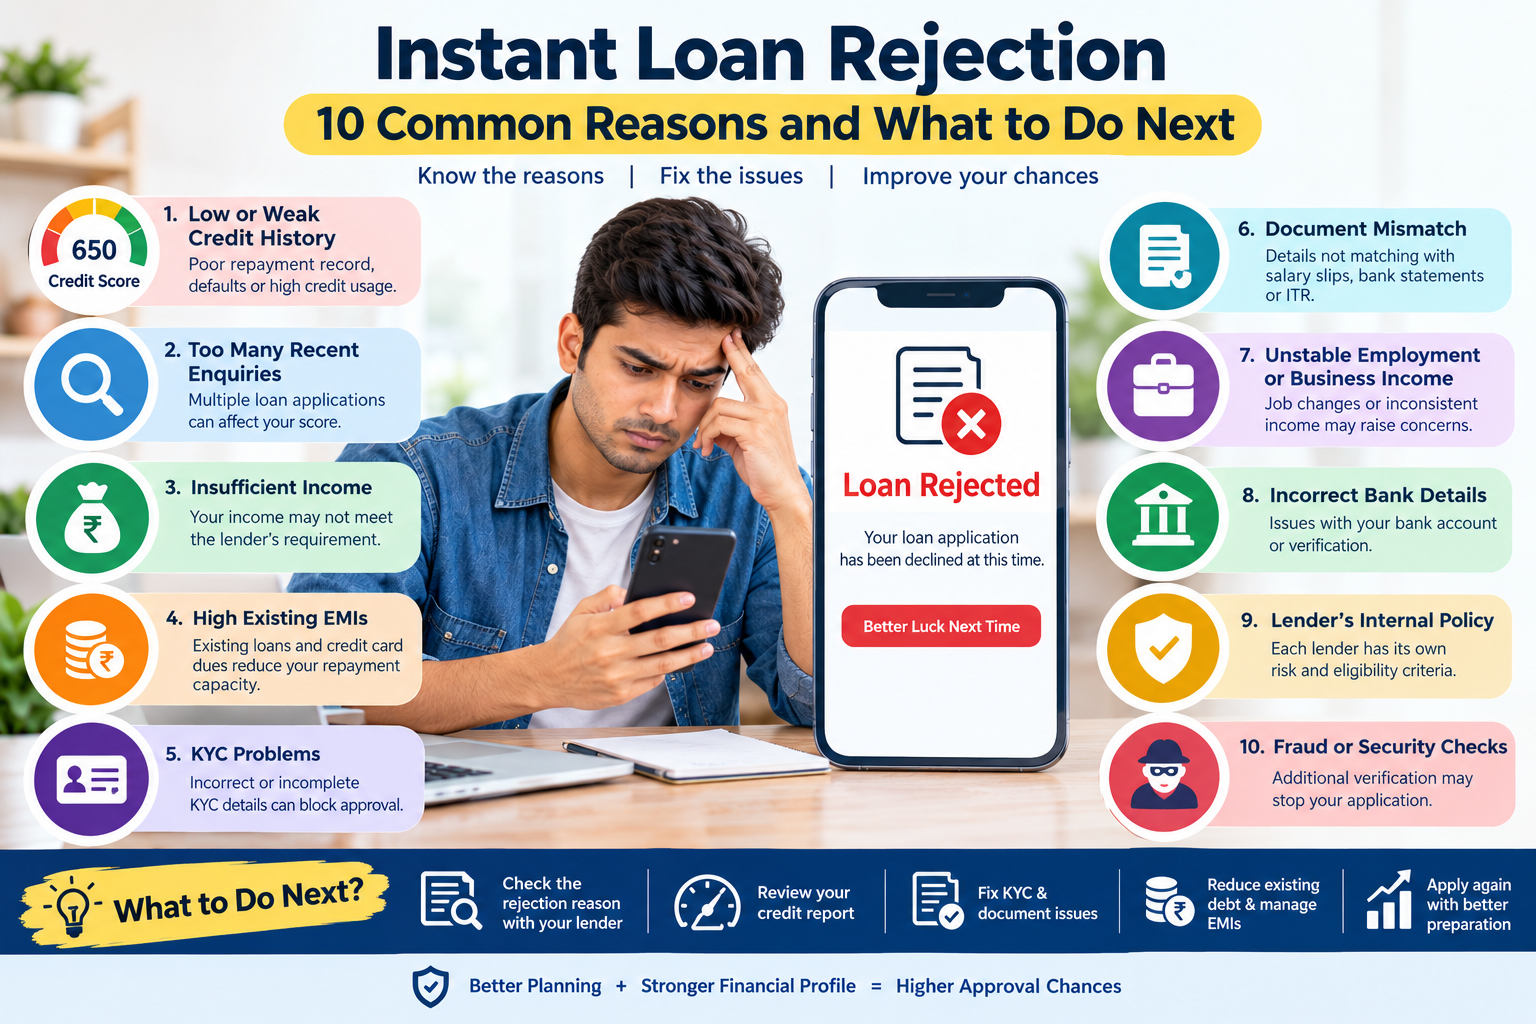
An instant loan rejection can be frustrating, especially when an online loan application is processed within minutes. However, lenders assess factors such as credit history, income, existing debt, KYC information and repayment capacity before making a final lending decision.
RBI guidance says lenders should properly assess credit applications and communicate the main reason or reasons for rejection to borrowers within the applicable timeframe.
10 Common Reasons for Instant Loan Rejection
1. Low or Weak Credit History
A lender may reject an application because of poor repayment history, defaults, high credit utilisation or other negative information in the credit report.
2. Too Many Recent Credit Enquiries
Multiple loan or credit applications within a short period can result in several credit enquiries and may affect how a lender assesses the application.
3. Insufficient Income
If your income does not meet the lender's criteria for the requested loan amount, the application may be rejected.
4. High Existing EMIs
Existing personal loans, credit-card dues and other EMIs can reduce your available repayment capacity.
5. KYC Problems
Incorrect, incomplete or mismatched PAN, Aadhaar or other KYC information can prevent successful verification.
6. Income or Document Mismatch
If information in your application does not match your salary slips, bank statements, ITR or other documents, the lender may request clarification or reject the application.
7. Unstable Employment or Business Income
Lenders may consider employment history or business stability when assessing repayment capacity.
8. Incorrect Bank Details
Problems with bank-account information or verification can stop the loan from progressing.
9. Internal Lender Policy
Every bank and NBFC has its own credit-risk policies. Meeting basic eligibility criteria does not guarantee approval.
10. Fraud or Security Checks
Digital lenders may perform additional identity and fraud checks. An application can be stopped if information cannot be verified.
Instant Loan Rejection vs Instant Approval
| Initial Loan Decision | Final Lending Decision |
|---|---|
| May be automated | Usually follows detailed checks |
| Based on information provided | May include additional verification |
| Can change after assessment | Depends on lender's final credit decision |
| Does not guarantee disbursal | Followed by loan agreement/disbursal if approved |
What Should You Do After Loan Rejection?
Check the Rejection Reason
First, contact the lender and ask for the reason. RBI guidance says the main reasons for loan rejection should be communicated to applicants within the applicable timeframe.
Review Your Credit Report
Check for:
- Incorrect personal information
- Unknown loans or accounts
- Missed-payment records
- Excessive credit utilisation
- Recent credit enquiries
If you find an error, raise a dispute with the relevant credit bureau or lender.
Check Your EMI Burden
Calculate your existing monthly obligations before applying again. Taking another loan while already carrying significant debt may make approval more difficult and increase financial pressure.
Correct Documentation
Make sure your KYC, income details, bank information and employment or business information are accurate and consistent.
Avoid Repeated Applications
Instead of applying to many lenders immediately, understand the rejection reason first and address the underlying issue.
How to Improve Your Loan Eligibility
- Pay existing EMIs and credit-card bills on time.
- Keep credit utilisation under control.
- Avoid unnecessary loan applications.
- Maintain accurate KYC information.
- Keep income documents updated.
- Reduce outstanding debt where practical.
- Apply for an amount that matches your repayment capacity.
Is Loan Rejection Bad for Your Credit Score?
A loan rejection itself is not the same as a missed payment or default. However, applying for credit can result in credit enquiries, depending on the lender and bureau-reporting process.
Therefore, repeated applications in a short period should be avoided unless you understand why previous applications were unsuccessful.
Can You Apply Again After Rejection?
Yes, but applying again immediately may not solve the problem.
Before reapplying:
- Find the rejection reason.
- Review your credit report.
- Correct documentation errors.
- Assess existing debt.
- Improve income or repayment capacity where possible.
- Compare lenders and their eligibility criteria.
Important Safety Tip for Loan Apps
Be cautious of apps promising guaranteed approval or asking for money before processing a loan.
Before submitting documents, verify the actual lender and review the loan terms. RBI's digital-lending framework includes requirements around creditworthiness assessment, borrower information and transparency in digital lending.
Key Takeaways
- Instant loan rejection can happen for several financial or verification reasons.
- Credit history, income, existing EMIs and KYC are important factors.
- Document mismatches can delay or stop an application.
- Internal lender policies can also affect approval.
- Check the rejection reason before applying again.
- Avoid multiple loan applications without understanding the cause.
- Verify the actual lender before sharing personal or financial information.
FAQs
Why was my instant loan rejected?
Common reasons include credit history, insufficient income, high existing debt, KYC problems, document mismatches and lender-specific eligibility rules.
Can a loan be rejected after instant approval?
Yes. An initial or automated indication may be subject to further verification before final approval and disbursal.
Does loan rejection reduce my credit score?
The rejection itself does not necessarily reduce your score, but credit enquiries associated with applications can appear on your credit report.
Can I apply for another loan after rejection?
Yes, but it is better to understand and address the rejection reason before submitting another application.
How can I improve my loan eligibility?
Maintain timely repayments, manage existing debt, keep documents accurate and avoid unnecessary credit applications.
Does income affect personal loan approval?
Yes. Lenders may assess income and repayment capacity when deciding whether to approve a loan.
Can high EMI obligations cause rejection?
Yes. Significant existing EMI obligations can affect the lender's assessment of your ability to repay another loan.
Can incorrect KYC details cause rejection?
Yes. Mismatched or incomplete KYC information can prevent successful verification.
What if the lender does not explain my rejection?
Contact the lender's customer-service or grievance-redressal channel and request the applicable reason for rejection. RBI guidance provides for communication of the main reasons for loan rejection by regulated lenders within the applicable timeframe.
Should I use another loan app after rejection?
Do not choose another app simply because it promises guaranteed approval. Verify the actual lender, compare terms and understand why the first application was rejected.
Final Word
An instant loan rejection does not necessarily mean you cannot borrow in the future. The useful first step is to identify the reason, check your credit and documents, review your existing debt and then decide whether another application is appropriate.
Published on : 23th September
Published by : Shibam Nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed