

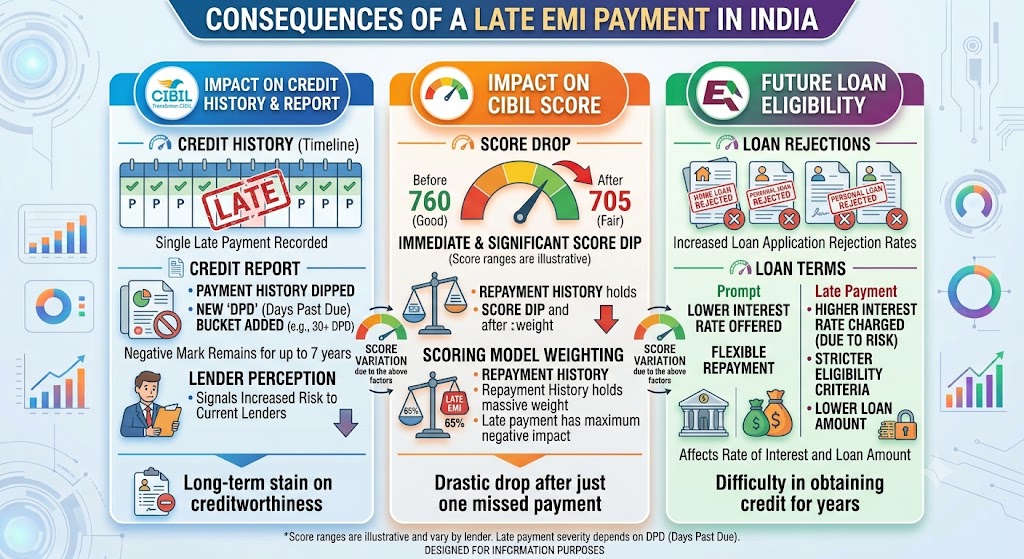
Paying your loan EMI on time is one of the most important habits for maintaining a healthy credit profile. Whether you have a personal loan, home loan, car loan, or another type of credit, missing an EMI payment can affect your credit history and may reduce your CIBIL score.
Many borrowers assume that a payment delay of just a few days will have no consequences. However, a late EMI can lead to additional charges, collection follow-ups, and potential credit-reporting issues, depending on the delay and the lender's policies.
In this guide, we explain how late EMI payments affect your CIBIL score, what happens when you miss a payment, and how you can protect your credit profile.
What Is an EMI?
EMI stands for Equated Monthly Instalment. It is the fixed periodic payment a borrower makes toward a loan. An EMI generally includes both principal and interest.
For example, if you take a personal loan, you must pay the agreed EMI on or before the due date specified in your loan agreement. Regular payments help demonstrate responsible credit behaviour.
How Does a Late EMI Affect Your CIBIL Score?
Your credit score reflects information in your credit history, including your repayment behaviour. When a lender reports a delayed payment to a credit bureau, it may negatively affect your credit profile.
The impact depends on factors such as the length of the delay, your previous repayment history, outstanding debt, and the scoring model used.
Here are some possible consequences of a late EMI:
1. Your Credit Score May Decrease
A reported late payment can negatively affect your CIBIL score. The impact is not identical for every borrower, and there is no fixed number of points that every person will lose.
Borrowers with an otherwise strong repayment history can also experience a negative impact when a missed payment is reported.
2. Your Credit Report May Show a Payment Delay
Lenders submit repayment information to credit bureaus. Depending on the reporting and applicable requirements, your credit report may reflect that an EMI was not paid as scheduled.
This information can influence how future lenders assess your creditworthiness.
3. Additional Charges May Apply
Depending on your loan agreement, a missed EMI may result in late-payment charges, penal charges where applicable, or other contractual consequences.
Check your loan agreement and Key Facts Statement (KFS) to understand the charges that apply to your loan.
4. Future Loan Approval May Become More Difficult
Lenders may consider your repayment history when evaluating applications for personal loans, home loans, vehicle loans, or credit cards.
Repeated payment delays may raise concerns about repayment reliability. However, a late EMI does not automatically mean that every future loan application will be rejected.
5. Repeated Delays Can Increase Financial Pressure
If missed payments continue, outstanding dues and applicable charges can accumulate. Continued non-payment may also lead to collection activity and more serious credit-reporting consequences.
Paying on time and contacting your lender early can help you manage a temporary financial difficulty before it becomes more serious.
Does a One-Day EMI Delay Affect CIBIL?
A one-day delay does not necessarily mean that a negative entry will immediately appear on your credit report. The outcome depends on the lender's processes, applicable reporting requirements, and the timing of payment and reporting.
However, borrowers should not assume that a short delay is always harmless. Pay as soon as possible, keep proof of payment, and contact the lender if you are concerned about how the delay will be recorded.
How Long Does a Late EMI Stay on Your Credit Report?
The duration for which late-payment information remains on a credit report depends on applicable credit-reporting practices and the bureau's records. A reported late payment may remain visible for an extended period and can influence lenders' assessment of your credit history.
Paying the overdue EMI can bring the account up to date, but it does not necessarily erase an accurately reported historical delay.
If the information is incorrect, you can raise a dispute with the relevant credit bureau and the lender that supplied the information.
What Should You Do After Missing an EMI?
If you have missed an EMI, take these practical steps:
Step 1: Pay the overdue amount as soon as possible. Check the amount due, including any applicable charges, through your lender's official payment channel.
Step 2: Contact your lender. Ask about the outstanding amount, payment status, and any charges that apply.
Step 3: Keep the payment receipt. Save the transaction reference and confirmation for your records.
Step 4: Check your credit report. Review the repayment status after the lender has had time to update the information.
Step 5: Dispute incorrect information. If a payment was made on time but incorrectly reported as late, submit evidence to the lender and the relevant credit bureau.
Step 6: Set up payment reminders. Use calendar alerts or automatic payments where appropriate, ensuring that sufficient funds are available.
How to Improve Your CIBIL Score After Late EMI Payments
You can take steps to strengthen your credit profile after a delayed payment, although score improvement is not guaranteed within a particular timeframe.
-
Pay all future EMIs on or before their due dates.
-
Clear overdue amounts and keep loan accounts up to date.
-
Avoid taking on more debt than you can comfortably repay.
-
Keep credit card utilisation under control.
-
Check your credit report regularly for errors.
-
Avoid unnecessary credit applications in a short period.
-
Maintain a consistent repayment record over time.
Remember, an accurate late-payment record generally cannot be removed simply because the overdue amount has been paid. The best approach is to maintain good repayment habits and correct any genuine reporting errors.
Frequently Asked Questions (FAQs)
1. Does a late EMI reduce my CIBIL score?
It may reduce your score if the delay is reported and affects your credit profile. The exact impact varies by borrower and scoring model.
2. Can one missed EMI affect loan approval?
Yes, it may influence a lender's assessment, but approval also depends on income, existing debt, repayment capacity, and lender-specific criteria.
3. Will my CIBIL score recover after paying a late EMI?
Your profile may improve with consistent repayments over time. However, the recovery period and score change cannot be guaranteed.
4. Can I remove a late EMI entry from my CIBIL report?
An accurate entry generally cannot be removed merely because you have paid the overdue amount. If the entry is incorrect, raise a dispute with the credit bureau and lender.
5. What happens if I repeatedly miss EMIs?
Repeated delays can negatively affect your credit history, increase applicable charges, and make future borrowing more difficult.
6. How can I avoid late EMI payments?
Set reminders, maintain sufficient funds, monitor due dates, and use automatic payment options where suitable.
Conclusion
Late EMI payments can affect your CIBIL score, increase borrowing costs, and influence future loan applications. The seriousness of the impact depends on the delay, reporting practices, and your overall credit history.
If you have missed an EMI, act promptly: pay the overdue amount, communicate with your lender, retain payment proof, and review your credit report. Consistent repayments are among the most important steps toward maintaining a healthy credit profile.
Published on : 17th October 2026
Published by : yogendra
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disburse