

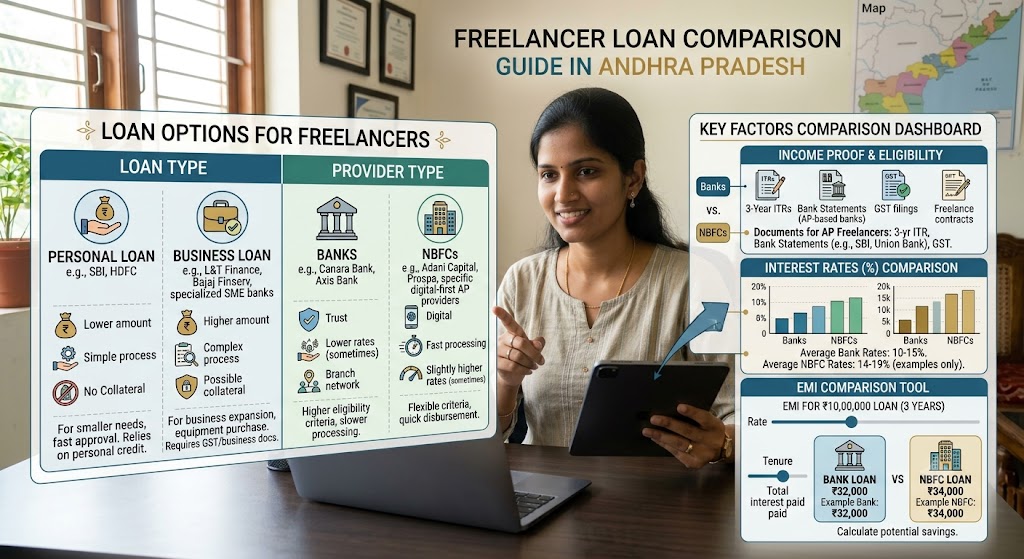
Freelancers in Andhra Pradesh may have different borrowing needs from salaried employees because their income can depend on client projects, contracts and payment schedules. When applying for a personal loan, comparing lenders, eligibility requirements and repayment terms can help freelancers choose an option that fits their financial situation.
Whether you work in software development, graphic design, content writing, digital marketing, consulting or another freelance profession, it is important to understand how different loan options work before submitting an application.
This comparison guide explains the differences between personal loans and other borrowing options, the documents freelancers may need, and the key factors to compare before accepting a loan.
1. Personal Loan vs Business Loan for Freelancers
Freelancers may consider personal loans for individual expenses or business loans for eligible professional purposes. The appropriate option depends on the lender's product terms and how the funds will be used.
| Feature | Personal Loan | Business Loan |
|---|---|---|
| Main purpose | Personal expenses, subject to loan terms | Eligible business or professional expenses |
| Income assessment | May consider personal income and repayment capacity | May assess business income and financial performance |
| Documents | KYC, bank statements and income proof, as required | May require business and financial records |
| Repayment | Usually through scheduled instalments | Depends on the product and agreement |
| Eligibility | Based on lender-specific criteria | Based on lender-specific business and borrower criteria |
Which is better? A personal loan may suit eligible personal expenses, while a business loan may be more appropriate for qualifying professional expenses. Compare the actual terms rather than assuming one product is always cheaper or easier to obtain.
2. Bank Loan vs NBFC Loan
Freelancers may encounter personal loan offers from banks and non-banking financial companies (NBFCs). Both can offer lending products, but their eligibility rules, pricing and processes may differ.
| Comparison factor | Bank | NBFC |
|---|---|---|
| Eligibility criteria | Vary by bank and product | Vary by NBFC and product |
| Income verification | Depends on the lender's policy | Depends on the lender's policy |
| Interest rate | Depends on the borrower and offer | Depends on the borrower and offer |
| Processing time | Varies by application and verification | Varies by application and verification |
| Documentation | Product-specific | Product-specific |
| Regulatory status | Verify the bank through official sources | Verify the NBFC through official RBI sources |
Neither option is automatically better for every freelancer. Compare the annualized cost, repayment conditions, service quality and eligibility requirements of the actual lender.
3. Salary Slip vs Alternative Income Proof
One common concern among freelancers is the absence of a traditional salary slip.
Unlike salaried applicants, freelancers may receive payments from several clients. Depending on the lender's policy, alternative documents may help demonstrate income.
| Document | How it may help |
|---|---|
| Bank statements | Show incoming payments and transaction patterns |
| Income Tax Returns (ITRs) | Provide evidence of reported income, where required |
| Client invoices | Record amounts billed for completed work |
| Client contracts | Show agreed professional engagements |
| Payment records | Help document money received from clients |
| Business records | May support additional financial verification |
Not every lender accepts all these documents. Check the requirements of your chosen loan product before applying.
4. Secured Loan vs Unsecured Personal Loan
Freelancers may also compare secured and unsecured borrowing options.
| Feature | Secured Loan | Unsecured Personal Loan |
|---|---|---|
| Collateral | Generally requires an eligible asset or security | Usually does not require collateral |
| Approval assessment | Depends on the borrower, security and product terms | Depends on the borrower's financial profile and lender criteria |
| Interest rate | May be lower in some cases, but not always | Depends on the lender and borrower profile |
| Main risk | The pledged asset may be at risk if repayment obligations are not met | Missed payments may result in charges and affect credit history |
A secured loan is not automatically cheaper, and an unsecured loan is not automatically available to every freelancer. Compare the complete cost and understand the consequences before borrowing.
5. What Factors Should Freelancers Compare Before Applying?
Before choosing a lender in Andhra Pradesh, review these important factors.
Credit Score and Repayment History
Lenders may consider your credit report, previous repayments, outstanding balances and other credit information. A good credit score can support an application, but it does not guarantee approval.
Income Stability
Freelancers should estimate average income across several months rather than relying on one high-paying project. Bank statements and other accepted records may help demonstrate income patterns.
Existing EMIs
Existing loan repayments reduce the amount available for a new EMI. Calculate your current obligations and essential expenses before deciding how much to borrow.
Loan Amount and Tenure
Choose an amount that meets your actual needs. A longer tenure may reduce the monthly EMI but can increase total interest paid.
Total Borrowing Cost
Compare the interest rate, Annual Percentage Rate (APR), processing fees, applicable taxes, late-payment charges, prepayment conditions and total repayment.
For covered digital loans, the applicable Reserve Bank of India (RBI) framework includes requirements for disclosing key loan information through a Key Facts Statement (KFS). Read the KFS and loan agreement before accepting an offer.
6. Example: Comparing Two Illustrative Loan Offers
Suppose a freelancer in Visakhapatnam compares two hypothetical offers for the same loan amount.
| Detail | Offer A | Offer B |
|---|---|---|
| Loan amount | ₹1,00,000 | ₹1,00,000 |
| Interest rate | 14% per year | 16% per year |
| Tenure | 24 months | 24 months |
| Processing fee | Must be checked | Must be checked |
| Other applicable charges | Must be checked | Must be checked |
Based on the stated rates alone, Offer A has the lower interest rate. However, the freelancer should not make a final decision until the APR, processing fees, other charges and total repayment are compared.
These figures are illustrative only and do not represent current offers from any specific lender.
7. How Can Freelancers Choose the Right Loan?
Use this practical checklist before applying:
-
Identify whether you need a personal loan or a business loan.
-
Compare banks and verified NBFCs.
-
Check whether the lender accepts your available income documents.
-
Review your credit report and existing financial obligations.
-
Calculate an affordable EMI using realistic income estimates.
-
Compare APR, fees, tenure and total repayment.
-
Read the KFS and loan agreement where applicable.
-
Verify the actual lender and submit documents only through authorized channels.
Avoid choosing a loan solely because an app advertises instant approval. Final approval depends on verification and the lender's assessment.
8. Digital Loan Safety for Freelancers
When comparing online loan offers, confirm the identity of the actual lender and review the app's privacy policy.
Never share OTPs, UPI PINs, ATM PINs or internet-banking passwords with loan agents or suspicious apps. Be cautious of guaranteed-approval promises, unexplained upfront payment demands and pressure to accept an offer immediately.
For official information about regulated lenders and digital lending, visit the Reserve Bank of India website: https://www.rbi.org.in/.
Frequently Asked Questions
1. Which loan is better for freelancers in Andhra Pradesh?
It depends on the purpose of borrowing, income profile, eligibility and loan terms. Compare personal and business loans according to their permitted uses and total costs.
2. Can freelancers apply for bank personal loans?
Yes. Freelancers may apply if they meet the bank's eligibility criteria and provide the required documentation.
3. Are NBFC loans available to freelancers?
Some NBFCs offer products that eligible freelancers may apply for. Requirements, interest rates and fees differ by lender.
4. Can freelancers apply without a salary slip?
Some lenders accept alternative income documents, such as bank statements, ITRs and client payment records. Requirements vary.
5. Is a secured loan better than an unsecured loan?
Not necessarily. A secured loan involves collateral, while an unsecured personal loan generally does not. Compare the full cost, eligibility and risks before choosing.
6. What should freelancers compare when choosing a loan?
Compare eligibility, accepted income documents, interest rate, APR, processing fees, tenure, EMI, total repayment and applicable prepayment conditions.
7. Does a good credit score guarantee loan approval?
No. Lenders may also consider income stability, existing EMIs, documentation and other eligibility criteria.
Published on : 14th October 2026
Published by : Shibam nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed