

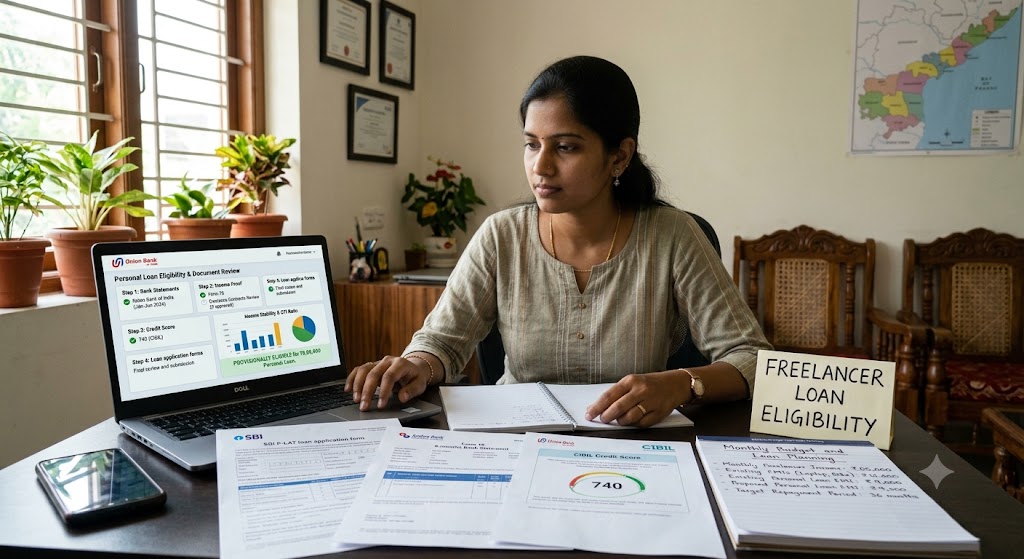
Freelancing is becoming a popular career choice in Andhra Pradesh, with professionals earning through content writing, graphic design, software development, digital marketing, consulting and other independent services. However, freelancers may sometimes find it difficult to understand personal loan eligibility because their income can vary from month to month.
Unlike salaried employees, freelancers may not have a regular salary slip or a fixed monthly income. This does not automatically make them ineligible for a loan. Lenders may evaluate their income records, bank statements, credit history, existing EMIs and overall repayment capacity.
Understanding the common myths and facts about loan eligibility for freelancers in Andhra Pradesh can help self-employed professionals prepare a stronger application and make informed borrowing decisions.
What Is Loan Eligibility for Freelancers?
Loan eligibility refers to the criteria a lender uses to decide whether an applicant qualifies for a loan. For freelancers, these criteria may include income stability, credit history, work experience, financial documents and existing financial obligations.
Eligibility requirements differ between banks, NBFCs and digital lending products. There is no single income level or credit score that guarantees approval for every freelancer.
Common Myths and Facts About Freelancer Loan Eligibility
Myth 1: Freelancers Cannot Get Personal Loans
Fact: Freelancers may qualify for personal loans if they meet the lender's eligibility requirements.
Lenders can consider income earned through freelance projects, consulting, online services and other independent work. They may ask for supporting financial records to assess whether the applicant can repay the loan.
Tip: Maintain clear records of client payments, invoices and bank transactions.
Myth 2: A Salary Slip Is Compulsory for Every Loan
Fact: A salary slip is not necessarily required for every freelancer loan application.
Because freelancers are generally self-employed, lenders may accept alternative documents, depending on their policies. These may include:
-
Recent bank statements
-
Income Tax Returns (ITRs)
-
Client invoices and payment records
-
Business or professional income documents
-
Proof of identity and address
Confirm the accepted documents with the lender before applying.
Myth 3: Irregular Monthly Income Means Automatic Rejection
Fact: Variable income does not automatically result in rejection.
Freelancers may earn different amounts depending on their projects and payment schedules. A lender may examine income over a period of time to understand its consistency and whether it can support the proposed EMI.
For example, a freelance designer might earn ₹35,000 in one month and ₹55,000 in another. The lender may consider the broader income pattern rather than relying on one month's earnings alone.
Tip: Keep a separate record of freelance income and regular expenses.
Myth 4: A High Credit Score Guarantees Loan Approval
Fact: A good credit score can help, but it does not guarantee approval.
Lenders may also evaluate your income, existing debt, requested loan amount, repayment history, documents and internal eligibility criteria.
Even applicants with strong credit histories may be declined if their documented income is insufficient for the proposed repayments.
Myth 5: Freelancers Must Have a Registered Company
Fact: A registered company is not always necessary for a freelancer to apply for a personal loan.
Some individuals provide professional services in their own name. However, the requirements depend on the loan product and lender. A business loan may involve different documentation from a personal loan.
Check whether the lender offers a suitable product for individual freelancers or self-employed professionals.
Myth 6: Applying Through Any Instant Loan App Is Safe
Fact: Not every loan app is trustworthy.
Before submitting personal or financial information, verify the actual lender and confirm that the digital lending arrangement is legitimate. Review the interest rate, Annual Percentage Rate (APR), fees, repayment schedule and Key Facts Statement (KFS), where applicable.
Avoid apps or agents that demand advance payments under suspicious conditions or request your OTP, UPI PIN, ATM PIN or banking password.
For official information, consult the Reserve Bank of India (RBI).
Documents Freelancers May Need for a Loan
The exact requirements depend on the lender and loan type. Commonly requested documents may include:
| Document | Why it may be needed |
|---|---|
| PAN | Tax and identity verification |
| Aadhaar or another accepted identity document | KYC verification, where applicable |
| Bank statements | Review of income and financial transactions |
| ITRs | Evidence of declared income, where required |
| Client invoices or contracts | Supporting evidence of freelance work |
| Address proof | Address verification |
| Existing loan details | Assessment of current repayment obligations |
Submit documents only through verified and authorized channels. Never share confidential banking credentials.
How Freelancers in Andhra Pradesh Can Improve Loan Eligibility
1. Maintain Consistent Financial Records
Keep invoices, client contracts, payment receipts and bank statements organized. Clear records can help demonstrate your freelance income.
2. File Income Tax Returns Where Required
Accurate tax records can support income verification. Keep your ITRs and related documents ready if the lender requests them.
3. Pay EMIs and Credit-Card Bills on Time
Timely repayments help build a positive credit history. Review your credit report and raise disputes if you identify genuine errors.
4. Calculate Your Repayment Capacity
Before applying, account for rent, household expenses, business costs and existing EMIs. Choose a loan amount that fits your finances, including months when freelance earnings may be lower.
5. Compare Lenders Carefully
Compare the APR, interest rate, processing fees, tenure, EMI and total repayment amount. Do not select a loan solely because an app advertises quick approval.
Example: Understanding a Freelancer's Loan Application
Suppose a freelance digital marketer based in Vijayawada earns between ₹30,000 and ₹50,000 per month. The person maintains bank statements, records client payments and files income tax returns where applicable.
These records may help the lender understand the applicant's income pattern. However, approval would still depend on the lender's eligibility criteria, credit assessment, existing financial commitments and document verification.
This is an illustrative example, not a guarantee of loan approval.
Checklist Before Applying for a Freelancer Loan
Before submitting your application, check the following:
-
My KYC information is accurate and up to date.
-
I can provide the income documents required by the lender.
-
My bank statements reflect my financial transactions clearly.
-
I have reviewed my credit report.
-
I have calculated my existing EMIs and expected new EMI.
-
I have compared interest rates, APR and fees.
-
I have verified the actual lender.
-
I have reviewed the KFS and loan agreement where applicable.
Key Takeaways
-
Freelancers in Andhra Pradesh may qualify for personal loans if they meet the lender's requirements.
-
A salary slip is not compulsory for every loan product; alternative income documents may be accepted.
-
Irregular earnings do not automatically mean rejection.
-
A good credit score helps but cannot guarantee approval.
-
Bank statements, ITRs and client payment records may support income verification.
-
Always check the APR, fees, EMI and total repayment before accepting an offer.
-
Verify the lender and protect your KYC and banking information.
Frequently Asked Questions (FAQs)
1. Can freelancers in Andhra Pradesh get personal loans?
Yes, freelancers may qualify if they meet the lender's income, credit, documentation and repayment-capacity requirements.
2. Is a salary slip required for a freelancer loan?
Not always. Depending on the lender, alternative documents such as bank statements, ITRs and client payment records may be accepted.
3. Can I apply for a loan if my freelance income changes every month?
Possibly. A lender may assess your income pattern over time, but acceptance depends on its eligibility rules and your overall financial profile.
4. Do freelancers need ITRs to apply for a loan?
Some lenders may require ITRs, while others may accept different forms of income evidence. Check the specific product requirements.
5. Does a good credit score guarantee loan approval?
No. Income, existing debt, documentation and lender-specific criteria can also affect the decision.
6. Can a freelancer without a registered company apply for a personal loan?
Potentially, yes. Some personal loan products are available to individuals, subject to the lender's requirements.
7. What is the safest way to apply for an online loan?
Verify the actual lender, use its genuine or authorized application process, review the loan documents and never share OTPs, PINs or banking passwords.
8. How can freelancers improve their loan eligibility?
Maintain organized income records, pay existing debts on time, check credit reports, reduce unnecessary debt and apply for an affordable loan amount.
Conclusion
Loan eligibility for freelancers in Andhra Pradesh depends on more than whether they receive a fixed salary. Income documentation, credit history, existing EMIs and repayment capacity can all influence the lender's decision.
Published on : 14th October 2026
Published by : Shibam nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed