

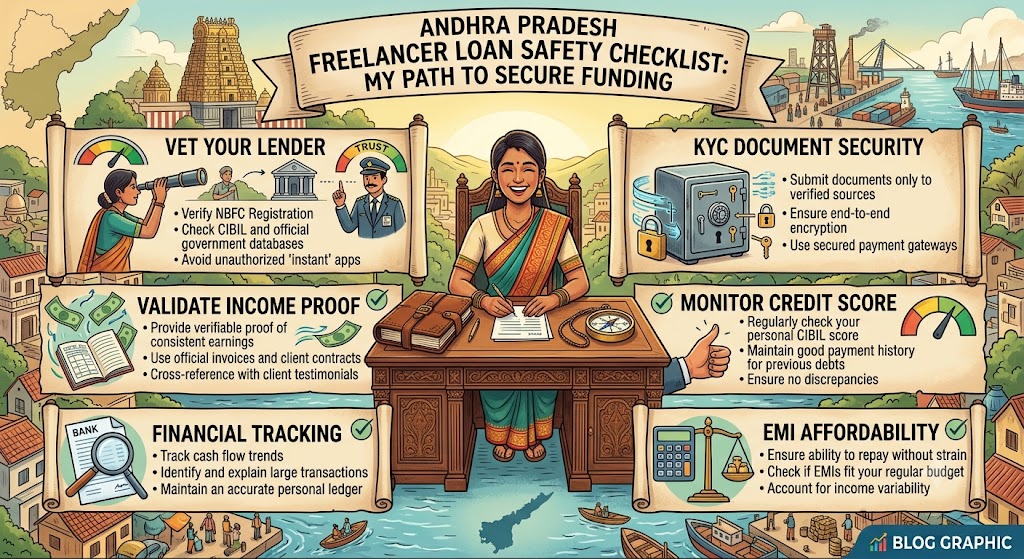
Freelancers in Andhra Pradesh often depend on project payments, client contracts and independent work for their income. Whether you work in digital marketing, software development, graphic design, content writing, consulting or another freelance field, applying for a personal loan may involve different documentation and income-verification requirements than a salaried application.
Before applying, it is important to understand the lender's eligibility criteria, verify the loan provider and review the complete borrowing cost. A safe application process can help you protect your financial information and avoid unnecessary debt.
This freelancer loan eligibility safety checklist for Andhra Pradesh explains what to verify before submitting an online loan application.
1. Verify the Actual Lender Before Applying
One of the most important safety steps is checking who will actually provide the loan.
A mobile application may be operated by a lending service provider, while the loan itself is issued by a bank or an RBI-registered non-banking financial company (NBFC).
Before proceeding:
-
Identify the bank or NBFC providing the loan.
-
Verify the lender's details through official sources.
-
Check whether the app or lending service provider is associated with the stated lender.
-
Read the lender's privacy policy and terms of service.
-
Avoid unknown apps that make unrealistic approval promises.
Safety tip: Do not assume an app is genuine simply because it appears in an app store or advertises instant approval.
2. Check Your Freelancer Loan Eligibility
Freelancers may not receive a fixed monthly salary, so lenders can assess income stability and repayment capacity using different documents.
Depending on the lender and loan product, eligibility checks may include:
-
Age and residential details
-
Freelance occupation and work history
-
Average monthly income
-
Credit score and repayment history
-
Existing loans and EMIs
-
Bank statements showing client payments
-
Income Tax Returns (ITRs), where required
-
PAN and other KYC documents
Requirements differ between lenders. There is no single income amount or credit score that guarantees approval for every freelancer.
Safety tip: Check the eligibility criteria before applying. This helps you avoid unnecessary applications and potential credit enquiries.
3. Submit Income Documents Through Secure Channels
Freelancers may receive payments from multiple clients, making accurate income documentation particularly important.
Commonly requested documents can include:
-
Bank statements
-
Client invoices or payment records
-
Freelance contracts, where applicable
-
ITRs or other income documents, where required
-
PAN and accepted KYC documents
Use only the lender's official website or authorized application to submit these records. Confirm that the website or app is genuine before uploading sensitive information.
Never send financial documents to an unknown person through an unverified WhatsApp number, email address or social media account.
4. Protect Your PAN, Aadhaar and Banking Information
Digital loan applications can involve identity verification, so protecting personal information is essential.
Follow these precautions:
-
Submit only the documents genuinely required for verification.
-
Review the app's permissions before granting access.
-
Do not share OTPs, UPI PINs, ATM PINs or internet-banking passwords.
-
Avoid uploading documents through suspicious links.
-
Do not install unknown applications at an agent's request.
-
Never allow another person to control your banking app or phone remotely.
Legitimate verification processes should not require you to disclose your banking PINs or passwords to a loan agent.
Important: If an app requests excessive access to your contacts, call logs or other personal information without a clear, lawful purpose, stop and verify the lender and its privacy practices before continuing.
5. Calculate Your EMI and Repayment Capacity
Loan eligibility is not just about whether a lender will approve your application. You should also determine whether you can repay the loan comfortably.
Freelance income may change from month to month. A good approach is to assess your income over several months and account for essential expenses, taxes and possible gaps between projects.
For example, suppose a freelancer earns an average of ₹50,000 per month but already pays ₹12,000 in existing EMIs. A new loan would increase the monthly repayment burden beyond the existing ₹12,000.
Before applying, calculate:
-
Average monthly income after accounting for irregular payments
-
Existing EMIs and debt obligations
-
Essential household and business expenses
-
Proposed new EMI
-
Emergency savings
-
Total repayment over the loan tenure
Do not rely on your highest-earning month when deciding how much you can borrow.
6. Review the Interest Rate, APR and Loan Charges
A loan advertised as quick or convenient may still be expensive. Compare the total cost instead of focusing only on the EMI or advertised interest rate.
Check the following before accepting an offer:
| Loan detail | What to verify |
|---|---|
| Interest rate | Whether it is fixed or variable, as applicable |
| APR | The annualized cost of borrowing, including applicable charges |
| Processing fee | The amount charged and applicable taxes |
| EMI | Whether the instalment fits your budget |
| Loan tenure | How long you will repay |
| Late-payment charges | The consequences of missed payments |
| Prepayment terms | Any applicable conditions or charges |
| Total repayment | The total amount payable over the loan term |
For covered digital loans, RBI requirements include providing a Key Facts Statement (KFS) with important loan information and disclosing the Annual Percentage Rate (APR).
Read these details carefully before accepting the loan agreement.
7. Watch for Loan App Fraud and Upfront Payment Scams
Be cautious if a loan app or agent:
-
Guarantees approval regardless of your financial profile.
-
Demands an unexplained advance payment to release the loan.
-
Pressures you to accept immediately.
-
Refuses to identify the actual lender.
-
Hides fees or interest rates.
-
Threatens to contact your friends or family.
-
Requests OTPs, PINs or banking passwords.
An upfront payment demand is not automatically proof of fraud in every circumstance, but unexplained or suspicious requests should be independently verified before you pay.
If you suspect a digital lending scam in India, contact your bank or payment provider promptly if money has been lost. You can also report cyber financial fraud through India's official cybercrime reporting portal at cybercrime.gov.in or call 1930 for assistance with financial cyber fraud.
8. Keep a Copy of Every Loan Document
Before finalizing a loan, save copies of the important records, including:
-
Loan application details
-
Sanction letter or loan offer
-
Key Facts Statement
-
Loan agreement
-
Repayment schedule
-
Fee and charge disclosures
-
Lender's grievance contact details
-
Payment receipts and account statements
These records can help you understand your obligations and support a complaint if a dispute arises.
If the loan is approved, confirm the final terms and the identity of the lender before proceeding with the agreement and disbursal.
Quick Safety Checklist for Freelancers in Andhra Pradesh
Use this checklist before submitting your application.
-
I have verified the actual bank or NBFC providing the loan.
-
I have checked the lender's eligibility requirements.
-
My income and KYC information are accurate.
-
I am submitting documents through an authorized channel.
-
I have not shared my OTP, PIN or banking password.
-
I have calculated my existing EMIs and the proposed new EMI.
-
I have compared the APR, processing fee and total repayment.
-
I have reviewed the KFS and loan agreement.
-
I have saved the loan documents and lender's contact details.
-
I can manage the repayment even if my freelance income falls.
Frequently Asked Questions
1. Can freelancers in Andhra Pradesh apply for personal loans?
Yes. Freelancers may apply for personal loans, subject to the lender's eligibility criteria, income assessment, credit profile and documentation requirements.
2. Do freelancers need a salary slip to apply for a loan?
Not always. Depending on the lender, bank statements, ITRs, client payment records or other acceptable income documents may be considered.
3. Is a high credit score enough to guarantee loan approval?
No. Lenders may also assess income stability, existing EMIs, documentation and overall repayment capacity.
4. Is it safe to submit Aadhaar and PAN through a loan app?
Only submit documents through a verified lender's official or authorized channel. Review the app's privacy terms and avoid suspicious links or unverified agents.
5. What is the KFS in a digital loan?
KFS stands for Key Facts Statement. It presents key loan terms and cost information, including the applicable APR, to help borrowers understand the offer.
6. What should freelancers check before accepting a loan?
Verify the lender, confirm eligibility, calculate affordability, compare APR and fees, read the KFS and agreement, and keep copies of all documents.
7. What should I do if a loan app threatens or harasses me?
Preserve messages and other evidence, contact the actual lender through its official grievance channel and report suspected cybercrime or financial fraud to the appropriate Indian authorities.
Published on : 13th October 2026
Published by : Shibam nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed