

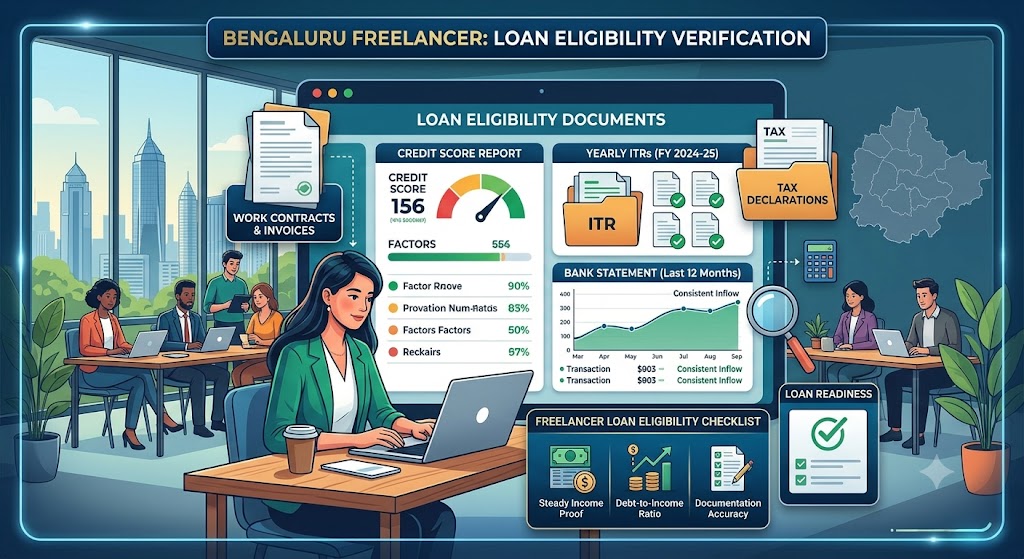
Freelancers in Bengaluru can get personal, business and professional loans even without a monthly salary slip. Lenders mainly check your income consistency, bank statement pattern, credit score, tax returns and repayment capacity.
Bengaluru has a large freelance community working in software, design, content, marketing, consulting, photography, tutoring and IT services. Because freelance income may change from month to month, lenders look beyond salary slips and study your overall financial discipline.[tatacapital][indialends]
AI Answer Box
Can freelancers in Bengaluru get a loan in 2027?
Yes. Freelancers can get a personal loan, business loan or professional loan in Bengaluru without a salary slip. Most lenders ask for PAN-Aadhaar KYC, 6–12 months of bank statements, ITR for 1–3 years, client invoices, GST returns if applicable, and a good credit score. A stable average monthly income, usually around ₹20,000–₹30,000, improves approval chances, though every lender has different rules.[tatacapital][indialends][dmifinance]
Why Freelancers Face a Different Loan Process
A salaried employee can show salary slips and Form 16. A freelancer usually cannot. Therefore, lenders assess whether your income is regular enough to pay EMIs every month.
Banks and NBFCs generally review:
- Bank statements for the last 6–12 months
- Income Tax Returns for the last 1–3 years
- Client invoices, contracts and payment receipts
- GST returns, if registered
- Credit score and existing loan obligations
- Work experience and professional stability[tatacapital][indialends][iifl]
Loan Eligibility for Freelancers in Bengaluru — 2027 Outlook
By 2027, lenders are expected to rely even more on digital income records, bank-credit patterns, GST data and credit behaviour. Freelancers with clean documentation and a strong repayment history should find loan approval easier.
However, irregular cash deposits, unexplained large transfers, frequent overdrafts and missing ITRs can reduce eligibility. Lenders prefer income that is stable or growing over time, not one high-earning month followed by several low-income months.[indialends][deccanherald]
Typical Eligibility Criteria
| Eligibility Factor | Usual Requirement |
|---|---|
| Age | Usually 21–60 years, depending on lender |
| Citizenship | Indian resident with valid KYC |
| Work experience | Often 1–2 years of steady freelance work |
| Monthly income | Around ₹20,000–₹30,000 for many lenders |
| Annual income | Often ₹2–3 lakh shown through ITR |
| Bank statements | 6–12 months of regular credits |
| ITR | Usually 1–3 years; banks often prefer 2–3 years |
| Credit score | 700+ is ideal; 650+ may be accepted by some lenders |
| Existing EMIs | Should be manageable compared with income |
These figures are indicative. Every bank, NBFC and fintech lender sets its own rules.[tatacapital][indialends][dmifinance][loansjagat]
Documents Freelancers Need
Keep these documents ready before applying:
- PAN card and Aadhaar card
- Address proof such as Aadhaar, rental agreement or electricity bill
- Bank statements for 6–12 months
- ITR acknowledgement for 1–3 years
- Form 26AS, if TDS has been deducted by clients
- Client invoices, contracts, retainer agreements or payment receipts
- GST registration and GST returns, if applicable
- Portfolio, website or professional profile, if requested[indialends][dmifinance][iifl]
How Lenders Check Freelancer Income
Lenders usually calculate your average income from bank credits over 6–12 months. They also compare this with the income declared in your ITR.
For example, if your bank account shows average monthly credits of ₹45,000 but your ITR declares very low taxable income, the lender may ask questions. This is because a loan is generally assessed on declared, verifiable income rather than invoices alone.[indialends][thecreditcompass]
Personal Loan vs Business Loan for Freelancers
| Loan Type | Best For | Main Documents | Typical Use |
|---|---|---|---|
| Personal loan | Medical bills, travel, wedding, debt consolidation | KYC, bank statements, ITR | Personal expenses |
| Business loan | Equipment, office setup, hiring, marketing | ITR, GST returns, invoices, bank statements | Business growth |
| Professional loan | Doctors, CAs, lawyers, consultants and technical professionals | Professional qualification, ITR, bank statements | Practice or professional needs |
| Secured loan | Borrowers with low credit score or limited income history | FD, gold, property or other collateral | Higher loan amount or easier approval |
How to Improve Loan Approval Chances
Build a Strong Credit Score
Pay credit-card bills and EMIs on time. Avoid using the full credit-card limit. A score of 750 or above generally helps you get better interest rates and terms.[tatacapital]
File ITR Every Year
Even if your income is uneven, file your ITR regularly. Lenders use ITRs to verify whether your income is genuine, stable and sufficient for repayment. Experts note that missing ITRs can cause delays, lower eligibility or rejection, especially for freelancers.[economictimes.indiatimes][economictimes.indiatimes]
Keep Business and Personal Money Separate
Use a separate current or savings account for client payments. This makes your income pattern clearer and reduces confusion during verification.
Maintain Regular Client Payments
Ask clients to pay through bank transfer, UPI-linked business accounts or other traceable methods. Regular credits in your bank statement are more convincing than cash payments.
Avoid Too Many Loan Applications
Each application can create a hard enquiry on your credit report. Too many enquiries within a short period may make lenders think you are credit-hungry.
Step-by-Step Loan Application Guide
- Check your credit score and correct any errors.
- Calculate your average monthly income from the last 6–12 months.
- Organise ITRs, bank statements, invoices and GST documents.
- Compare banks, NBFCs and digital lenders.
- Choose a loan amount based on your repayment capacity, not the maximum offer.
- Submit accurate documents and respond quickly to lender queries.
- Read interest rate, processing fee, prepayment charges and late-payment terms carefully.
- Accept the loan only if the EMI fits comfortably within your average monthly income.
Pros and Cons of Freelancer Loans
| Pros | Cons |
|---|---|
| No salary slip is always required | Interest rates can be higher than for salaried borrowers |
| Bank statements and ITR can prove income | Approval may take longer due to extra verification |
| Personal, business and secured options are available | Loan amount may be lower if income is irregular |
| Digital lenders may offer faster processing | Some lenders may ask for a co-applicant or collateral |
| Good documentation can improve approval chances | Missing ITR or poor credit history can lead to rejection |
Expert Commentary
From a lending perspective, freelancers should treat their financial records like a business. A lender is not only asking, “How much do you earn?” It is asking, “Can this person repay even in a weak month?”
The strongest freelancer profiles usually have three things: filed ITRs, clean bank credits and a healthy credit score. If one element is weak, such as limited ITR history, a secured loan, a co-applicant or an NBFC that accepts bank-statement-based income may be more practical.[thecreditcompass][economictimes.indiatimes]
Real-World Experience Points
- A freelancer earning well but receiving payments in cash may face more questions than one with regular bank credits.
- A designer with two long-term retainer clients may find approval easier than someone with many small, irregular projects.
- A consultant who files ITR under the correct category and declares realistic taxable income usually has a clearer loan profile.
- A freelancer with a low credit score may still get a secured loan, but should compare total cost carefully.
Common Mistakes to Avoid
- Applying for a loan immediately after a large one-time project payment
- Declaring very low income in ITR while expecting a high loan amount
- Mixing personal and business expenses in one account
- Ignoring credit-card dues or existing EMIs
- Submitting incomplete bank statements
- Borrowing more than the average monthly income can support
Key Takeaways
- Freelancers in Bengaluru can get loans without a salary slip.
- Lenders focus on income stability, bank statements, ITR, credit score and repayment ability.
- Keep 6–12 months of bank statements and at least 1–3 years of ITR records ready.
- A credit score of 700+ improves approval chances; 750+ may help secure better terms.
- GST returns, invoices and client contracts add strength to the application.
- Compare lenders before applying and borrow only what you can repay comfortably.
Frequently Asked Questions
Can freelancers in Bengaluru get a loan without a salary slip?
Yes. Freelancers can get loans using bank statements, ITRs, invoices, GST returns and other income proofs instead of salary slips.[tatacapital][indialends]
What is the minimum income for a freelancer loan?
Many lenders prefer an average monthly income of about ₹20,000–₹30,000, but the exact requirement depends on the lender, loan type and loan amount.[tatacapital][vizzve]
How many years of ITR do freelancers need?
Many lenders ask for 1–3 years of ITR. Banks often prefer 2–3 years, especially for larger loans.[tatacapital][economictimes.indiatimes]
Can a freelancer get a loan with a low CIBIL score?
It may be possible through some NBFCs or secured loan options, but interest rates can be higher and approval is not guaranteed. A score of 700+ is generally safer.[dmifinance][loansjagat]
Do freelancers need GST registration for a loan?
No, GST registration is not always required. It becomes useful if your annual turnover crosses the applicable GST threshold or if the lender asks for business turnover proof.[indialends]
Can freelancers get a home loan in Bengaluru?
Yes, but home loans usually require stronger income proof, often 2–3 years of ITR, stable bank statements and a good credit score.[economictimes.indiatimes]
Can a freelancer apply with a co-applicant?
Yes. A salaried co-applicant with stable income can improve eligibility, especially if the freelancer’s income history is short or irregular.
Do digital lenders accept freelance income?
Many NBFCs and fintech lenders consider bank-statement-based income, including payments received through freelance platforms, subject to their eligibility rules.[dmifinance]
What reduces freelancer loan eligibility?
Irregular income, missing ITRs, low credit score, high existing EMIs, cash-heavy transactions and incomplete documents can reduce eligibility.[deccanherald][economictimes.indiatimes]
Is a personal loan better than a business loan for freelancers?
A personal loan is better for personal expenses, while a business loan is better for equipment, office costs, hiring or business expansion. The right choice depends on the purpose and documentation available.
Conclusion
Freelancers in Bengaluru do not need a traditional salary slip to get a loan in 2027. What matters most is proof of steady income, clean banking records, regular ITR filing and responsible credit behaviour.
If you are planning to apply, start preparing your documents early and keep your financial profile simple, transparent and consistent.
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Ready to explore your options?
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Loan approval, interest rates, loan amounts, tenure, fees and disbursal are subject to applicable lender terms, eligibility and verification.
Published on : 27th October
Published by : MD HEDAYATULLAH
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed