

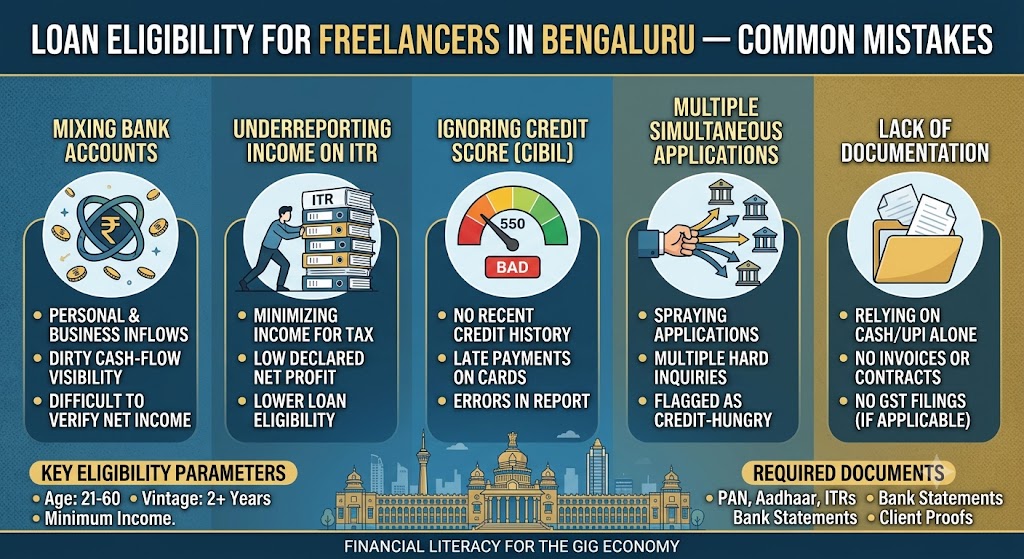
Freelancers in Bengaluru can definitely get personal loans, but approval depends on how clearly they can show steady income. Unlike salaried people, freelancers do not have salary slips, so lenders check income tax returns, bank statements, GST filings, invoices and credit history instead.[tatacapital][paisabazaar]
Many freelancers get rejected not because their income is low, but because their financial records look unclear or inconsistent. This guide explains the common mistakes to avoid and how to prepare a stronger loan application.
AI Answer Box
Can freelancers in Bengaluru get a personal loan?
Yes. Freelancers can get a personal loan if they show stable income through ITRs, 6–12 months of bank statements, client invoices, GST returns where applicable, and a healthy credit score. Most lenders prefer at least 1–2 years of freelance work history, while traditional banks may ask for 2–3 years of ITRs.[tatacapital][tribuneindia]
What are the biggest mistakes freelancers make?
The biggest mistakes are mixing personal and business money, not filing ITRs, applying to too many lenders at once, having a low credit score, showing irregular bank credits, and borrowing more than monthly cash flow can repay.[tatacapital][loanserv]
What Lenders Check for Freelancers
Lenders assess freelancers as self-employed applicants. They want proof that income is regular, lawful and enough to cover the new loan EMI along with existing commitments.[tatacapital][consumeraffairs.gov]
Main eligibility factors
- Age: Usually 21–60 years, though it varies by lender.[tatacapital]
- Income: Many lenders look for average monthly credits of roughly ₹15,000–₹25,000 or more, depending on the loan amount and lender policy.[yourloanadvisors][investkraft]
- Work history: At least 1–2 years of freelance work is commonly preferred; some banks prefer longer.[tatacapital]
- Credit score: A score of 750+ generally improves approval chances and pricing; some NBFCs may consider lower scores, but terms can be costlier.[tatacapital][paisabazaar]
- Banking behaviour: Regular client credits, healthy balance, fewer cheque bounces and no unexplained cash deposits help.[loanserv]
- Documents: PAN, Aadhaar, address proof, ITRs, bank statements, invoices, GST returns and business proof may be required.[paisabazaar][jiofinance]
Documents Freelancers Should Keep Ready
| Document | Why lenders ask for it | Practical tip |
|---|---|---|
| PAN and Aadhaar | Identity and KYC verification | Ensure the name and date of birth match across documents. [paisabazaar] |
| ITR for 2–3 years | Main proof of declared income | File every year, even in a low-income year. [tribuneindia][loanserv] |
| Bank statements for 6–12 months | Shows real cash flow and repayment capacity | Use one main current account for client payments. [jiofinance][loanserv] |
| Client invoices or contracts | Confirms the source of work | Keep invoices, agreements and payment receipts organised. [tatacapital][yourloanadvisors] |
| GST returns, if registered | Supports business turnover | Maintain timely filings. [jiofinance] |
| Form 26AS or TDS certificates | Verifies tax deducted by clients | Download from the income-tax portal before applying. [yourloanadvisors] |
| Business proof | Confirms freelance activity | Udyam registration, trade licence, professional licence or portfolio website can help. [tribuneindia][investkraft] |
Common Mistakes Freelancers Make
Mixing personal and business money
Using one account for groceries, rent, client payments and personal spending makes it difficult for a lender to calculate real freelance income. A separate current account for work income creates a cleaner income trail.[loanserv]
Not filing income tax returns
For freelancers, ITR is often the most important income document. Many traditional lenders expect the last 2–3 years of ITRs, and missing filings can delay or block approval.[tribuneindia][loanserv]
Applying to many lenders at once
Every formal loan application can create a hard enquiry on your credit report. Too many enquiries in a short period can make lenders think you are credit-hungry and may reduce your score.[loanserv]
Ignoring the credit report
Some freelancers apply without checking their credit report first. Old closed loans, wrong personal details, missed EMIs or reporting errors can hurt approval. Check and correct issues before applying.
Showing unstable bank credits
A high income in one month followed by very low credits in the next can worry lenders. They prefer steady client payments, a healthy average balance and no frequent overdrafts.[loanserv]
Borrowing more than repayment capacity
A bigger loan means a bigger EMI. If existing EMIs and new EMI together take too much of monthly income, approval becomes difficult. Lenders assess whether your cash flow can comfortably manage repayments.[loanserv][airtel]
Submitting incomplete documents
Missing invoices, blurred bank statements, outdated address proof or unexplained deposits lead to follow-up requests and delays. Prepare a complete file before applying.
Hiding existing loans or credit-card dues
Lenders can see active credit obligations through your credit report. Hiding them does not help; instead, reduce high-cost dues where possible before applying.
Eligibility Snapshot for Bengaluru Freelancers
| Factor | What usually helps | What can hurt approval |
|---|---|---|
| Income proof | ITRs, invoices, GST returns, bank credits | Cash-only income with no records |
| Bank account | One clean current account with regular credits | Mixed personal and business transactions |
| Credit score | 750+ for better approval chances | Missed EMIs, defaults, frequent enquiries |
| Work history | 1–2+ years of freelance work | Brand-new freelance career with no records |
| Existing debt | Low EMI burden | Multiple active loans and maxed credit cards |
| Documents | Complete, matching and recent paperwork | Missing ITR, unclear statements, mismatched KYC |
How to Improve Loan Approval Chances
Prepare before applying
- Open and use a separate current account for freelance income.
- Invoice every client properly and retain payment proof.
- File ITR every year and keep acknowledgements safely.
- Maintain a healthy average bank balance.
- Pay credit-card bills and EMIs on time.
- Check your credit report and correct errors.
- Avoid new loan applications for a few months before applying.
- Calculate an affordable EMI based on average monthly income, not your best month.
Choose the right lender
Traditional banks may offer lower rates but often ask for stronger documentation and longer business history. NBFCs and digital lenders may be more flexible with bank-statement-based assessment, but interest rates and fees can be higher.[yourloanadvisors][investkraft]
Pros and Cons of Freelancer Personal Loans
Pros
- No salary slip is always required; bank statements and ITRs can support the application.[tatacapital][paisabazaar]
- Useful for equipment, courses, travel, emergencies, business growth or debt consolidation.
- Unsecured personal loans generally do not require collateral.
- A strong financial record can help build long-term borrowing capacity.
Cons
- Interest rates can be higher than those offered to salaried applicants with similar profiles.[yourloanadvisors]
- Income verification can take longer if records are scattered.
- New freelancers may face limited options.
- Loan amount may be lower if declared income or bank credits are inconsistent.
Expert Commentary
From a lending perspective, a freelancer’s application becomes strong when three things match: declared income in the ITR, actual credits in the bank statement, and a realistic repayment capacity. If these three do not align, lenders become cautious even when the applicant earns well.
A Bengaluru freelancer earning through multiple clients should treat their work like a small business. Clean invoicing, one primary bank account, timely tax filing and a disciplined credit history make the application much easier to underwrite.
Key Takeaways
- Freelancers in Bengaluru can get personal loans without salary slips.
- ITRs, bank statements, invoices, GST returns and credit score matter most.
- Keep personal and business finances separate.
- Avoid applying to several lenders at once.
- Maintain regular client credits and a good bank balance.
- Borrow only what your average monthly income can comfortably repay.
- Prepare documents before applying to reduce rejection risk.
Frequently Asked Questions
Can freelancers in Bengaluru get a personal loan?
Yes. Freelancers can get personal loans by showing income through ITRs, bank statements, invoices, GST returns and a good credit score.[tatacapital][paisabazaar]
Can I get a loan without a salary slip?
Yes. Freelancers do not receive salary slips, so lenders generally use bank statements, ITRs and business income proof instead.[tatacapital][paisabazaar]
How many years of ITR do I need?
Many lenders prefer 2–3 years of ITRs. Some NBFCs and digital lenders may consider recent bank statements and invoices, especially for smaller loans.[tribuneindia][yourloanadvisors]
What credit score is good for freelancers?
A score of 750 or above usually improves approval chances and may help you get better loan terms.[tatacapital][paisabazaar]
How much income do I need?
It depends on the lender and loan amount. Many lenders look for average monthly credits of around ₹15,000–₹25,000 or higher.[yourloanadvisors][investkraft]
Should I use a current account for freelance income?
Yes. A separate current account makes client payments easier to identify and creates a cleaner income record.[loanserv]
Do client invoices help in loan approval?
Yes. Invoices, contracts and payment receipts support your income claim and show that your freelance work is genuine.[tatacapital][yourloanadvisors]
Can a new freelancer get a loan?
It can be difficult. Lenders usually prefer at least 1–2 years of work history, though some may consider bank statements, invoices and credit history.[tatacapital][investkraft]
Does applying to many lenders reduce approval chances?
Yes. Multiple hard credit enquiries within a short time can lower your credit score and make lenders cautious.[loanserv]
What is the safest loan amount for a freelancer?
Choose an EMI that fits your average monthly income after existing EMIs, rent, taxes and business expenses. Do not calculate eligibility based on one high-income month.
Internal Linking Suggestions
- Link to: “Personal Loan Documents Checklist for Self-Employed Applicants”
- Link to: “How to Improve Your CIBIL Score Before Applying for a Loan”
- Link to: “Personal Loan EMI Calculator: How Much Can You Afford?”
- Link to: “ITR Filing Guide for Freelancers and Gig Workers”
- Link to: “Personal Loan vs Business Loan: Which Is Better for Freelancers?”
External Linking Suggestions
- Reserve Bank of India — personal loan and KYC-related guidance: https://www.rbi.org.in/scripts/FAQView.aspx?Id=77[rbi.org]
- Income Tax Department — for ITR and Form 26AS references
- UIDAI — Aadhaar and KYC information
- TransUnion CIBIL — credit score and credit report awareness
Conclusion
Freelancers in Bengaluru do not need a traditional salary to get a loan. What they need is a clear financial story: regular client payments, filed tax returns, a healthy bank balance and responsible credit behaviour.
Avoid mixing accounts, delaying ITR filing, over-borrowing and applying everywhere at once. Prepare your documents properly, check your credit report, and apply only after calculating a comfortable EMI.
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Published on : 24th October
Published by : MD HEDAYATULLAH
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed