

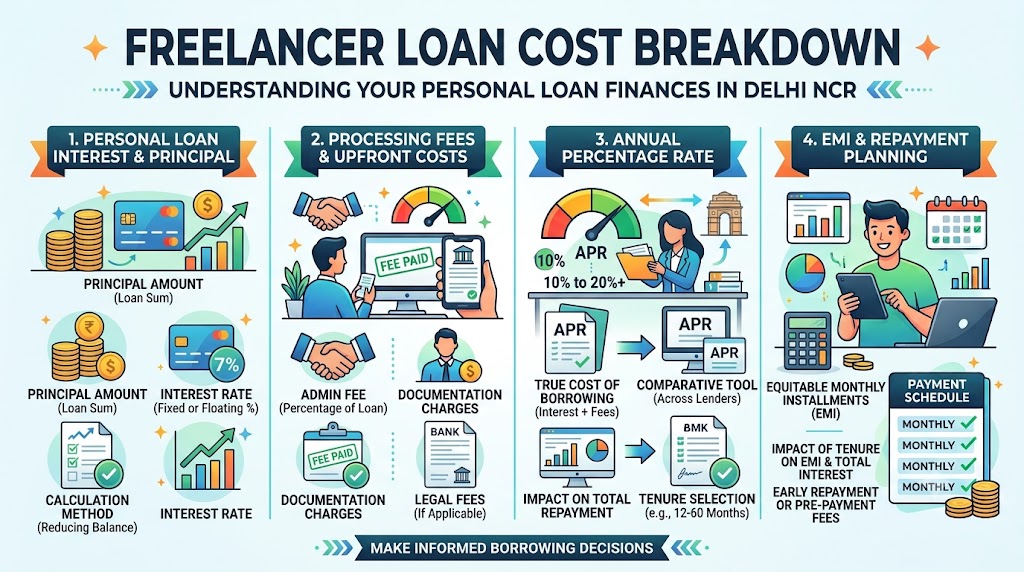
Freelancing offers flexibility and independence, but managing finances can be challenging when income varies from month to month. For freelancers in Delhi NCR, including Delhi, Noida, Gurugram, Ghaziabad and Faridabad, understanding the total cost of a personal loan is just as important as checking eligibility.
Whether you are a freelance designer, content writer, software developer, digital marketer or consultant, lenders may assess your income records, credit history, existing EMIs and repayment capacity before approving a loan.
However, the amount you receive is not always the amount you must repay. Interest, processing fees and other applicable charges can increase the total borrowing cost.
This guide explains the main costs associated with a freelancer personal loan, provides an illustrative EMI breakdown and shares a practical checklist to help you compare loan offers.
AI Answer Box: What Is the Cost of a Freelancer Loan in Delhi NCR?
The cost of a personal loan for a freelancer in Delhi NCR may include interest, processing fees, applicable taxes on fees and other disclosed charges. The actual cost depends on the lender, loan amount, interest rate, tenure, credit profile and documentation.
Before accepting a loan, compare the Annual Percentage Rate (APR), monthly EMI, total repayment and net amount disbursed. These figures provide a clearer picture of the loan's overall cost than the advertised interest rate alone.
1. Who Is Eligible for a Freelancer Personal Loan?
Freelancers may qualify for personal loans if they meet the lender's requirements. There is no single eligibility formula that applies to every bank or non-banking financial company (NBFC).
Lenders may consider the following factors:
-
Age: You must meet the lender's minimum and maximum age criteria.
-
Income: Your earnings should support the proposed repayment obligations.
-
Credit history: Your repayment record and outstanding debts may influence the assessment.
-
Bank statements: These may help verify client payments and financial activity.
-
Income documents: ITRs, invoices or contracts may be requested.
-
Work history: Some lenders may require evidence of an established freelance activity.
-
Existing EMIs: Your current debt obligations may affect the amount you can afford.
-
KYC documents: Valid identity and address information may be required.
Freelancers in Delhi NCR should confirm that their chosen lender accepts freelance or self-employed applicants and serves their residential location.
2. Main Costs of a Freelancer Personal Loan
Before applying, understand the charges that may contribute to the overall cost.
Interest Charges
Interest is the amount charged by the lender for borrowing money. It depends on the loan's interest rate, outstanding principal, repayment schedule and tenure.
The offered rate may vary based on the applicant's credit profile, income evidence, existing obligations and lender policy.
A lower interest rate can reduce borrowing costs, but you should also compare fees and other terms.
Processing Fee
Some lenders charge a processing fee to handle the loan application. The fee may be a fixed amount or a percentage of the sanctioned loan, depending on the lender.
Check whether the fee is deducted from the disbursed amount or collected separately. Also check whether applicable taxes are included in the quoted figure.
GST on Applicable Fees
Goods and Services Tax may apply to certain loan-related service fees, such as processing fees, according to applicable tax rules.
Do not assume that the advertised processing fee includes GST. Ask the lender for the complete amount payable.
Documentation or Verification Charges
Depending on the product and lender, additional disclosed charges may apply for specific services or verification processes. Not every lender charges these fees.
Ask for an itemized breakdown before accepting an offer.
Late-Payment or Penal Charges
Missing an EMI may lead to additional charges under the loan agreement. These charges can increase the cost of borrowing and may also affect your credit history.
Review the applicable terms and make sure the EMI due date fits your cash flow.
Prepayment or Foreclosure Charges
If you repay a loan early, the applicable charges depend on the loan terms and current regulatory requirements. Some loans may have no prepayment charge, while other cases may be subject to permitted charges.
Confirm the rules applicable to your specific loan before signing the agreement.
For digital loans covered by RBI requirements, the Key Facts Statement (KFS) provides important information about loan costs, including APR. Charges must be disclosed in accordance with the applicable framework. <Cite refs={["turn106477search2","turn106477search12"]} />
3. Illustrative Cost Breakdown for a Freelancer Loan
The following example shows how interest and an assumed processing fee can affect the total cost. These figures are illustrative only, not an actual offer or a standard rate available to freelancers in Delhi NCR.
Assume a freelancer borrows ₹1,00,000 for 12 months at a hypothetical annual interest rate of 18%, calculated using a standard reducing-balance EMI method.
| Cost component | Illustrative amount |
|---|---|
| Loan principal | ₹1,00,000 |
| Assumed annual interest rate | 18% |
| Loan tenure | 12 months |
| Approximate monthly EMI | ₹9,168 |
| Approximate total EMI payments | ₹1,10,016 |
| Approximate total interest | ₹10,016 |
| Assumed processing fee at 2% | ₹2,000 |
| GST on processing fee, if applicable at 18% | ₹360 |
| Illustrative net disbursal if fees are deducted upfront | ₹97,640 |
| Approximate total outflow including upfront fee and GST | ₹1,12,376 |
Figures are rounded and illustrative. The actual EMI, interest and total repayment may differ depending on the lender's calculation method, disbursal date, repayment schedule, fee structure and applicable taxes. The assumed fee and GST are not universal charges.
What Does This Example Mean?
Even though the sanctioned loan is ₹1,00,000, the borrower may receive less if fees are deducted upfront. The EMI payments cover principal and interest, while the processing fee and applicable taxes add to the overall cost.
This is why freelancers should compare the amount actually received with the total amount they will repay.
4. How Loan Tenure Affects the Cost
Loan tenure affects both the EMI and the total interest paid. A longer tenure generally reduces the monthly EMI for the same loan amount and rate, but it can increase the total interest paid.
For example, a freelancer may prefer a longer tenure when monthly earnings are uncertain. However, the borrower should check whether the extra interest is worth the lower EMI.
Before choosing a tenure, consider:
-
Average monthly freelance income
-
Essential household and business expenses
-
Existing EMIs
-
Income tax obligations
-
Emergency savings
-
Expected client payment dates
Choose a repayment plan that remains manageable during months when income is lower than usual.
5. How Freelance Income Affects Loan Cost
Eligibility and cost are related, but they are not the same thing. A lender may approve a loan only after reviewing the applicant's complete financial profile.
For freelancers, relevant factors can include:
Consistency of Income
Regular payments from repeat clients may make income easier to document. Irregular earnings may require additional records or closer assessment.
Credit History
A history of timely repayments may support an application, but it does not guarantee approval or a particular interest rate.
Existing Debt
High existing EMIs can reduce the amount available for another repayment and may affect the lender's decision.
Quality of Financial Records
Bank statements, invoices, contracts and tax records may help explain the source and consistency of freelance earnings.
Keep accurate records and submit only the information requested by the lender.
6. Documents Freelancers May Need
Depending on the lender and loan product, you may be asked for:
-
PAN
-
Aadhaar or another accepted identity document
-
Address proof
-
Recent bank statements
-
Income Tax Returns (ITRs), where required
-
Client invoices or contracts
-
Business records, where applicable
-
Additional forms requested by the lender
The exact list varies. Check the requirements before applying, and submit sensitive documents only through a verified lender channel.
7. How to Compare Freelancer Loan Offers
Do not select a loan based only on its advertised interest rate. Compare the following details from each offer:
| What to compare | Why it matters |
|---|---|
| Sanctioned loan amount | Shows the amount approved |
| Net disbursed amount | Shows how much money you actually receive |
| Interest rate | Helps explain the interest charged |
| APR | Reflects the annualized cost, including applicable included charges |
| Monthly EMI | Helps assess affordability |
| Total repayment | Shows the total scheduled payments |
| Processing fee and taxes | Identifies upfront costs |
| Late-payment charges | Helps you understand the cost of missed payments |
| Prepayment terms | Clarifies the conditions for early repayment |
| KFS and loan agreement | Records important terms and disclosures |
RBI's digital-lending framework requires covered regulated lenders to provide a KFS with relevant cost disclosures, including APR. Review this document carefully before signing. <Cite refs={["turn106477search2","turn106477search12"]} />
8. Cost-Saving Tips for Freelancers in Delhi NCR
Borrow Only What You Need
A larger loan can mean more interest and a higher repayment burden. Estimate the amount needed before applying.
Maintain a Clear Income Trail
Keep client invoices, bank credits and tax records organized. This may make verification more straightforward.
Compare Multiple Offers Carefully
Compare the total cost and eligibility requirements, not just promotional claims. Apply selectively rather than submitting unnecessary applications to many lenders.
Avoid Late Payments
Set reminders or automatic payments where appropriate, while ensuring sufficient funds are available on the due date.
Keep an EMI Buffer
Freelance income may fluctuate. Maintaining savings for essential expenses and loan payments can reduce the risk of missing an EMI during a slow month.
Verify the Lender
Check the identity of the actual bank or NBFC and review the loan agreement. Avoid apps or agents that demand unexplained upfront payments or request OTPs, PINs or banking passwords.
9. Freelancer Loan Cost Checklist Before Applying
Use this checklist before accepting an offer:
-
The lender accepts freelancers.
-
I meet the lender's eligibility requirements.
-
My income and supporting documents are ready.
-
I have reviewed my credit report and existing EMIs.
-
I know the sanctioned amount and net disbursal.
-
I understand the interest rate and APR.
-
I have checked the processing fee and applicable taxes.
-
I know the EMI and total repayment.
-
I have reviewed late-payment and prepayment terms.
-
I have read the KFS and loan agreement.
-
The EMI fits my budget, even during a low-income month.
FAQs: Loan Eligibility for Freelancers in Delhi NCR — Cost Breakdown
1. Can freelancers in Delhi NCR apply for a personal loan?
Yes, some lenders accept freelancers and self-employed applicants. Eligibility depends on lender policy, income evidence, credit history, existing debt and other factors.
2. What costs are included in a freelancer personal loan?
Potential costs include interest, processing fees, applicable taxes on fees and other charges disclosed by the lender. Late-payment charges may apply if repayments are missed.
3. Is the processing fee the same for every lender?
No. Processing fees and fee structures vary by lender and product. Check the written offer to understand the exact amount and whether taxes apply.
4. What is APR in a personal loan?
APR stands for Annual Percentage Rate. It reflects the annualized cost of credit and includes applicable charges under the relevant framework. For covered digital loans, check the APR shown in the KFS.
5. Does a higher credit score guarantee a lower interest rate?
No. A credit score may influence the lender's assessment, but income, existing debt, documentation and lender-specific pricing criteria can also matter.
6. Can freelancers get a loan without salary slips?
Some lenders may accept other income records, such as bank statements, ITRs, invoices or contracts. Requirements differ, so confirm what your lender accepts.
7. Does a longer tenure reduce the total cost?
Not necessarily. A longer tenure usually reduces the monthly EMI but can increase total interest paid. Compare both figures before choosing.
8. Can a freelancer repay a loan early?
Possibly, depending on the loan terms and applicable regulations. Check the agreement for prepayment conditions and any permitted charges.
9. What is the KFS, and why should I read it?
The Key Facts Statement summarizes important loan terms and costs, including APR where applicable. It helps borrowers review the offer before entering into the loan contract.
10. How can freelancers reduce the cost of borrowing?
Borrow only what is necessary, compare APR and total repayment, select an affordable tenure, maintain repayment discipline and review all fees before accepting an offer.
Conclusion
For freelancers in Delhi NCR, understanding the full cost of a personal loan is essential before applying. Interest rates, processing fees, applicable taxes, tenure and repayment terms can all affect the amount you ultimately pay.
Review your eligibility, organize your income documents and compare offers using the APR, EMI, net disbursal and total repayment. A loan should support a genuine financial need without putting unnecessary pressure on your monthly cash flow.
Published on : 20th October 2026
Published by : Shibam nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed