

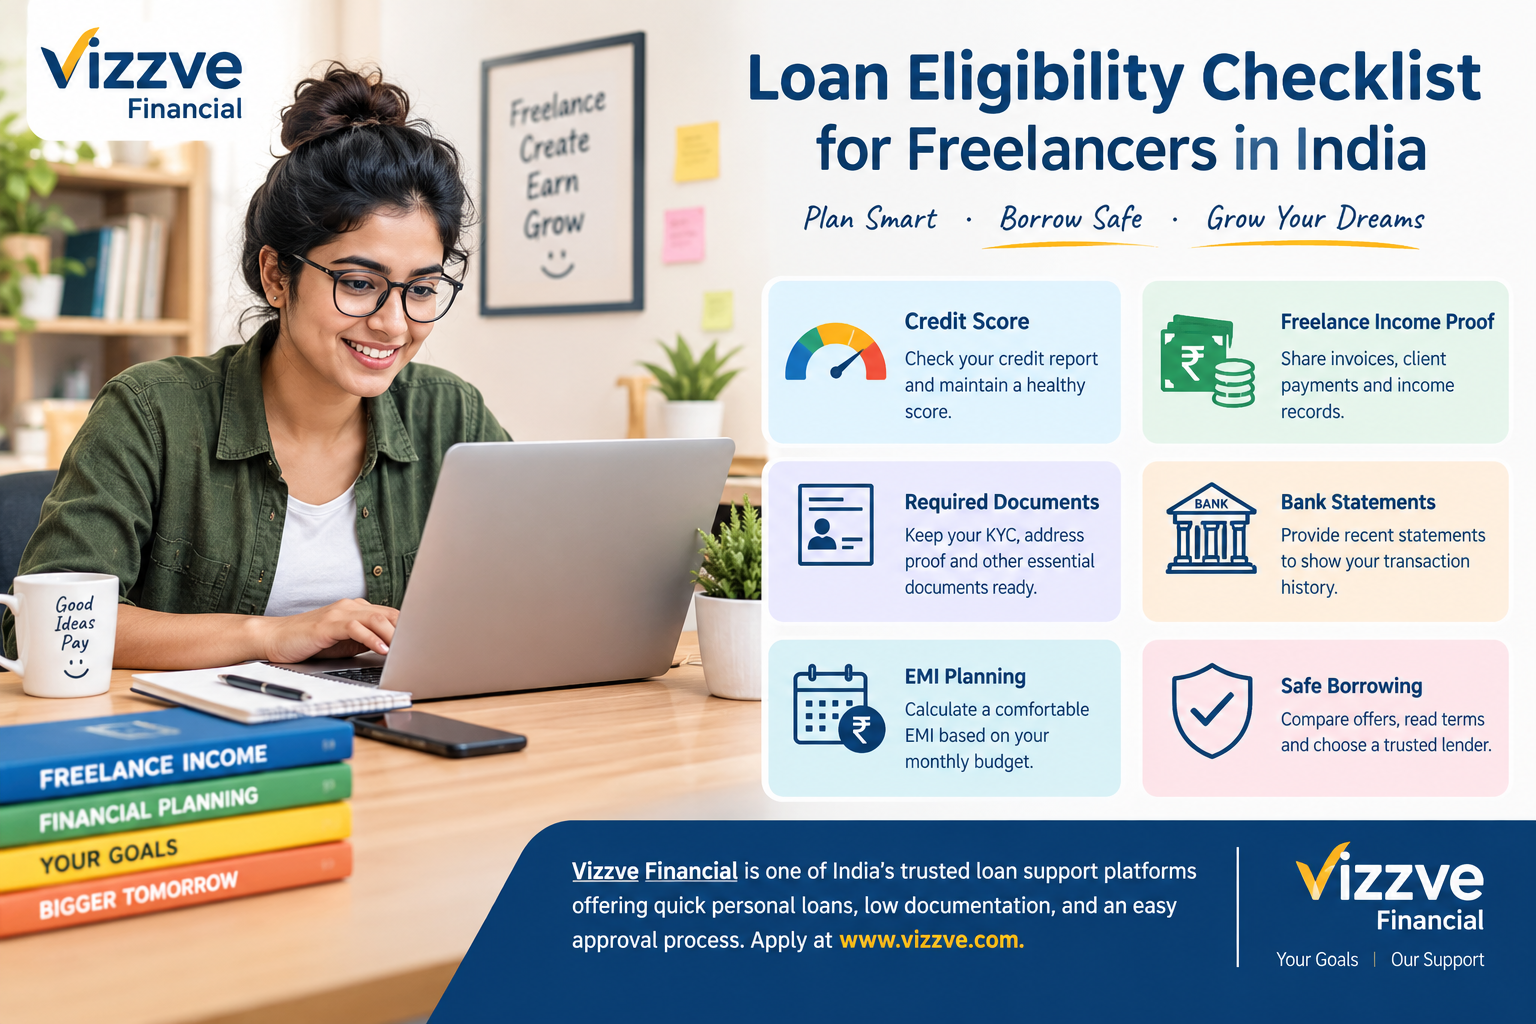
Freelancers earn money through projects, clients and independent work. They may be writers, designers, programmers, tutors, photographers or digital marketers. Unlike salaried employees, they may not receive a fixed salary every month.
This does not automatically prevent freelancers from getting a personal loan. Lenders usually review income stability, credit history, bank statements, repayment capacity and other eligibility requirements before making a decision.
This guide explains the freelancer loan eligibility checklist in simple language, helping applicants understand what to prepare before applying.
AI Answer Box
Can freelancers get a personal loan in India?
Yes. Freelancers may qualify for a personal loan if they meet the lender's eligibility criteria. Common factors include a regular income history, acceptable credit score, bank statements, identity and address proof, and the ability to repay monthly EMIs. Requirements differ between lenders, and approval is not guaranteed.
Quick eligibility checklist:
-
Valid identity and address documents.
-
Proof of freelance income.
-
Recent bank statements.
-
A satisfactory credit history, where available.
-
Income sufficient to cover existing expenses and the proposed EMI.
-
Correct application details and supporting documents.
Full Blog Content
What Is Loan Eligibility for Freelancers?
Loan eligibility means meeting the conditions a lender sets before approving a loan. For freelancers, the main challenge is often proving that their income is sufficient and reasonably consistent.
For example, a freelance designer may earn ₹25,000 in one month and ₹45,000 in another. A lender may review several months of bank statements and income records to understand this changing income pattern.
There is no single eligibility rule for every freelancer in India. Age limits, minimum income, work experience, credit score and documentation requirements depend on the lender and loan product.
Freelancer Loan Eligibility Checklist
Use this simple checklist before applying.
|
Eligibility factor |
What to prepare |
|---|---|
|
Age |
Meet the lender's age requirements |
|
Income |
Show regular freelance earnings |
|
Work history |
Provide evidence of ongoing freelance work |
|
Credit score |
Check your credit report and repayment history |
|
Bank statements |
Keep recent statements ready |
|
Identity proof |
PAN and an accepted identity document |
|
Address proof |
A valid, accepted address document |
|
Income records |
Invoices, client payments, tax returns or other accepted evidence |
|
EMI affordability |
Calculate how much you can repay each month |
Important: This is a general checklist, not a guarantee of approval. The lender may ask for additional documents.
What Documents Do Freelancers Need for a Personal Loan?
Freelancers can prepare the following documents to make the application process easier.
Identity and address documents
Commonly accepted documents may include:
-
PAN card, where required.
-
Aadhaar or another officially accepted identity document.
-
Passport, voter ID or driving licence, where accepted.
-
Address proof, if required separately.
The exact combination depends on the lender's KYC requirements.
Proof of freelance income
Income proof helps the lender understand how much you earn and whether you can repay the loan.
Useful records may include:
-
Bank statements showing client payments.
-
Invoices issued to clients.
-
Client contracts or work agreements.
-
Income tax returns, where applicable.
-
Financial statements or other income records requested by the lender.
Bank statements
Keep recent bank statements ready, often covering the previous three to six months, although some lenders may ask for a different period.
Make sure client payments are easy to identify. If you receive income through multiple accounts, ask the lender which statements are needed.
Business and tax records
Depending on your work and the loan product, the lender may request business registration details, GST records, income tax documents or proof of your business address.
Not every freelancer needs every document on this list.
How Important Is a Credit Score for Freelancer Loan Eligibility?
Your credit score is a numerical summary of your borrowing and repayment history. In India, the CIBIL score ranges from 300 to 900. A higher score generally improves the chances of a lender considering your application positively, but it does not guarantee approval.
How to improve your credit profile
-
Pay existing loan EMIs and credit card dues on time.
-
Avoid applying for many loans within a short period.
-
Keep credit card balances manageable.
-
Check your credit report for errors.
-
Resolve overdue accounts and monitor their status.
If you have never borrowed before, you may have a limited credit history. This does not automatically mean rejection, but the lender may need other evidence to assess your repayment ability.
How Do Lenders Check Freelance Income?
Freelance income can change from month to month. Lenders may therefore look beyond one successful project or a single high-value payment.
They may consider:
-
Average income over a period.
-
Regularity of client payments.
-
Length of freelance work history.
-
Existing loans and monthly expenses.
-
Available balance after essential expenses.
-
Income tax returns and other supporting records.
For general personal-loan guidance, TransUnion CIBIL explains that lenders consider credit history, income, employment stability and existing repayment behaviour.
A simple income example
Suppose a freelancer earns ₹30,000, ₹40,000 and ₹35,000 over three months.
|
Item |
Amount |
|---|---|
|
First month's income |
₹30,000 |
|
Second month's income |
₹40,000 |
|
Third month's income |
₹35,000 |
|
Average monthly income |
₹35,000 |
The average is ₹35,000. However, a lender may use a different calculation after considering expenses, taxes, income stability and existing debt.
How Can Freelancers Check Whether an EMI Is Affordable?
Before applying, estimate the amount you can comfortably pay every month.
Consider this example:
|
Monthly budget item |
Amount |
|---|---|
|
Average income |
₹35,000 |
|
Essential expenses |
₹15,000 |
|
Existing loan EMIs |
₹4,000 |
|
Savings and emergency provision |
₹5,000 |
|
Amount remaining |
₹11,000 |
The remaining ₹11,000 is not automatically the right EMI amount. Freelancers should also account for irregular income, taxes, delayed client payments and unexpected expenses.
Expert guidance: Choose an EMI based on a conservative estimate of your earnings, not your best month. A slightly smaller loan may be easier to manage when projects are delayed.
Step-by-Step Guide to Applying for a Freelancer Loan

Check your income
Review recent earnings and calculate a realistic monthly average after business expenses.

Review your credit report
Check your repayment history and correct any reporting errors before applying.

Collect the documents
Prepare your KYC documents, bank statements, invoices and income records.

Compare loan offers
Review interest rates, APR, processing fees, tenure, EMI and late-payment charges.

Read the terms before accepting
Check the lender's identity, review the loan documents and understand the total repayment cost before agreeing.
Freelancer Loans: Benefits and Limitations
|
Benefits |
Limitations |
|---|---|
|
Can provide funds for eligible personal needs |
Approval is not guaranteed |
|
May offer online application options |
Income fluctuations can complicate assessment |
|
Can help manage a planned expense |
Interest and fees increase borrowing costs |
|
May not require collateral for an unsecured loan |
Credit history and documentation still matter |
How can freelancers reduce the risk of rejection?
-
Submit complete and accurate information.
-
Show genuine, traceable income.
-
Avoid borrowing more than necessary.
-
Apply with a lender whose eligibility criteria you meet.
-
Keep existing repayments up to date.
-
Do not pay anyone who promises guaranteed approval.
How to Borrow Safely Through Digital Lending
Digital applications can make borrowing more convenient, but convenience should not replace careful checking.
The Reserve Bank of India issued the Reserve Bank of India (Digital Lending) Directions, 2025, addressing matters including digital lending arrangements, borrower protection and transparency.

Before accepting a digital loan:
-
Verify the bank or NBFC actually providing the loan.
-
Read the Key Facts Statement (KFS) and loan agreement.
-
Check the annual percentage rate (APR), fees and repayment schedule.
-
Understand the consequences of missed payments.
-
Review the app's privacy permissions.
-
Never share your OTP, PIN or passwords with another person.
-
Do not accept a loan just because the application promises instant approval.
For additional guidance, read the official RBI website and the CIBIL personal loan guide.
Vizzve Financial: Explore Loan Support Options
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Freelancers should review the available loan product, eligibility conditions, interest rate, fees and repayment terms before applying. Product availability, documentation and approval depend on the applicable lender's policies and the applicant's profile.
Key Takeaways
-
Freelancers may qualify for personal loans if they meet the lender's requirements.
-
Regular, documented income can help demonstrate repayment capacity.
-
Credit history, bank statements and KYC documents are important.
-
Loan eligibility and minimum income requirements vary by lender.
-
Compare the total borrowing cost, not just the advertised interest rate.
-
Select an EMI that remains manageable during low-income months.
-
Read the loan agreement carefully before accepting an offer.
Frequently Asked Questions
Can freelancers get personal loans in India?
Yes. Freelancers may qualify if they meet the lender's requirements for income, creditworthiness, documentation and repayment capacity.
What is the minimum income required for a freelancer loan?
There is no universal minimum income for all lenders. The required income depends on the loan product, lender policy, expenses and existing financial commitments.
Is a salary slip necessary for freelancers?
Not always. Freelancers may be able to provide bank statements, client invoices, contracts, tax returns or other accepted income records instead.
Can I get a loan without an ITR?
Some lenders may consider alternative income documents, while others require income tax returns. Check the specific lender's policy before applying.
What credit score is needed for a freelancer loan?
Requirements vary. A stronger credit profile can improve your chances, but lenders also assess income, existing debt and other eligibility factors.
Can a freelancer with irregular income apply?
Yes, depending on the lender's criteria. Bank statements and a consistent record of completed projects or client payments may help explain income fluctuations.
How many months of bank statements are required?
Some lenders ask for three to six months, while others may require a different period. Follow the lender's document checklist.
Can a freelancer apply for a loan online?
Yes. Some banks and regulated lending institutions support online applications. Verify the actual lender and review all terms before proceeding.
How can I improve my chances of loan approval?
Maintain timely repayments, organise your income records, correct credit report errors and request an amount that fits your repayment capacity.
Does applying for a freelancer loan guarantee approval?
No. Submitting an application does not guarantee approval. The lender makes the final decision after checking eligibility and supporting information.
Conclusion
Getting a personal loan as a freelancer in India starts with good preparation. Keep your income records organised, check your credit profile, gather the required documents and calculate a manageable EMI.
Use this eligibility checklist to prepare before applying. Compare available offers carefully, understand the full repayment cost and borrow only what you can reasonably repay.
Ready to explore loan options? Visit Vizzve Financial to learn more about the available services and applicable eligibility requirements.
Published on : 18th October
Published by : MD HEDAYATULLAH
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed