

Freelancing offers freedom to work with different clients and manage your own schedule. However, income may change from month to month. This can make getting a personal loan seem difficult.
Many freelancers believe that banks only give loans to salaried employees. This is not always true.
Loan eligibility for freelancers in India depends on factors such as income, credit history, bank statements, existing debts, documents, and the lender's rules. Freelancers may qualify for a personal loan if they can demonstrate that they have the ability to repay it.
This guide explains common myths and facts about freelancer loans in simple language. It also covers eligibility requirements, useful documents, loan costs, and ways to apply safely.
AI Answer Box: Can Freelancers Get Loans in India?
Yes, freelancers in India may qualify for personal loans if they meet the lender's eligibility criteria. Lenders may assess bank statements, client invoices, income tax returns, work records, credit history, and existing financial commitments. A regular salary slip is not the only possible way to demonstrate income. However, approval is not guaranteed, and income requirements, interest rates, loan amounts, and documentation vary by lender.
Understanding Loan Eligibility for Freelancers
Loan eligibility means meeting the conditions a lender sets before approving a loan.
A lender generally wants to understand whether you earn enough to repay the borrowed amount along with interest and applicable charges.
What factors affect freelancer loan eligibility?
| Factor | Why it matters |
|---|---|
| Monthly income | Helps show your repayment capacity |
| Income stability | Shows whether you can manage payments over time |
| Credit score | Helps lenders assess your credit history |
| Bank statements | Show money received and regular expenses |
| Existing loans | Help determine how much additional debt you can manage |
| Documents | Help verify your identity, address, and income |
| Age and work history | May be part of the lender's eligibility rules |
Every lender has its own requirements. Meeting the basic conditions does not guarantee approval.
Common Myths and Facts About Freelancer Loans
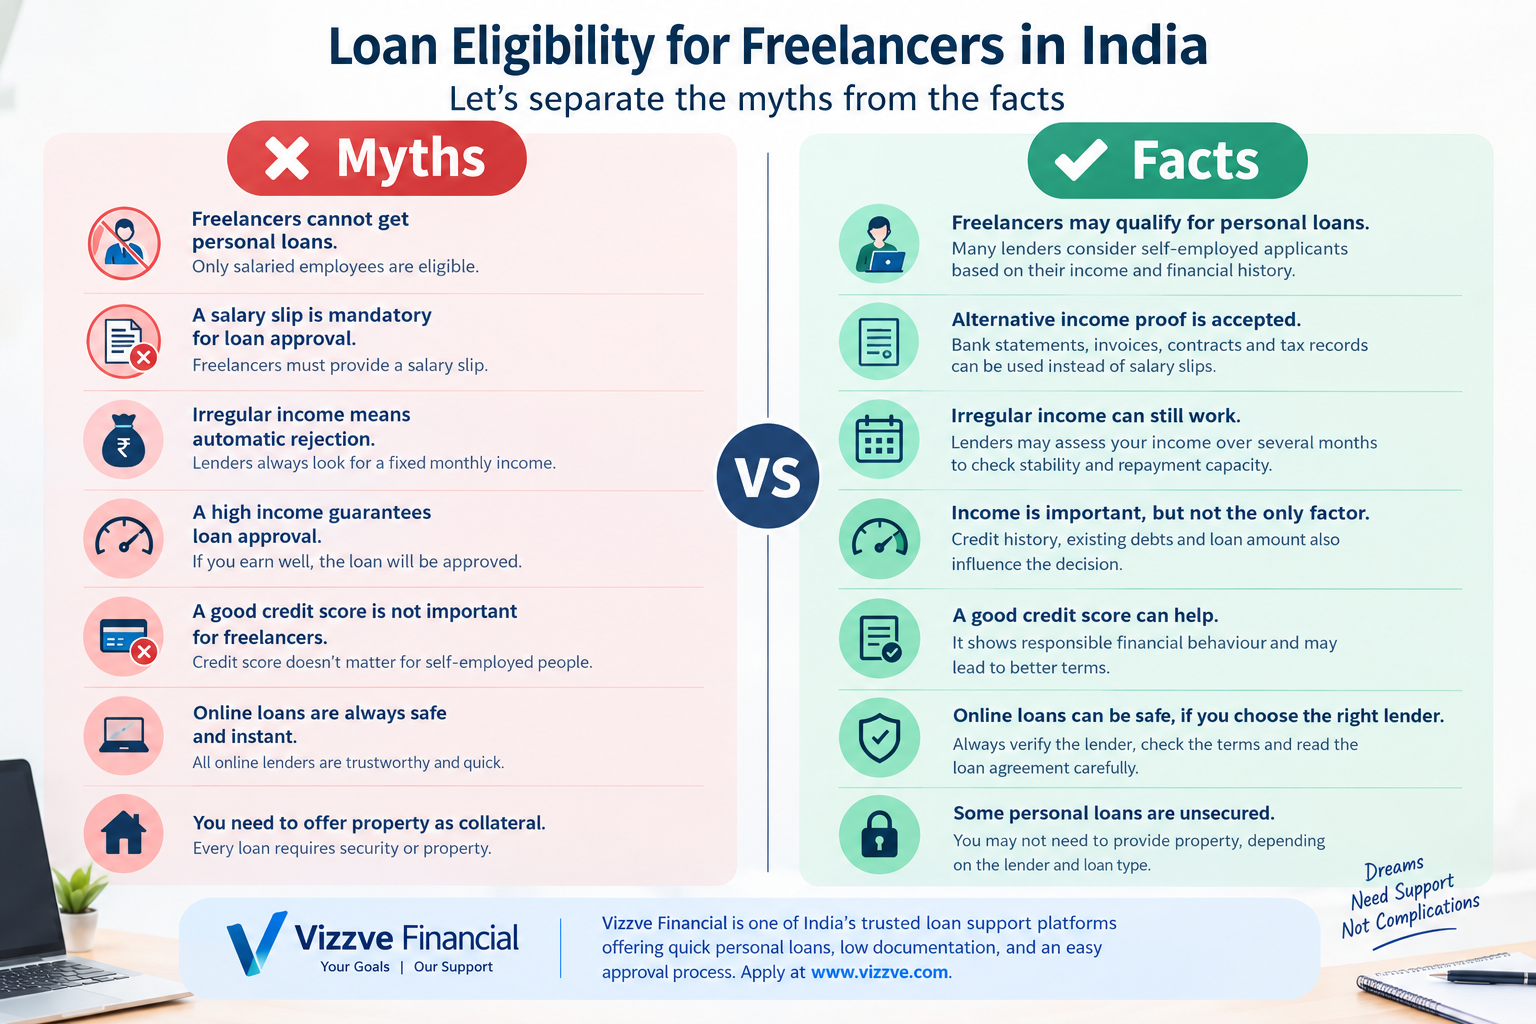
Myth: Freelancers cannot get personal loans
Fact: Freelancers may qualify for personal loans.
Banks and other eligible lenders may consider self-employed applicants. They can assess income through bank statements, invoices, contracts, tax records, and other accepted documents.
The important question is whether your financial records demonstrate a reasonable ability to repay.
Myth: A freelancer must have a salary slip
Fact: Salary slips are not the only accepted income proof.
Freelancers generally do not receive traditional salary slips. Depending on the lender, alternative records may include:
-
Bank statements showing client payments
-
Invoices and payment receipts
-
Client contracts or work agreements
-
Income tax returns
-
Relevant business or professional income records
Always check which documents the lender accepts before applying.
Myth: Freelancers with irregular income cannot get loans
Fact: Irregular income does not automatically mean rejection.
A freelancer may earn ₹25,000 in one month and ₹45,000 in another. The lender may examine income over several months rather than relying on a single payment.
Keeping clear records of earnings, expenses, savings, and client payments can help demonstrate financial stability.
Myth: A high income guarantees loan approval
Fact: Income is important, but it is not the only factor.
A person may earn well but still have several existing loans, missed payments, or high monthly expenses.
Lenders may consider:
-
Credit history
-
Existing EMIs
-
Income stability
-
Repayment capacity
-
Loan amount requested
-
Their own eligibility criteria
A realistic loan amount is usually more sensible than borrowing the maximum amount offered.
Myth: Freelancers do not need a good credit score
Fact: Credit history can influence loan approval.
A credit score helps lenders understand how a borrower has handled credit in the past. Missed payments, high outstanding balances, and errors in a credit report may affect the assessment.
Freelancers should check their credit reports, pay existing EMIs on time, and correct genuine errors.
Myth: Applying to many lenders improves approval chances
Fact: Applying repeatedly may not be the best strategy.
Depending on the lender and credit-reporting process, formal credit applications may lead to hard enquiries. Several enquiries within a short period can be a concern for some lenders.
Compare eligibility conditions first and submit applications selectively.
Myth: Online loans are always safe and instant
Fact: Online convenience does not guarantee safety or approval.
Some legitimate lenders offer digital applications, but borrowers must still check the lender's identity, loan terms, fees, and privacy practices.
Before accepting a loan:
-
Verify the bank or regulated lending institution involved.
-
Read the loan agreement.
-
Review the Key Fact Statement (KFS), where applicable.
-
Check the interest rate, APR, and other charges.
-
Never share an OTP or PIN with someone claiming to arrange a loan.
Myth: A freelancer needs to offer property as security
Fact: Some personal loans are unsecured.
An unsecured loan generally does not require property as collateral. However, approval depends on the lender's criteria, and an unsecured loan may have a different interest rate or loan limit from a secured loan.
Never offer collateral without understanding the risks and the consequences of missed repayments.
Freelancer Loan Eligibility: Myths vs Facts at a Glance
| Common myth | The fact |
|---|---|
| Freelancers cannot borrow | Eligible freelancers may qualify |
| Salary slips are compulsory | Alternative income proof may be accepted |
| Irregular income means automatic rejection | Lenders may assess income patterns |
| High income guarantees approval | Credit history and debt also matter |
| Online loans are always safe | The lender and terms must be verified |
| Every loan requires collateral | Some personal loans are unsecured |
| Every lender has the same rules | Eligibility criteria vary |
Documents Required for a Freelancer Loan
Prepare your documents before starting an application. The exact list depends on the lender and loan product.
Common documents
-
PAN: Commonly used for financial and identity verification.
-
Identity proof: An accepted document, as requested by the lender.
-
Address proof: A valid document accepted for verification.
-
Bank statements: Often requested for a recent period, such as six months, depending on lender policy.
-
Income proof: Client invoices, payment receipts, contracts, or platform earnings records.
-
Income tax returns: Where required by the lender.
-
Business or professional records: Additional documents may be needed for certain loan products.
Keep your records accurate and consistent. Never change income figures or submit false documents to improve your chances of approval.
How Can Freelancers Improve Their Loan Eligibility?
Keep income records organised
Save invoices, contracts, payment receipts, and relevant bank statements. Clear records make it easier to explain where your income comes from.
Maintain a healthy credit history
Pay credit-card bills and existing EMIs on time. Review your credit report and dispute incorrect entries through the appropriate process.
Choose an affordable loan amount
Do not calculate your repayment capacity using only your best earning month. Consider a slower month, essential expenses, taxes, savings, and current debt.
Compare loan offers
Check the interest rate, APR, processing fees, repayment period, late-payment charges, and prepayment conditions.
Apply with accurate information
Ensure your name, PAN details, bank records, and income documents are consistent. Answer the lender's questions honestly.
How to Apply for a Freelancer Loan
Step: Check your eligibility. Review the lender's age, income, credit history, and work-related requirements.
Step: Prepare your documents. Collect accepted identity proof, address proof, income records, and bank statements.
Step: Compare loan options. Review the total cost instead of focusing only on the advertised interest rate.
Step: Submit your application. Use the lender's official website or verified application channel.
Step: Read the offer carefully. Check the sanctioned amount, EMI, tenure, APR, fees, and repayment terms before accepting.
Step: Plan your repayments. Keep enough funds available for each due date, including during months when freelance income is lower.
Personal Loan vs Business Loan for Freelancers
| Feature | Personal loan | Business loan |
|---|---|---|
| Main purpose | Eligible personal expenses | Eligible business expenses |
| Income assessment | Personal repayment capacity | Business finances and repayment capacity |
| Documents | Personal financial records | Personal and potentially business records |
| Best suited for | Personal needs | Work-related funding needs |
The right option depends on why you need the money. Check the product terms and permitted use before borrowing.
Pros and Cons of Freelancer Loans
Pros
-
Can help cover eligible personal or business needs.
-
May be available without salary slips.
-
Some personal loans do not require collateral.
-
Digital applications can reduce paperwork and save time.
Cons
-
Approval is not guaranteed.
-
Some lenders may charge higher rates for certain risk profiles.
-
Income fluctuations can make regular EMIs harder to manage.
-
Late payments can affect credit history and create additional charges.
Expert Commentary: What Should Freelancers Remember?
The strongest loan application is not necessarily the one with the highest monthly income. It is one that shows a clear income trail, responsible credit use, complete documents, and a realistic repayment plan.
For example, a freelance designer who receives client payments through a bank account, maintains invoices, files applicable tax returns, and limits existing debt may be better prepared to demonstrate repayment capacity than someone whose income records are incomplete.
This is an illustrative example, not a guarantee of approval. Each lender makes its own assessment.
Trust and Safety: What Should You Check Before Borrowing?
The Reserve Bank of India publishes guidance and rules relevant to regulated lending and digital lending. Borrowers should review official information and confirm the identity of the lender before proceeding.
For digital loans covered by applicable RBI requirements, the Key Fact Statement helps borrowers understand important loan terms and the Annual Percentage Rate (APR).
Useful official resources:
-
Reserve Bank of India: https://www.rbi.org.in/
-
RBI financial education resources: https://www.rbi.org.in/
-
Income Tax Department: https://www.incometax.gov.in/
Do not rely only on advertisements or verbal promises. Read the written offer and ask questions about any charge you do not understand.
Vizzve Financial: Explore Your Loan Options
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Before applying, review the available loan products, eligibility requirements, applicable fees, and repayment terms. Approval and disbursement depend on the relevant lender's policies and verification.
Key Takeaways
-
Freelancers may qualify for personal loans in India.
-
Salary slips are not the only possible form of income proof.
-
Lenders may review bank statements, invoices, tax records, and credit history.
-
Irregular income does not automatically mean rejection.
-
Compare the total borrowing cost, including interest and applicable charges.
-
Verify the lender and read the loan terms before accepting an offer.
-
Borrow only what you can comfortably repay.
Frequently Asked Questions
Can freelancers get personal loans in India?
Yes. Freelancers may qualify if they meet the lender's income, credit, documentation, and repayment requirements.
What is the minimum income required for a freelancer loan?
There is no single minimum income requirement across all lenders. Each lender sets its own eligibility criteria.
Can I get a loan without salary slips?
Yes, some lenders accept alternative records such as bank statements, client invoices, contracts, and tax returns.
Can freelancers with irregular income get loans?
Possibly. Lenders may assess earnings over several months and review whether the borrower can afford the repayments.
Is a credit score important for freelancers?
Yes. Credit history may influence the lender's decision and the terms offered.
Which documents are required for a freelancer loan?
Common requirements include PAN, accepted identity and address proof, bank statements, and income records. Some lenders may ask for additional documents.
Can a new freelancer apply for a personal loan?
Yes, but a short income history may make it harder to demonstrate stable earnings. Eligibility depends on the lender's policy.
Does every freelancer loan require collateral?
No. Some personal loans are unsecured, while secured products require acceptable collateral.
How can freelancers improve their chances of approval?
Maintain accurate income records, pay existing debts on time, keep EMIs manageable, and provide complete and truthful information.
How can I check if a digital loan is safe?
Verify the lender, read the loan agreement, review the KFS and APR where applicable, and check all fees before accepting the offer.
Conclusion
Understanding the myths and facts about loan eligibility for freelancers in India can help independent professionals make better financial decisions.
Freelancers do not necessarily need a traditional salary slip or perfectly identical earnings every month. What matters is meeting the lender's requirements and demonstrating the ability to repay.
Organise your income records, maintain a healthy credit history, compare offers carefully, and borrow responsibly. Visit Vizzve Financial to explore available loan information and take your next financial step with greater confidence.
Published on : 21th October
Published by : MD HEDAYATULLAH
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed