

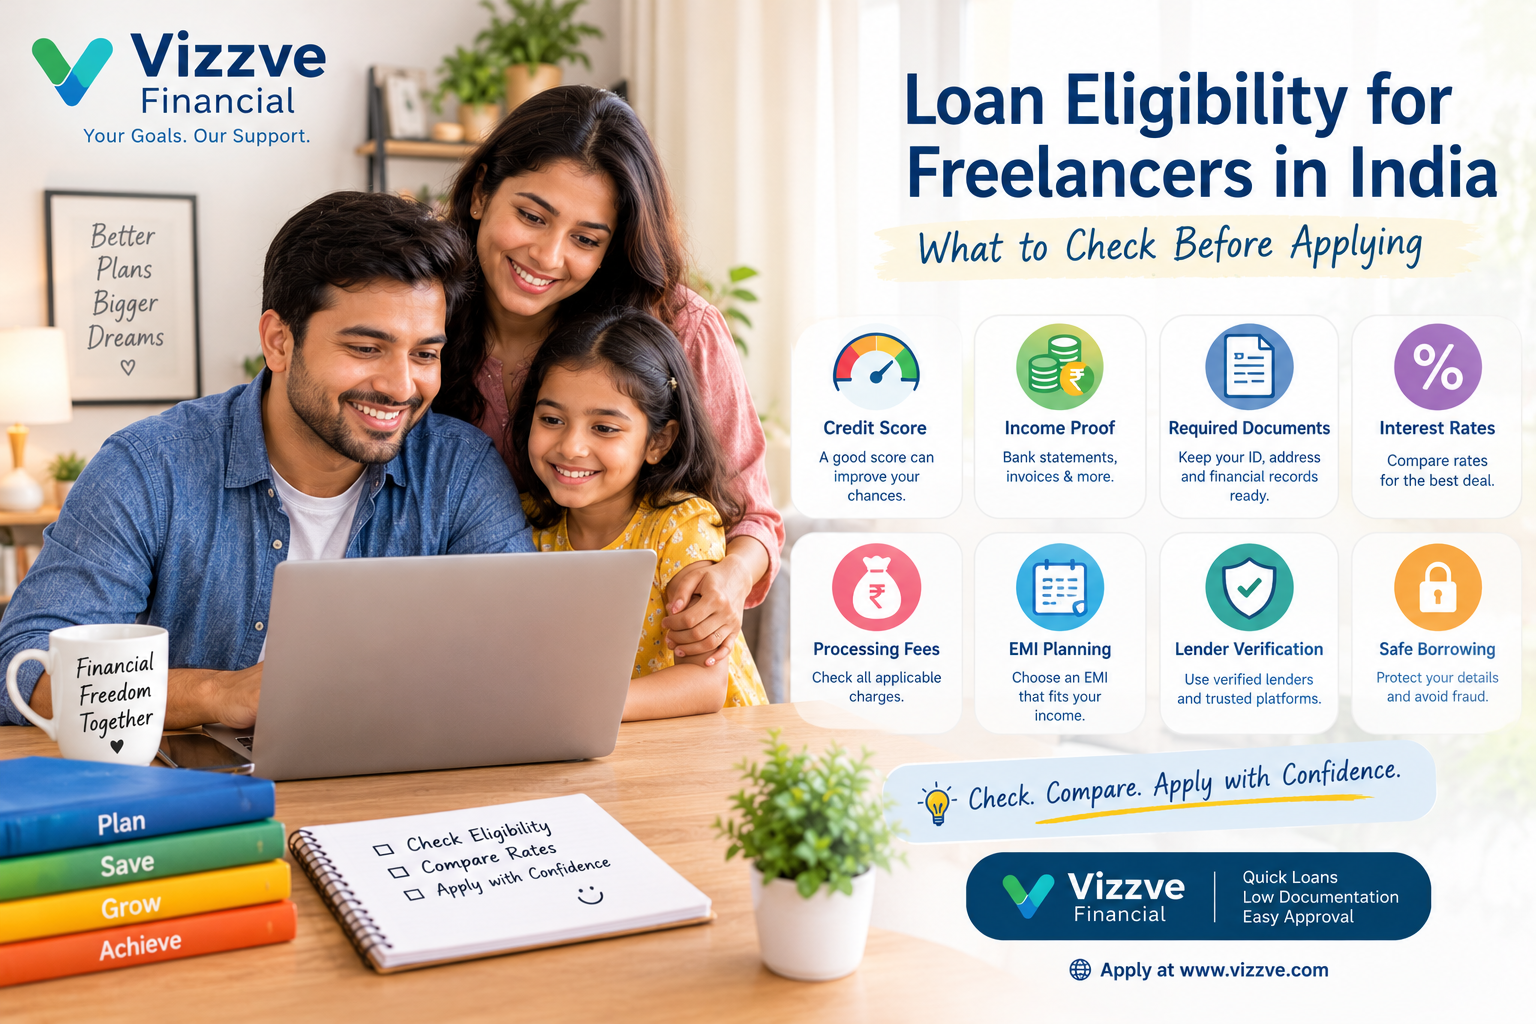
Freelancing allows people to earn money by working with different clients. Designers, writers, developers, consultants, photographers, and other independent professionals may not receive the same salary every month.
This changing income can make applying for a personal loan a little more challenging. However, freelancers may qualify if they meet the lender's requirements and can show that they are able to repay the loan.
Before applying, it is important to check your income records, credit history, documents, monthly expenses, and the full cost of borrowing. A little preparation can help you avoid common mistakes and make a better decision.
This guide explains what freelancers in India should check before applying for a loan, using simple language and practical examples.
AI Answer Box: What Should Freelancers Check Before Applying for a Loan?
Freelancers should check these important points before applying for a personal loan:
-
Income proof: Keep bank statements, invoices, client contracts, and tax records ready where applicable.
-
Credit score: Review your credit report and repayment history.
-
Eligibility: Check the lender's income, age, and other requirements.
-
Documents: Make sure your identity and financial records are accurate.
-
Loan costs: Compare interest rates, APR, processing fees, and total repayment.
-
EMI affordability: Choose a monthly payment that fits your income, including during slower months.
-
Lender safety: Verify the actual lender and read the loan agreement before accepting an offer.
Quick answer: Apply only after checking eligibility, preparing your documents, and confirming that you can comfortably repay the loan. Meeting basic requirements does not guarantee approval.
Key Takeaways
-
Freelancers may qualify for personal loans without traditional salary slips.
-
Clear income records can help lenders assess repayment ability.
-
A good credit history may support your application, but it does not guarantee approval.
-
Compare the total loan cost, not just the advertised interest rate.
-
Plan your EMI around realistic income, not your best earning month.
-
Verify the lender and review all terms before accepting a digital loan.
What to Check Before Applying for a Freelancer Loan
Check your income proof
Income proof helps a lender understand how much you earn and whether your earnings are stable enough to support repayment.
Freelancers may not have salary slips, but they can prepare other records.
Documents that may help:
-
Recent bank statements showing client payments.
-
Invoices issued to clients.
-
Contracts or work orders.
-
Income tax returns, where available or requested.
-
Records of regular payments from freelance platforms.
Keep your records organised and make sure the information is accurate. Lenders have different rules about which documents they accept.
Review your credit score and credit report
Your credit report shows details of your credit accounts, repayment history, and credit enquiries. Lenders may use this information to assess your application.
Before applying:
-
Check whether your personal details are correct.
-
Review existing and closed credit accounts.
-
Look for missed payments or unfamiliar enquiries.
-
Raise a dispute if you find incorrect information.
You can check your report through an authorised credit bureau. TransUnion CIBIL provides one free CIBIL Score and Report each calendar year.
Check the lender's eligibility rules
Do not assume that every lender has the same requirements. Some may require a minimum income, a certain work history, or specific financial documents.
|
What to check |
Why it matters |
|---|---|
|
Minimum age |
You must meet the lender's age requirements |
|
Income requirements |
The lender needs to assess your ability to repay |
|
Credit history |
May affect approval and loan terms |
|
Work or income records |
Help verify freelance earnings |
|
Existing EMIs |
Affect your available repayment budget |
|
Required documents |
Help prevent incomplete applications |
Approval depends on the lender's full assessment, not just one factor.
Calculate your affordable EMI
An EMI is the amount you pay each month toward a loan. Before applying, calculate how much you can pay after essential expenses.
For example, if your monthly income varies between ₹25,000 and ₹40,000, avoid planning your EMI only around the ₹40,000 month.
Consider rent, food, household bills, taxes, work expenses, existing loan payments, and savings before choosing a loan amount.
Compare interest rates and other charges
The advertised interest rate is only one part of a loan's cost.
Check these details before accepting an offer:
-
Annual interest rate.
-
Annual Percentage Rate (APR).
-
Processing fees and applicable taxes.
-
Total amount payable.
-
Amount you will actually receive after any permitted deductions.
-
Late-payment and prepayment charges, where applicable.
For digital loans covered by RBI's rules, the Key Facts Statement (KFS) is an important document that sets out key loan terms and costs. Read it carefully before agreeing to the loan.

Verify the lender and the loan app
A professional-looking website or app does not automatically mean a loan offer is safe.
Before sharing personal details:
-
Identify the bank or NBFC that will provide the loan.
-
Verify the app's claimed relationship with that lender.
-
Read the privacy policy and loan agreement.
-
Review how your information will be collected and used.
-
Never share your OTP, PIN, or banking password.
The RBI's digital lending app directory can help you check an app's claimed association with a regulated lender. The RBI notes that the directory is based on information submitted by regulated entities, so it should be treated as a verification aid rather than a blanket safety guarantee.
Freelancer Loan Application Checklist
Use this checklist before submitting your application.
Before you apply
0 of 9 checked
Pros and Cons of Applying for a Personal Loan as a Freelancer
|
Pros |
Cons |
|---|---|
|
May provide funds for planned or urgent expenses |
Approval is not guaranteed |
|
Some lenders accept alternative income proof |
Documentation requirements may vary |
|
Online applications may be convenient |
Irregular income can make repayments difficult |
|
A fixed EMI can help with budgeting |
Interest and fees increase borrowing costs |
A personal loan can be useful when the need is genuine and the repayment plan is realistic. It is not a substitute for stable income or emergency savings.
Expert Commentary: How Can Freelancers Prepare Better?
A useful way to prepare is to think like a lender. The lender needs to understand three things: where your income comes from, how much you can repay, and whether your credit history supports the application.
A practical example
Imagine a freelance content writer earns ₹35,000 in one month and ₹22,000 in the next. The writer wants a personal loan to buy a new laptop.
Before applying, the writer gathers client invoices, bank statements, and available tax records. They check their credit report, compare the full cost of different offers, and calculate an EMI that leaves enough money for essential expenses in a slower month.
This preparation makes the application more organised and supports a more informed decision. It does not guarantee approval.
Trust-building reminder: Do not exaggerate income, submit false documents, or pay unexplained fees in exchange for a promise of guaranteed approval. Accurate information and clear loan terms are essential.
Common Mistakes to Avoid Before Applying
|
Mistake |
Better approach |
|---|---|
|
Applying without income records |
Organise invoices and bank statements |
|
Ignoring credit history |
Review your credit report |
|
Choosing the largest available loan |
Borrow only what you need |
|
Comparing only interest rates |
Compare APR and total repayment |
|
Applying to many lenders without research |
Check eligibility first |
|
Ignoring the loan agreement |
Read all terms before accepting |
|
Trusting guaranteed approval claims |
Verify the lender independently |
How Vizzve Financial Can Help
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Freelancers should review the available loan options, eligibility conditions, actual lending partner, documentation requirements, and repayment terms before applying. Loan approval, interest rates, and fees depend on the applicable lender's assessment and policies.
Frequently Asked Questions
Can freelancers apply for personal loans in India?
Yes. Freelancers may apply for personal loans if they meet the lender's eligibility requirements and can provide acceptable evidence of income and repayment ability.
What should I check before applying for a freelancer loan?
Check your income proof, credit report, required documents, lender eligibility rules, interest rate, processing fees, APR, and EMI affordability.
Can I get a personal loan without salary slips?
Some lenders accept alternative income proof, such as bank statements, invoices, client contracts, and tax records. Requirements vary by lender.
What credit score is required for a freelancer loan?
There is no single score requirement across all lenders. A stronger credit history may help, but approval also depends on income, existing debt, and other factors.
How can I prove my freelance income?
You may use bank statements, invoices, client agreements, payment receipts, and income tax returns, depending on the lender's requirements.
Does irregular income affect loan eligibility?
It can. Lenders may review your income records and repayment capacity to understand whether you can manage monthly instalments despite income changes.
What charges should I check before taking a loan?
Review the interest rate, APR, processing fees, applicable taxes, late-payment charges, prepayment terms, and total repayment amount.
Can checking my credit score affect it?
Checking your own CIBIL Score does not lower it, according to CIBIL. A lender's credit enquiry during an application is different.
Is it safe to apply for a loan online?
It can be safe if you verify the actual lender, review the KFS and agreement, protect your personal information, and avoid suspicious payment requests.
Does meeting the eligibility criteria guarantee loan approval?
No. The lender makes the final decision after reviewing your documents, income, credit history, repayment capacity, and internal lending policies.
Conclusion
Before applying for a personal loan, freelancers should prepare their income records, review their credit history, check eligibility, and understand the full cost of borrowing.
The most important step is to choose a loan that fits your real income and expenses. A well-prepared application can help you avoid common errors, but approval always depends on the lender's assessment.
Explore available loan options at Vizzve Financial and review the applicable terms before applying.
Published on : 19th October
Published by : MD HEDAYATULLAH
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed