

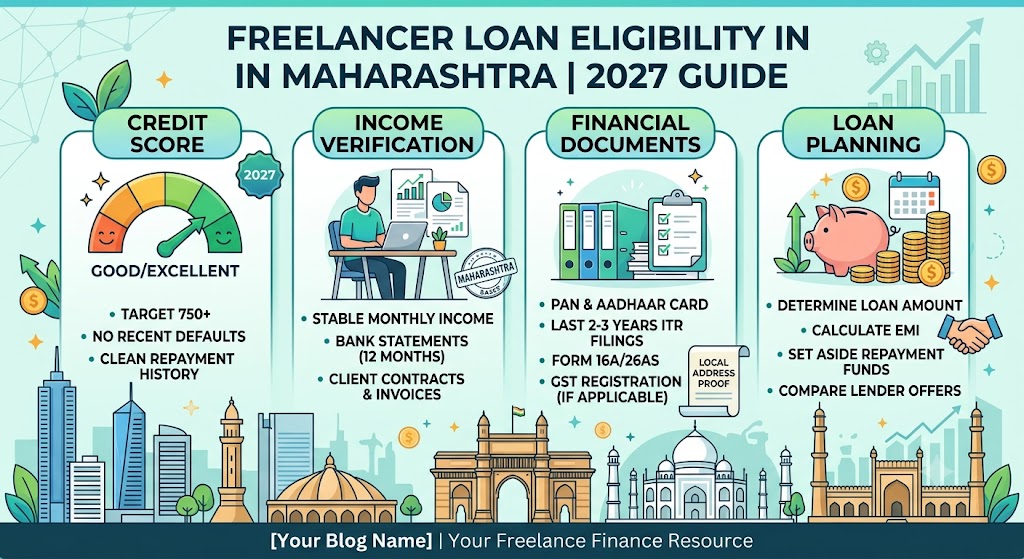
Freelancing is becoming an important way to earn for professionals working in fields such as digital marketing, graphic design, content writing, software development, consulting, photography, and online services. Across Maharashtra, freelancers may need personal loans or business finance to manage equipment costs, expand their services, handle irregular income, or cover unexpected expenses.
However, getting a loan as a freelancer can be different from getting one as a salaried employee. Freelancers may not receive fixed monthly salaries, and their income can change depending on projects, clients, and payment schedules.
As we look toward 2027, loan eligibility for freelancers in Maharashtra is likely to remain closely linked to documented income, credit history, existing debt, repayment capacity, and lender-specific policies. Digital lending may make applications more convenient, but it does not guarantee approval.
This guide explains the factors freelancers should prepare for, the possible trends to watch in 2027, and the steps that may help strengthen a loan application.
AI Answer Box: Will Freelancers Be Eligible for Loans in Maharashtra in 2027?
Freelancers may qualify for personal or business loans in Maharashtra in 2027, depending on the lender's eligibility criteria. Lenders may assess CIBIL or other credit information, bank statements, income tax returns, invoices, work history, existing EMIs, and overall repayment capacity.
There is no universal income threshold or credit score that guarantees approval. Requirements vary by lender, loan type, requested amount, and borrower profile.
1. Why Freelancer Loan Eligibility May Matter More in 2027
Freelancers often have different financial patterns from salaried employees. One month may bring several client payments, while another may generate less income. This can make it important to maintain clear financial records.
In 2027, freelancers should prepare for loan applications by focusing on the following areas:
-
Documented income: Keep records that demonstrate how much you earn over time.
-
Credit history: Maintain a responsible repayment record and review your credit report.
-
Banking consistency: Use bank accounts that clearly show business or professional receipts.
-
Existing obligations: Understand how current loans and EMIs affect your budget.
-
Digital verification: Be prepared to submit documents and complete identity checks through authorized channels.
These are practical preparation steps, not predictions that every lender will introduce the same eligibility rules in 2027.
2. Key Factors That May Affect Freelancer Loan Eligibility
Credit Score and Repayment History
Your credit profile may influence whether a lender considers your application suitable for approval. Lenders may review previous loan repayments, credit-card usage, outstanding balances, overdue payments, and other available credit information.
A strong credit history may support your application, but it does not guarantee approval.
What to do: Pay EMIs and credit-card bills on time, check your credit report for errors, and avoid taking on debt you cannot comfortably repay.
Monthly and Annual Income
Freelancers may receive income from several clients rather than one employer. Lenders may assess both the amount and consistency of this income.
Depending on the lender, supporting documents may include:
-
Recent bank statements
-
Income tax returns (ITRs)
-
Client invoices
-
Contracts or work orders
-
Payment receipts
-
Other income-related records
Maintaining a clear record of earnings can help demonstrate your repayment capacity.
Existing Loans and EMI Commitments
A freelancer earning ₹70,000 in one month may not have the same income every month. If a large portion of that money already goes toward EMIs, rent, household expenses, and business costs, a new loan could create financial pressure.
Lenders may consider existing debt and the affordability of the proposed repayment.
Practical tip: Estimate your income using a realistic average and consider how you would pay the EMI during a slow business month.
Work Experience and Client Stability
Some lenders may consider professional experience, business continuity, or the stability of income when assessing self-employed applicants.
A freelancer with repeat clients, documented projects, and consistent payment records may be better prepared to demonstrate financial reliability. However, individual lender requirements differ.
3. The 2027 Outlook: Trends Freelancers Should Watch
The following are reasonable areas to monitor, not guaranteed changes in loan eligibility.
Trend 1: More Digital Application Processes
Online applications can help borrowers submit information without visiting a branch. Digital onboarding may include identity verification, document uploads, and electronic communication.
However, digital access does not automatically mean easier eligibility or instant disbursal.
Trend 2: Greater Attention to Documented Financial Information
Freelancers should expect lenders to request enough information to assess their ability to repay. Keeping invoices, bank statements, and tax records organized can help borrowers respond to document requests.
Do not assume every lender uses the same method to verify freelance income.
Trend 3: Continued Focus on Digital Lending Safety
The Reserve Bank of India issued the Reserve Bank of India (Digital Lending) Directions, 2025, which address digital lending arrangements and borrower safeguards. These directions include requirements concerning disclosures, lender responsibilities, and the handling of digital lending relationships. <Cite refs={["turn343391search5","turn343391search0"]}/>
For freelancers applying online in 2027, verifying the actual lender and reviewing the loan terms will remain important.
Trend 4: Comparing the Full Cost of Borrowing
Borrowers should compare more than the advertised interest rate. The Annual Percentage Rate (APR), processing fees, repayment schedule, late-payment charges, and other applicable costs can affect the total expense.
RBI's digital-lending framework requires applicable digital loan costs to be disclosed through the APR and Key Facts Statement (KFS). <Cite refs={["turn343391search5","turn343391search1"]}/>
Before accepting an offer, review the complete loan documentation rather than relying only on an app notification.
4. Documents Freelancers May Need for a Loan in Maharashtra
The exact documents depend on the lender and loan product. A freelancer may be asked to provide some of the following:
| Document | Why it may be required |
|---|---|
| PAN and valid KYC documents | Identity verification |
| Bank statements | Review of financial transactions and income |
| Income tax returns | Evidence of declared income, where required |
| Client invoices | Records of work billed to clients |
| Client contracts or work orders | Supporting evidence of professional activity |
| Business or professional records | Additional verification, where applicable |
| Existing loan details | Assessment of current repayment obligations |
Not every applicant will need every document. Check the lender's official requirements before submitting personal or financial information.
5. Personal Loan vs Business Loan for Freelancers
Freelancers may consider different financing options depending on why they need the money.
| Feature | Personal loan | Business loan |
|---|---|---|
| Typical purpose | Personal or household expenses | Eligible business or professional expenses |
| Eligibility | Depends on the lender and applicant profile | Depends on the lender, business activity, and applicant profile |
| Income assessment | May include personal income and repayment capacity | May include business income and financial records |
| Documents | KYC, bank statements, income records as required | May include business and financial documents |
| Main consideration | Affordability of personal repayments | Business purpose, affordability, and loan terms |
These are general distinctions. Product terms and eligibility vary, and freelancers should confirm that the intended use is permitted under the selected loan.
6. How Freelancers Can Improve Loan Readiness Before 2027
If you plan to apply for a loan in Maharashtra, consider these practical steps.
Maintain Clear Income Records
Keep invoices, contracts, payment confirmations, bank statements, and tax documents organized. Clear records can help explain how you earn and how your income changes.
Separate Professional and Personal Transactions Where Practical
Using a dedicated account for professional receipts and expenses may make it easier to understand your cash flow. Check the lender's requirements before applying.
Build a Responsible Credit History
Pay existing credit obligations on time and monitor your credit report. Avoid taking unnecessary loans simply to build a credit profile.
Reduce Unnecessary Debt
Review existing EMIs and credit-card balances before applying. Choose a new repayment amount that remains manageable when freelance income falls.
Compare Lenders Carefully
Compare interest rates, APR, fees, tenure, prepayment conditions, and total repayment. Avoid choosing a lender solely because it advertises instant approval.
Plan for Slow Months
Before accepting a loan, estimate whether you can afford the EMI during a period with fewer projects or delayed client payments. A financial buffer can help manage income fluctuations.
7. How to Identify a Safer Digital Loan Option
Digital lending can be convenient, but borrowers should verify the lender before applying.
The RBI's digital-lending framework includes a directory intended to help people check digital lending apps and their association with regulated entities. Borrowers can consult the RBI's official website and verify the relevant lender details. <Cite refs={["turn343391search2","turn343391search5"]}/>
Before sharing your information, check:
-
Whether the actual regulated lender is clearly identified
-
Whether the interest rate, APR, fees, and repayment terms are disclosed
-
Whether a KFS and loan agreement are provided when applicable
-
Whether the app requests permissions that appear unnecessary
-
Whether a clear grievance-redressal process is available
Never share an OTP, UPI PIN, ATM PIN, or banking password with an agent or suspicious app. Do not pay an unexplained upfront fee to secure a promised loan.
8. Common Mistakes Freelancers Should Avoid
Freelancers preparing for a loan application should avoid these mistakes:
-
Relying only on a high credit score: Lenders may also consider income, debt, and documents.
-
Ignoring irregular income: A good earning month may not reflect your typical cash flow.
-
Submitting inconsistent documents: Differences in names, amounts, or dates may require clarification.
-
Applying to many lenders without comparison: Check requirements before submitting multiple applications.
-
Choosing a loan based only on fast approval: Review the total cost and affordability.
-
Assuming all loan apps are regulated lenders: Verify the actual lender and its authorized digital lending arrangements.
FAQs: Loan Eligibility for Freelancers in Maharashtra in 2027
1. Can freelancers get personal loans in Maharashtra in 2027?
Freelancers may qualify for personal loans if they meet the lender's eligibility criteria. Approval can depend on income, credit history, documents, existing debt, and repayment capacity.
2. What CIBIL score will freelancers need in 2027?
There is no single CIBIL score that guarantees approval from every lender. Minimum requirements, where used, vary by lender and loan product.
3. Can I get a loan without salary slips?
Possibly. Freelancers do not always receive salary slips, and some lenders may accept other income evidence, such as bank statements, ITRs, or invoices. Confirm the exact requirements before applying.
4. Do freelancers need ITRs to apply for a loan?
Some lenders may ask for ITRs, while others may accept different documents depending on the product and applicant profile. Do not assume that every lender has identical documentation rules.
5. Does irregular income reduce loan eligibility?
Irregular income may make repayment capacity harder to demonstrate. Clear records of earnings over time can help a lender assess the application, but approval is not guaranteed.
6. Will digital loans become easier to get in 2027?
Digital processes may make applications more convenient, but this does not guarantee easier approval. Eligibility will depend on the lender, product, and borrower's financial profile.
7. Should freelancers choose personal loans or business loans?
Choose according to the purpose of borrowing and the terms of the product. Compare eligibility, permitted use, total cost, and repayment affordability before deciding.
8. How can freelancers prepare for a loan application?
Maintain clear income records, review your credit report, manage existing EMIs, organize required documents, and compare offers from verified lenders.
Conclusion
The 2027 outlook for loan eligibility for freelancers in Maharashtra points to the continued importance of financial documentation, credit history, responsible borrowing, and digital-lending awareness. While online applications can make the process more convenient, each lender will continue to apply its own eligibility criteria.
Freelancers can prepare by keeping accurate income records, managing existing debt, reviewing loan costs, and planning repayments around changing earnings. These steps may help make an application more organized and support better borrowing decisions, but they cannot guarantee loan approval.
Published on : 19th October 2026
Published by : Shibam nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed