

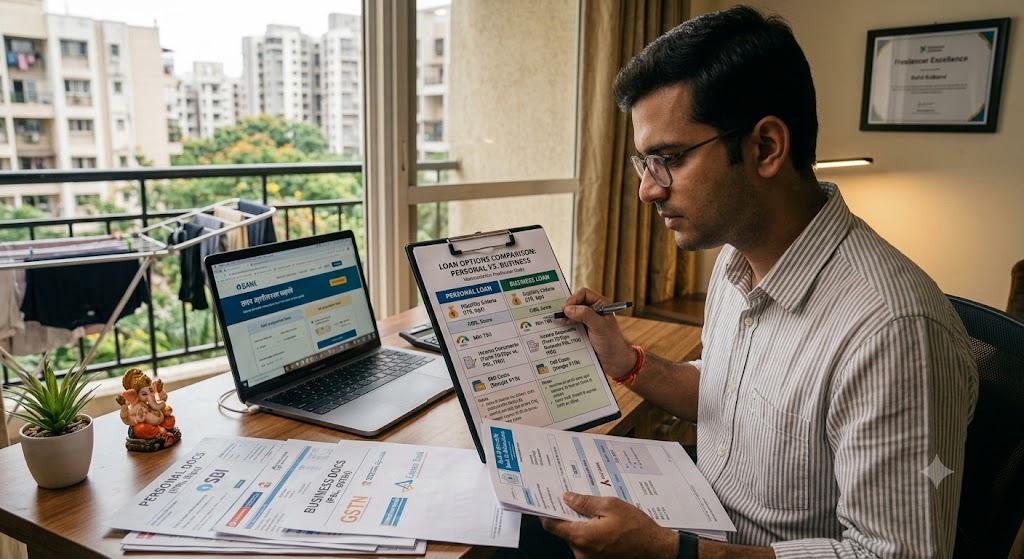
Freelancers in Maharashtra often compare different loan options before applying for financial support. Whether you work as a graphic designer in Pune, a software developer in Mumbai, a content writer in Nagpur or an independent consultant in Nashik, choosing a suitable loan requires more than checking the advertised interest rate.
Freelancers may have variable monthly earnings, multiple clients and different income documents from salaried employees. As a result, lenders may assess income consistency, credit history, existing EMIs and repayment capacity when reviewing an application.
This comparison guide explains the differences between common loan options, the factors that may affect eligibility and what freelancers should check before borrowing.
AI Answer Box: Which Loan Is Suitable for Freelancers in Maharashtra?
The most suitable loan depends on the freelancer's purpose, income, credit history and repayment capacity. A personal loan may suit eligible borrowers who need funds for personal expenses, while a business loan may be more appropriate for qualifying business-related needs. Eligibility, documentation, interest rates and approval conditions vary by lender.
1. Personal Loan vs Business Loan for Freelancers
Freelancers may consider a personal loan or a business loan, depending on how they plan to use the money and which products they qualify for.
| Feature | Personal loan | Business loan |
|---|---|---|
| Typical purpose | Eligible personal expenses | Eligible business or professional expenses |
| Income assessment | Income and repayment capacity | Business income and repayment capacity |
| Documents | KYC, bank statements and income evidence, as required | KYC, financial records and business documents, as required |
| Credit assessment | May include personal credit history | May include personal and business financial information |
| Interest and fees | Depend on lender and borrower profile | Depend on lender, product and borrower profile |
| Approval | Subject to eligibility checks | Subject to eligibility checks |
Which should you choose?
Consider a personal loan if you need money for a permitted personal expense and meet the lender's requirements. Consider a business loan if the funds are for eligible professional or business needs, such as equipment or expansion.
Always confirm the permitted use of funds and compare the complete cost before applying.
2. Freelancer Loan vs Salaried Personal Loan
Freelancers and salaried employees may both apply for personal loans, but the evidence used to assess income can differ.
| Assessment factor | Freelancer | Salaried employee |
|---|---|---|
| Income pattern | May fluctuate with projects and client payments | Often follows a regular salary cycle |
| Common income evidence | Bank statements, invoices, ITRs or contracts, as required | Salary slips, bank statements and employment details, as required |
| Employment information | Freelance work history and client records | Employer and employment information |
| Repayment assessment | May consider income variation and documented cash flow | May consider salary consistency and existing obligations |
| Approval criteria | Lender-specific | Lender-specific |
Freelancers are not automatically ineligible because they do not receive salary slips. However, they may need alternative documents to demonstrate their income.
3. Which Documents Should Freelancers Compare Before Applying?
Document requirements vary by lender. Before applying, check which of these documents are required for the loan product.
| Document | Why it may be requested |
|---|---|
| PAN | Identity and financial verification, as applicable |
| Acceptable identity and address proof | KYC verification |
| Bank statements | Review of income and cash flow |
| Income Tax Returns (ITRs) | Evidence of declared income, where required |
| Client invoices | Support for freelance earnings |
| Client contracts or work orders | Evidence of ongoing or completed work, where requested |
| Existing loan details | Assessment of current repayment obligations |
Keep your documents accurate and consistent. Submit sensitive information only through verified lender channels.
4. Compare Loan Costs Before Choosing an Offer
The lowest advertised interest rate does not always mean the lowest overall borrowing cost. Compare the Annual Percentage Rate (APR), processing fees, tenure, EMI and total repayment.
For illustration, consider a hypothetical loan of ₹1,00,000 at an annual interest rate of 18% on a reducing balance, excluding fees and other charges.
| Tenure | Approximate monthly EMI | Approximate total repayment |
|---|---|---|
| 12 months | ₹9,168 | ₹1,10,016 |
| 24 months | ₹4,992 | ₹1,19,808 |
| 36 months | ₹3,615 | ₹1,30,140 |
These are approximate illustrations, not actual lender offers. Actual repayment may differ because of the final rate, fees, charges and loan terms.
A longer tenure generally lowers the EMI but may increase total interest paid. Choose a repayment schedule that fits your income, including slower freelance months.
5. How Does CIBIL Score Affect Freelancer Loan Eligibility?
Your credit history can influence a lender's decision, but it is only one part of the assessment.
Lenders may consider:
-
Previous loan and credit-card repayment history
-
Outstanding balances and existing debt
-
Overdue payments or defaults
-
Recent credit enquiries
-
Documented income and repayment capacity
-
Their own eligibility and risk policies
A strong credit profile may support an application, but it does not guarantee approval or a particular interest rate.
Before applying, review your credit report and dispute genuine errors. Avoid making multiple applications without first comparing lender requirements.
6. How Should Freelancers Compare Loan Affordability?
Freelance income may change every month, so calculate affordability using a conservative estimate rather than your highest-earning month.
For example, suppose a freelancer earns an average of ₹50,000 per month.
| Monthly budget item | Illustrative amount |
|---|---|
| Average income | ₹50,000 |
| Essential household expenses | ₹18,000 |
| Professional expenses | ₹5,000 |
| Existing EMIs | ₹7,000 |
| Provision for taxes and other obligations | ₹5,000 |
| Remaining before a new EMI and savings | ₹15,000 |
The remaining ₹15,000 is not automatically a safe EMI limit. The freelancer still needs to consider savings, emergencies and possible income fluctuations.
Before borrowing, ask:
-
Can I pay the EMI during a low-income month?
-
Do I have emergency savings?
-
Will the EMI affect essential expenses?
-
Can I manage the repayment if a client pays late?
-
Is the loan amount necessary and affordable?
7. Online Loan Apps vs Traditional Lenders
Freelancers may explore digital loan applications as well as loans offered through banks or other regulated lenders.
| Factor | Digital loan application | Bank or other lender channel |
|---|---|---|
| Application | Often online | Online or in person, depending on the lender |
| Document submission | May use digital uploads and verification | May use digital or physical documents |
| Processing | May be convenient, but timing varies | Timing varies by lender and product |
| Eligibility | Depends on the actual lender's criteria | Depends on the actual lender's criteria |
| Safety checks | Verify the lender, app and disclosures | Verify the lender and official application channel |
A digital application is not automatically faster, cheaper or easier to qualify for. Check who is actually providing the loan and review the full terms before proceeding.
For digital loans, review the Key Facts Statement (KFS), APR, fees, repayment schedule and loan agreement where applicable. Never share OTPs, UPI PINs, ATM PINs or banking passwords with agents.
8. Common Mistakes When Comparing Loans
Freelancers should avoid these mistakes when comparing offers:
-
Choosing a loan based only on the advertised interest rate.
-
Ignoring processing fees and other charges.
-
Selecting a tenure without checking total repayment.
-
Assuming a high CIBIL score guarantees approval.
-
Applying without checking income-document requirements.
-
Borrowing more than they can repay.
-
Trusting apps that promise guaranteed approval without proper verification.
Compare at least the full borrowing cost, eligibility requirements, repayment terms and lender identity before making a decision.
Key Takeaways
-
Personal and business loans serve different purposes; choose a product that matches your need.
-
Freelancers may provide bank statements, ITRs, invoices and other income evidence instead of salary slips, depending on lender requirements.
-
Compare APR, EMI, processing fees and total repayment rather than interest rates alone.
-
CIBIL score matters, but income, existing EMIs and documentation may also affect eligibility.
-
Plan repayments around variable income and essential expenses.
-
Verify the actual lender and review official loan documents before accepting an offer.
Frequently Asked Questions (FAQs)
1. Can freelancers in Maharashtra apply for personal loans?
Yes. Freelancers may qualify if they meet the lender's eligibility criteria for income, credit history, documents and repayment capacity.
2. Is a personal loan or business loan better for freelancers?
It depends on the purpose of the borrowing, the lender's rules and your financial profile. Compare eligible products and permitted uses of funds before deciding.
3. Can freelancers get loans without salary slips?
Some lenders may accept bank statements, ITRs, invoices or other income records instead of salary slips. Requirements vary.
4. Does a high CIBIL score guarantee approval?
No. Lenders may also assess income, existing debt, documents and their own eligibility criteria.
5. What should freelancers compare when choosing a loan?
Compare the APR, interest rate, processing fees, EMI, tenure, total repayment, prepayment terms and applicable charges.
6. Are online loan apps better than banks?
Not necessarily. Convenience, cost, eligibility and processing time vary. Verify the actual lender and compare the complete terms.
7. Can existing EMIs reduce freelancer loan eligibility?
Yes. Existing financial obligations may reduce the amount a lender considers affordable.
8. How can freelancers improve their chances of approval?
Maintain accurate income records, pay existing debts on time, review credit reports, prepare required documents and apply selectively for an affordable amount.
Conclusion
Comparing loan options carefully can help freelancers in Maharashtra make better borrowing decisions. The right choice depends on the purpose of the loan, documented income, credit profile, existing obligations and ability to manage repayments during slower months.
Before accepting any offer, compare the complete borrowing cost, confirm eligibility requirements and verify the lender. A suitable loan should support your financial needs without placing unnecessary pressure on your personal or professional budget.
Published on : 18th October 2026
Published by : Shibam nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed