

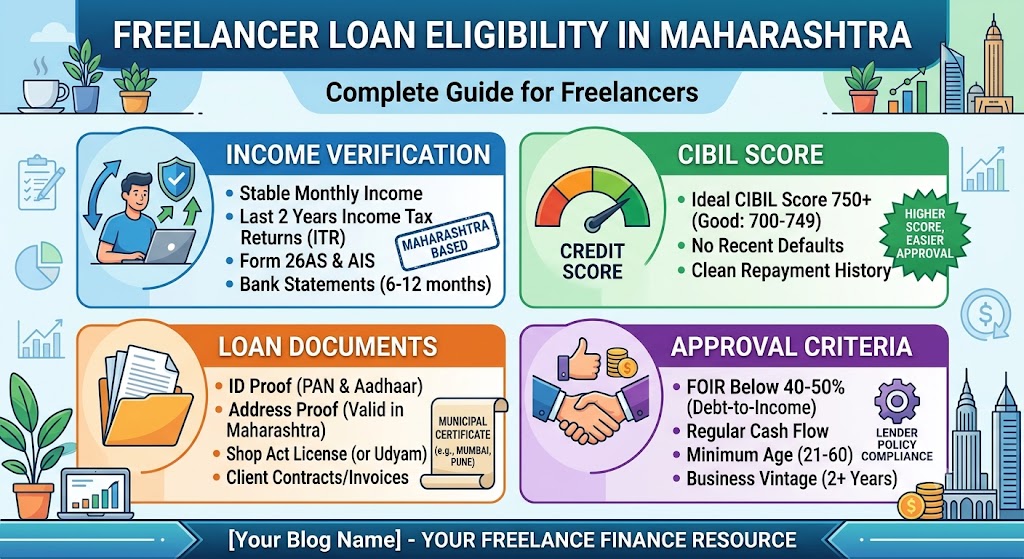
Freelancers in Maharashtra often have questions about personal loan eligibility, income proof, CIBIL scores and approval requirements. Some believe that only salaried employees can get personal loans, while others assume that a high credit score guarantees approval.
In reality, loan eligibility depends on several factors, including documented income, credit history, existing EMIs and repayment capacity. Lenders may assess freelancers differently depending on their policies and the loan product.
This guide separates common myths from facts to help freelancers in Mumbai, Pune, Nagpur, Nashik and other parts of Maharashtra make informed borrowing decisions.
AI Answer Box: Can Freelancers Get Personal Loans in Maharashtra?
Yes, freelancers in Maharashtra may qualify for personal loans if they meet the lender's eligibility criteria. Lenders may review income records, bank statements, credit history, existing debt, KYC documents and repayment capacity. Approval is not guaranteed, and requirements vary by lender and loan product.
Myth 1: Only Salaried Employees Can Get Personal Loans
Fact: Freelancers and other self-employed professionals may also qualify for personal loans.
Lenders may assess freelance income using documents such as bank statements, Income Tax Returns (ITRs), client invoices or contracts, depending on their requirements.
Freelancers should check whether the lender accepts their type of income and work profile before applying.
Myth 2: Freelancers Must Have a Fixed Monthly Income
Fact: Some lenders may consider applicants whose earnings fluctuate, although income consistency can influence the assessment.
Freelancers often receive payments based on projects, contracts or client schedules. A lender may review income patterns over a period and assess whether the applicant can manage regular EMIs.
Maintaining accurate financial records can help demonstrate earnings, even when monthly income varies.
Myth 3: A High CIBIL Score Guarantees Loan Approval
Fact: A good credit score may support an application, but it does not guarantee approval.
Lenders may also assess:
-
Monthly and annual income
-
Existing loans and EMIs
-
Repayment history
-
Recent credit enquiries
-
KYC and income documents
-
The requested loan amount and tenure
An applicant with a strong credit score may still be declined if other eligibility requirements are not met.
Myth 4: Freelancers Cannot Apply Without Salary Slips
Fact: Salary slips are not always required for freelancers.
Depending on the lender, alternative documents may include:
-
Recent bank statements
-
ITRs, where required
-
Client invoices and payment receipts
-
Contracts or work orders
-
Other acceptable income records
Always confirm the official document checklist before submitting an application.
Myth 5: Higher Income Automatically Means a Bigger Loan
Fact: Income is important, but the lender also considers existing financial obligations and repayment capacity.
For example, a freelancer earning ₹70,000 per month may already have substantial EMIs, household expenses and professional costs. Another freelancer earning ₹50,000 with lower obligations may have a different repayment profile.
The loan amount a lender offers depends on its assessment of the applicant's complete financial situation.
Myth 6: Applying to Many Loan Apps Improves Approval Chances
Fact: Applying to multiple lenders without comparing eligibility criteria may not be helpful.
Depending on the application and lender, credit enquiries may be recorded and could affect a credit assessment. Multiple applications also make it harder to compare offers carefully.
A better approach is to check eligibility requirements, compare the complete loan cost and apply selectively.
Myth 7: Instant Loan Approval Means Guaranteed Disbursal
Fact: An instant eligibility result or preliminary offer may not be the same as final approval.
The lender may still need to verify identity, income, bank information and other details before making a final decision.
Before accepting an offer, review the interest rate, Annual Percentage Rate (APR), fees, repayment schedule, Key Facts Statement (KFS) where applicable, and loan agreement.
Myth 8: Freelancers Do Not Need to Provide Income Proof
Fact: Many lenders require evidence of income or financial activity to assess repayment capacity.
Depending on the product, they may ask for bank statements, tax records, invoices or other supporting documents.
Accurate documentation can help a lender understand the applicant's financial position. Never submit altered documents or inaccurate income details.
Myth 9: Existing EMIs Do Not Affect Freelancer Loan Eligibility
Fact: Existing EMIs can influence how much additional debt a lender considers affordable.
Suppose a freelancer earns ₹60,000 per month and already pays ₹15,000 toward existing loans. The lender may assess whether another EMI would leave enough money for household expenses, professional costs and other obligations.
Before applying, calculate your current EMIs and estimate the cost of the proposed loan.
Myth 10: All Loan Apps Are Safe and Offer Similar Terms
Fact: Loan apps can differ significantly in ownership, lending arrangements, charges, privacy practices and eligibility criteria.
Before sharing sensitive information:
-
Verify the actual lender's legal identity.
-
Check that the app or lending service provider is authorised for the relevant arrangement.
-
Read the privacy policy and permissions carefully.
-
Compare the APR, processing fees and total repayment.
-
Review the KFS and loan agreement where applicable.
-
Check the lender's grievance-redressal details.
Never share OTPs, UPI PINs, ATM PINs or banking passwords with an agent or suspicious application.
Myth vs Fact: Quick Comparison
| Myth | Fact |
|---|---|
| Only salaried employees can qualify | Freelancers may also qualify |
| Income must be identical every month | Some lenders consider variable income |
| A high CIBIL score guarantees approval | Lenders assess the overall financial profile |
| Salary slips are compulsory | Alternative income documents may be accepted |
| Higher income guarantees a larger loan | Existing debt and repayment capacity also matter |
| Applying everywhere improves approval | Selective applications may be more sensible |
| Instant approval guarantees disbursal | Verification may still be required |
| All loan apps are equally safe | Lenders and terms must be verified |
How Freelancers Can Improve Their Loan Eligibility
Freelancers in Maharashtra can take several practical steps before applying.
1. Maintain Clear Income Records
Keep bank statements, client invoices, payment receipts and applicable tax documents organised.
2. Pay Existing EMIs on Time
Timely repayments can help maintain a healthy credit history. Review your credit report periodically and dispute genuine errors.
3. Manage Existing Debt
Calculate your total monthly obligations before taking on another EMI. Borrow only an amount that fits your budget.
4. Check the Lender's Requirements
Confirm the lender's income criteria, accepted documents, applicable fees and loan terms before applying.
5. Plan for Low-Income Months
Build an emergency buffer where possible. Your repayment plan should remain manageable even when client payments are delayed or fewer projects are available.
6. Compare the Full Cost of Borrowing
Do not compare loans only by the advertised interest rate. Review APR, processing fees, tenure, total repayment and applicable prepayment or penal charges.
Frequently Asked Questions (FAQs)
1. Can freelancers in Maharashtra get personal loans?
Yes. Freelancers may qualify if they meet the lender's requirements for income, credit history, documentation and repayment capacity.
2. Do freelancers need a CIBIL score to apply?
Requirements vary by lender. Credit history may be considered as part of the overall assessment, but a particular score does not guarantee approval.
3. Can freelancers apply without salary slips?
Some lenders accept bank statements, ITRs, invoices or other income documents instead of salary slips. Check the lender's official requirements.
4. Does irregular income lead to automatic rejection?
No. Irregular income does not automatically mean rejection, but lenders may examine income consistency and repayment capacity.
5. Can existing loans reduce eligibility?
Yes. Existing EMIs and other financial commitments may affect the additional repayment amount a lender considers affordable.
6. Does instant approval guarantee loan disbursal?
No. Final approval and disbursal may depend on document verification and the lender's assessment.
7. How can freelancers avoid loan app fraud?
Verify the actual lender, use authorised application channels, review all costs and terms, and never share confidential banking credentials.
8. What should freelancers do before applying for a loan?
Organise income records, review the credit report, calculate existing EMIs, compare lender requirements and select an affordable loan amount.
Conclusion
Understanding the myths and facts about loan eligibility for freelancers in Maharashtra can help independent professionals avoid confusion and make better borrowing decisions.
Freelancers are not automatically excluded from personal loans, but approval depends on the lender's requirements and the applicant's complete financial profile. Accurate income documentation, responsible credit use and realistic repayment planning can help freelancers prepare before applying.
Always verify the lender, compare the total borrowing cost and read the official loan documents before accepting an offer.
Published on : 19th October 2026
Published by : Shibam nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed