

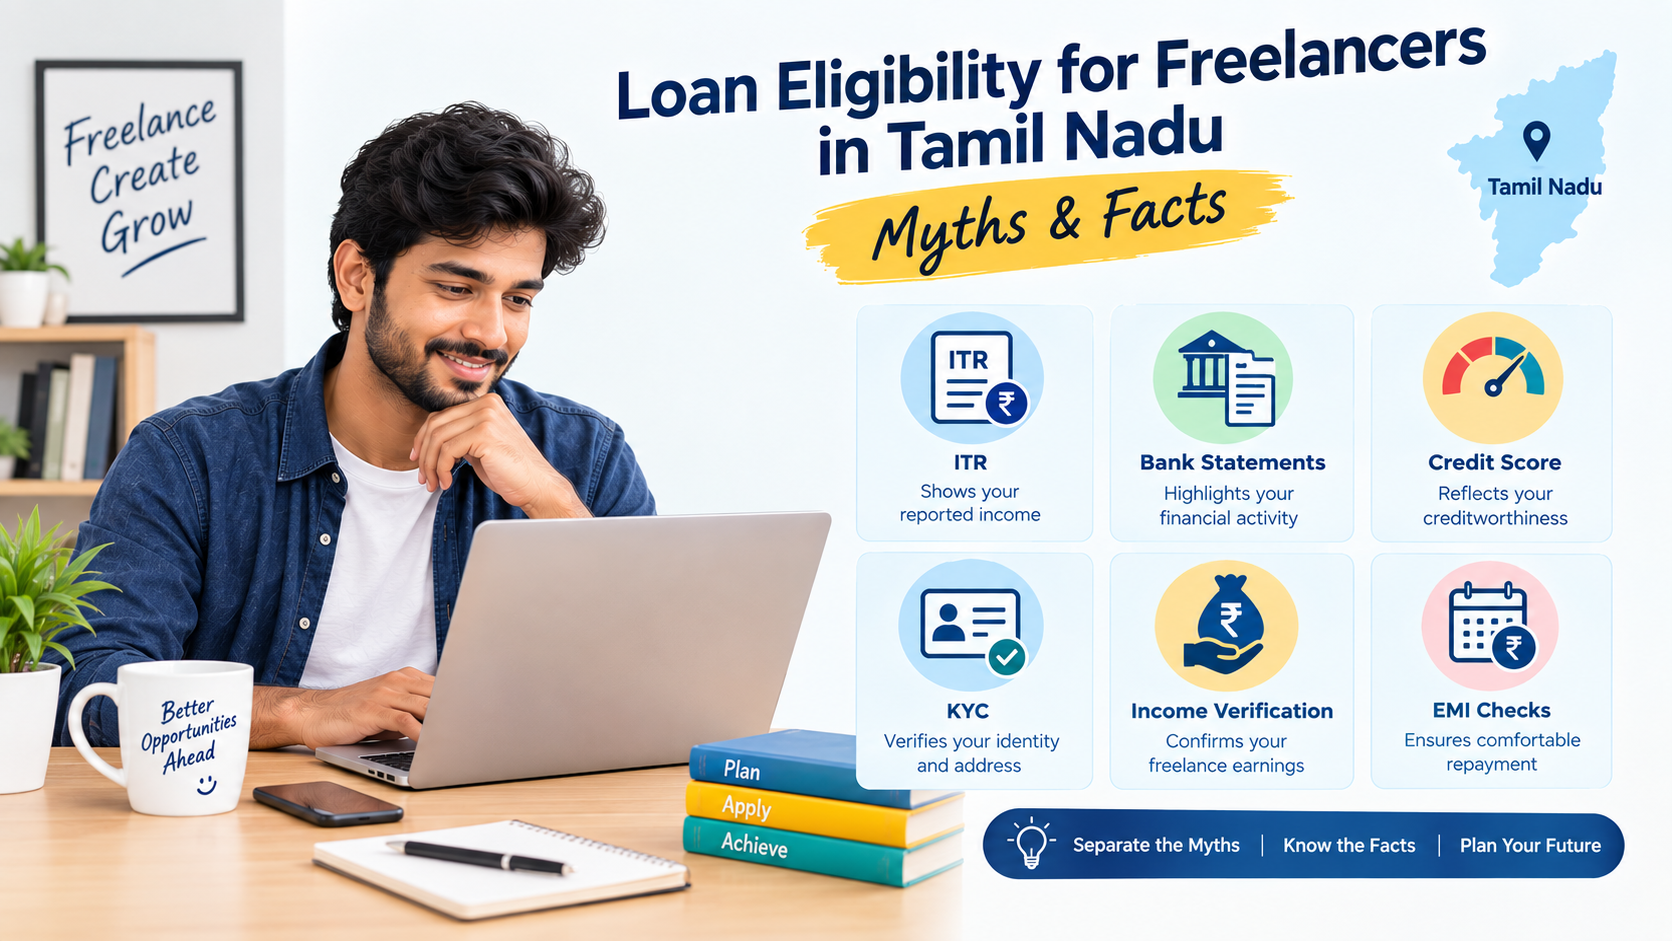
Freelancers in Tamil Nadu often have questions about whether they can qualify for a personal or business loan. Unlike salaried employees, freelancers may not receive a fixed monthly salary or traditional salary slips, which can create confusion about loan eligibility for freelancers in Tamil Nadu.
In reality, lenders can assess freelancers using several types of financial information, including income records, ITRs, bank statements, credit history, KYC documents and existing financial obligations. Eligibility requirements can differ from one lender to another.
Let's look at some common myths and facts.
Myth 1: Freelancers Cannot Get Loans
Fact: Freelancers can apply for loans if they meet the lender's eligibility requirements.
A lender may consider factors such as:
-
Documented income
-
Credit history
-
Bank statements
-
ITRs
-
Existing EMIs
-
KYC details
-
Work or business history
-
Repayment capacity
Being a freelancer does not automatically mean that a loan application will be rejected.
Myth 2: Salary Slips Are Always Mandatory
Fact: Freelancers may have alternative ways to demonstrate their income.
Depending on the lender, documents may include:
-
Income Tax Returns (ITRs)
-
Bank statements
-
Client invoices
-
Freelance contracts
-
GST records, where applicable
-
Business or professional registration documents
-
Other accepted income records
The exact documentation depends on the lender and loan product.
Myth 3: A Good Credit Score Guarantees Approval
Fact: A credit score is only one part of the lending assessment.
Lenders can also consider income, existing debt, repayment capacity, KYC, documentation and their own eligibility policies.
Therefore, even a strong credit history does not automatically guarantee loan approval.
Myth 4: Irregular Freelance Income Means Automatic Rejection
Fact: Variable income may require additional assessment, but it does not automatically make a freelancer ineligible.
For example, a freelancer whose monthly income changes could use historical bank statements and ITRs to demonstrate their financial activity.
Lenders may evaluate the overall income pattern and repayment capacity rather than looking at only one month.
Myth 5: Only Salary Income Is Considered
Fact: Freelance or self-employed income may also be considered by lenders.
Freelancers should maintain clear records showing professional earnings. Depending on the loan product, ITRs, bank transactions and other financial documents may help demonstrate income.
Myth 6: The Maximum Approved Amount Is the Right Amount to Borrow
Fact: Loan eligibility and affordable borrowing are not the same thing.
Even if a lender offers a particular amount, freelancers should calculate whether the EMI fits their actual financial situation.
Before borrowing, consider:
-
Average monthly income
-
Existing EMIs
-
Household and business expenses
-
New EMI
-
Emergency savings
-
Total repayment cost
This is especially important when freelance income changes from month to month.
Myth 7: Instant Online Loans Guarantee Approval
Fact: Digital applications can make the process faster, but they do not guarantee final approval.
Lenders may still conduct KYC, credit, income and repayment-capacity checks before approving and disbursing a loan.
Therefore, freelancers should be cautious about advertisements promising guaranteed loans with minimal verification.
Myth 8: Interest Rate Is the Only Cost to Check
Fact: Borrowers should look at the complete cost of the loan.
Before accepting an offer, compare:
| Loan Factor | Why It Matters |
|---|---|
| Interest rate | Determines interest charged |
| APR | Helps understand overall borrowing cost |
| EMI | Shows monthly repayment |
| Tenure | Affects EMI and total interest |
| Processing fee | Adds to borrowing cost |
| Prepayment terms | Important for early repayment |
| Penal charges | Relevant when payments are delayed |
| Total repayment | Shows overall amount payable |
Reading the applicable Key Facts Statement (KFS) and loan agreement can help borrowers understand the terms before accepting a digital loan.
Myth 9: Freelancers Should Apply to Many Lenders
Fact: Applying repeatedly without comparing loan terms may not be a good approach.
Before submitting applications, compare eligibility requirements, interest rates, APR, fees and repayment terms. Apply only after checking whether the product fits your requirements.
Myth 10: Online Loans Do Not Require Safety Checks
Fact: Digital convenience should not replace basic verification.
Before applying online:
-
Verify the actual lender.
-
Use the official website or application.
-
Check interest rate and APR.
-
Read the applicable KFS.
-
Review fees and charges.
-
Understand the EMI and repayment schedule.
-
Check privacy and data permissions.
-
Read the loan agreement.
-
Avoid suspicious upfront-payment requests.
-
Never share OTPs, UPI PINs, ATM PINs or internet-banking passwords.
Freelancer Loan Eligibility: Myths vs Facts
| Common Myth | Reality |
|---|---|
| Freelancers cannot get loans | Freelancers may qualify if they meet lender criteria |
| Salary slips are always required | Alternative income documents may be accepted |
| A high credit score guarantees approval | Multiple factors are considered |
| Irregular income means automatic rejection | Documented income can still be assessed |
| Only salary income matters | Freelance income may be considered |
| Maximum eligibility should be borrowed | Borrowing should match repayment capacity |
| Instant loans guarantee approval | Verification may still be required |
| Interest rate is the only cost | APR and fees also matter |
| Multiple applications improve chances | Compare options before applying |
| Online loans need no verification | Lender and loan terms should be checked |
How Freelancers Can Prepare for a Loan
Freelancers can make the application process more organized by maintaining proper financial records.
Keep Income Documents Ready
Maintain recent ITRs, bank statements, invoices and other relevant income records.
Monitor Your Credit Profile
Pay existing loans and credit card dues on time and review your credit report periodically.
Calculate Your EMI Capacity
Consider your average income, existing debt and regular expenses before deciding how much to borrow.
Keep KYC Information Updated
Make sure your name, address and other details are consistent across your important documents.
Compare the Full Loan Cost
Do not focus only on the advertised interest rate. Review APR, fees, EMI, tenure, total repayment and other applicable charges.
Key Takeaways
-
Freelancers in Tamil Nadu can apply for loans if they meet the lender's criteria.
-
A salary slip is not necessarily the only proof of income.
-
ITRs and bank statements can help demonstrate freelance income.
-
Credit score matters, but it does not guarantee approval.
-
Irregular income does not automatically mean rejection.
-
Existing EMIs should be considered before taking additional debt.
-
Compare the complete cost of borrowing before accepting a loan.
-
Verify digital lenders and read the applicable loan documents carefully.
Frequently Asked Questions
Can freelancers in Tamil Nadu get personal loans?
Yes. Freelancers can apply for personal loans, subject to the lender's eligibility requirements and financial assessment.
Can I get a loan without a salary slip?
Some lenders may accept ITRs, bank statements and other income documents instead of traditional salary slips.
Is ITR important for freelancer loan applications?
ITRs can help demonstrate reported income and may be requested as part of the lender's documentation process.
Does irregular income affect loan eligibility?
It can make income assessment more complex, but irregular income does not automatically mean that a freelancer cannot qualify.
Does a high credit score guarantee a loan?
No. Lenders may consider several factors, including income, existing debt, KYC and repayment capacity.
Can freelancers apply for business loans?
Depending on the nature of their professional activity and the lender's criteria, freelancers may be able to apply for suitable business loan products.
What documents can freelancers use as income proof?
Possible documents include ITRs, bank statements, invoices, contracts and other financial records accepted by the lender.
Should I compare APR before accepting a loan?
Yes. APR and other applicable charges can help you understand the broader cost of borrowing.
Are instant online loans guaranteed?
No. An instant application or preliminary offer does not necessarily mean guaranteed final approval.
What should I check before applying for an online loan?
Verify the lender, review the KFS and loan agreement, compare APR and fees, understand the repayment schedule and protect sensitive financial credentials.
Published on : 3rd October 2026
Published by : shibam nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+