

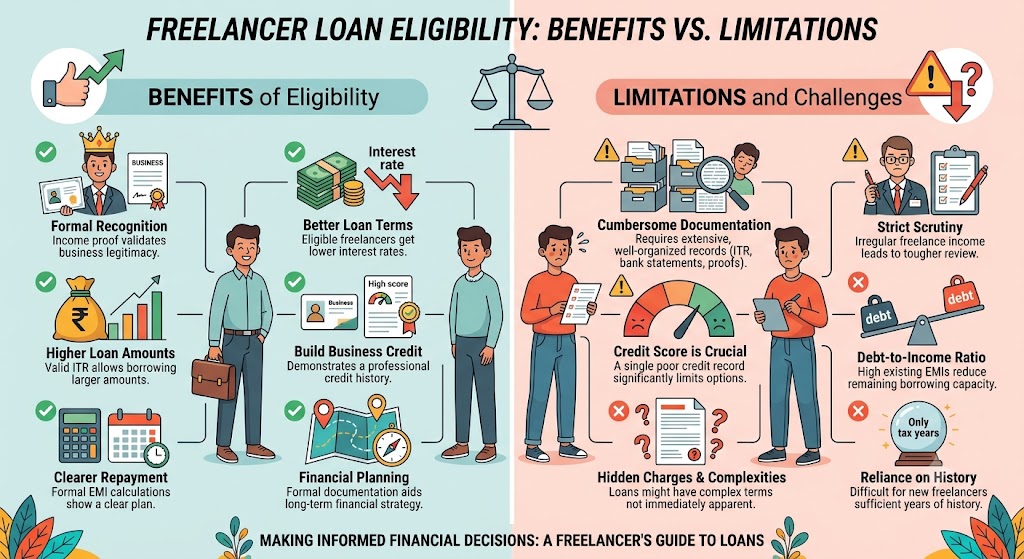
Freelancing offers flexibility and independence, but accessing formal credit can sometimes be more complicated than it is for salaried employees. Freelancers in Telangana can apply for personal loans and other credit products, but approval generally depends on factors such as income, credit history, documentation and repayment capacity.
Understanding the benefits and limitations of freelancer loan eligibility can help borrowers decide whether taking a loan is appropriate for their financial situation.
Can Freelancers in Telangana Get a Loan?
Yes. Freelancers may be eligible for loans if they meet the lender's requirements.
Unlike salaried employees who may provide salary slips, freelancers often need to demonstrate their income through other records, such as:
-
ITR documents
-
Bank statements
-
Client invoices
-
Work contracts
-
Payment records
-
GST records, where applicable
-
Professional or business documents
The exact requirements vary by lender and loan product.
How Is Freelancer Loan Eligibility Assessed?
Lenders may consider several aspects of a freelancer's financial profile.
Credit History
Your repayment history can influence how a lender evaluates your application. Previous loans, credit-card repayments, outstanding balances and defaults may be considered.
Freelance Income
Lenders may examine the amount, consistency and documentation of your income.
A freelancer with regular, traceable income may have a clearer financial profile than someone whose earnings fluctuate significantly without supporting records.
ITR and Tax Records
ITRs can provide documented evidence of reported income and may be useful when assessing self-employed applicants.
Bank Statements
Bank statements can help demonstrate actual cash flow, including client payments and existing financial commitments.
Existing EMIs
Existing loans affect repayment capacity. A high monthly debt obligation may reduce the amount of additional credit a lender considers affordable.
KYC
Valid identity and address documentation is generally required during the loan application and verification process.
Benefits of Loans for Freelancers in Telangana
1. Access to Formal Credit
A loan can provide freelancers with access to formal credit without depending entirely on personal savings or informal borrowing.
This can be useful for planned expenses, provided the repayment obligation is affordable.
2. No Traditional Salary Slip May Be Needed
Freelancers may not have monthly salary slips, but some lenders may accept alternative income documentation such as ITRs, bank statements and invoices.
This gives self-employed professionals another way to demonstrate their earning capacity.
3. Can Support Business or Professional Needs
Depending on the loan type and lender's terms, borrowed funds may help freelancers manage professional expenses such as:
-
Laptop or equipment purchases
-
Software and subscriptions
-
Workspace expenses
-
Professional training
-
Marketing
-
Working-capital requirements
The loan should still be used according to the applicable loan agreement.
4. Digital Application Convenience
Many loan applications can be completed online, allowing eligible borrowers to submit documents digitally.
However, convenience should not replace careful checking of the lender, loan terms and charges.
5. Can Help Manage Planned Expenses
For a financially prepared freelancer, a loan can help manage a significant planned expense without using all available savings at once.
The key is ensuring that the EMI remains affordable throughout the loan tenure.
Limitations of Freelancer Loan Eligibility
1. Variable Income Can Make Approval Difficult
Freelancers may not earn the same amount every month. Significant income fluctuations can make repayment capacity harder for a lender to assess.
2. More Income Documentation May Be Required
Because freelancers often do not have traditional salary slips, lenders may request several documents to verify income.
This can include ITRs, bank statements, invoices and contracts.
3. Credit History Matters
A weak credit history may make it harder to qualify or may result in less favourable loan terms.
Past missed payments, defaults or high outstanding debt can affect the overall assessment.
4. Existing Debt Can Reduce Eligibility
A freelancer with several existing EMIs may have limited capacity for another monthly obligation.
Before applying, calculate:
Existing EMIs + Proposed EMI = Total Monthly Debt Obligation
Compare this with your dependable income rather than your highest earning month.
5. Loan Costs Can Add Up
The cost of borrowing may include more than interest.
Depending on the loan, borrowers may need to consider:
-
Interest
-
APR
-
Processing fee
-
Applicable taxes
-
Late-payment charges
-
Penal charges
-
Documentation charges
-
Prepayment or foreclosure charges, where applicable
Always compare the complete cost before accepting an offer.
6. Eligibility Does Not Guarantee Approval
Meeting basic eligibility requirements does not automatically mean a loan will be approved.
The final decision depends on the lender's internal assessment, credit policy and the applicant's overall financial profile.
Freelancer Loan: Benefits vs Limitations
| Benefits | Limitations |
|---|---|
| Access to formal credit | Variable income can affect assessment |
| Alternative income proof may be accepted | More documentation may be required |
| Online application may be convenient | Credit history can affect approval |
| Can support planned expenses | Existing EMIs reduce repayment capacity |
| Useful for eligible professional needs | Interest and other charges increase borrowing cost |
| Flexible options may be available | Approval is not guaranteed |
What Should Freelancers Check Before Applying?
Before submitting a loan application, review the following:
Credit Profile
Check your credit history and make sure there are no obvious errors.
Income
Calculate your average and dependable freelance income rather than relying on your best earning month.
Documents
Keep ITRs, bank statements, invoices, contracts and KYC documents ready where required.
Existing Debt
Calculate all current EMIs and other financial obligations.
New EMI
Estimate whether the proposed EMI can comfortably fit into your monthly budget.
Complete Loan Cost
Compare the interest rate, APR, processing fees, applicable charges and total repayment.
KFS
For applicable digital loans, read the Key Facts Statement carefully before accepting the offer.
Lender Verification
Verify the actual lender and understand how your documents and personal information will be handled.
How Freelancers Can Improve Their Loan Eligibility
A few practical steps can strengthen your financial profile:
-
Pay existing EMIs and credit-card bills on time.
-
Maintain organized bank statements.
-
Keep ITRs and tax records updated.
-
Maintain proper invoices and payment records.
-
Avoid unnecessary debt.
-
Avoid applying for multiple loans without a clear need.
-
Choose a realistic loan amount.
-
Maintain sufficient repayment capacity.
-
Compare loan costs before borrowing.
FAQs
Can freelancers in Telangana get personal loans?
Yes. Freelancers may qualify if they meet the lender's credit, income, documentation and repayment requirements.
Is a salary slip required for freelancer loans?
Not necessarily. Some lenders may accept ITRs, bank statements, invoices and other income documents instead.
What is the biggest benefit of a freelancer loan?
One benefit is access to formal credit even when the borrower does not have a traditional salaried job, subject to lender eligibility.
What is the biggest limitation?
Variable income can make income and repayment-capacity assessment more difficult.
Does ITR help with loan eligibility?
ITR can provide evidence of reported income and may support income verification, depending on the lender's requirements.
Can existing EMIs affect eligibility?
Yes. Existing debt obligations can reduce the amount of additional repayment a lender considers affordable.
Should freelancers borrow the maximum amount they qualify for?
No. The maximum eligible amount may not be the most affordable amount. Borrow based on actual need and repayment capacity.
What should I compare before accepting a loan?
Compare the interest rate, APR, EMI, processing fee, applicable charges, total repayment and other loan terms.
Published on : 7TH October 2026
Published by : shibam nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed