

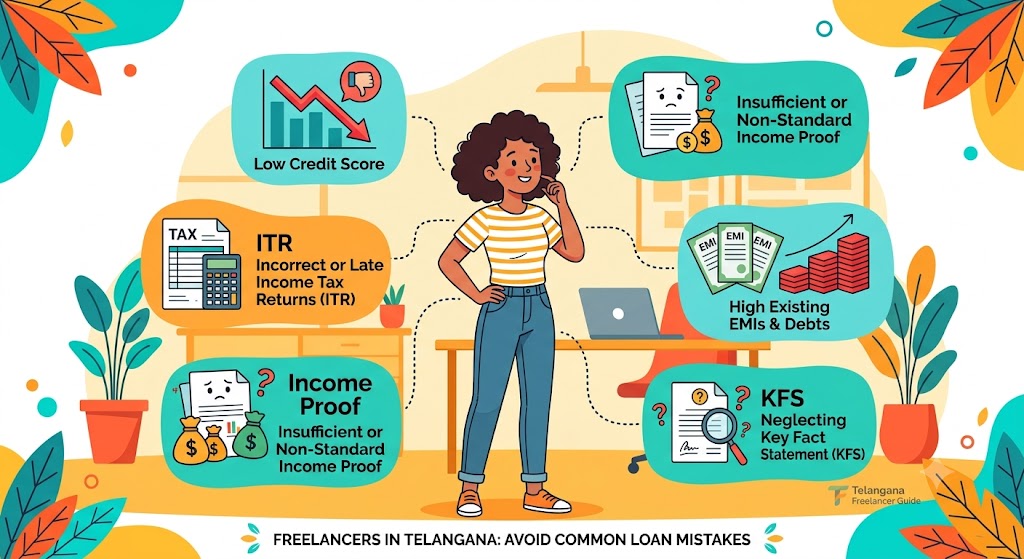
Freelancers in Telangana can apply for personal loans and other credit products, but loan approval is not based on income alone. Lenders may consider credit history, income stability, bank statements, ITR, KYC documents, existing EMIs and overall repayment capacity.
Many freelancers make avoidable mistakes while preparing a loan application. These mistakes can make income verification difficult, increase the chances of rejection or lead to borrowing that is more expensive than expected.
Understanding these common mistakes can help freelancers prepare a stronger application and make better borrowing decisions.
What Do Lenders Check for Freelancer Loan Eligibility?
Unlike salaried applicants who may provide salary slips, freelancers often have variable income. Therefore, lenders may use several documents to understand the applicant's financial position.
Common factors include:
-
Credit history and repayment behaviour
-
Freelance income
-
ITR and tax records
-
Bank account statements
-
Existing loans and EMIs
-
KYC information
-
Professional or business history
-
Requested loan amount
-
Repayment capacity
-
Lender-specific eligibility rules
10 Common Mistakes Freelancers Should Avoid
1. Applying Without Checking Credit History
One of the most common mistakes is applying for a loan without first reviewing your credit profile.
Missed payments, defaults, high outstanding balances or multiple recent credit applications may affect how lenders assess your application.
Better approach: Review your credit report before applying and make sure the information is accurate.
2. Showing Unclear or Inconsistent Income
Freelance income can change every month. Problems can arise when the income declared in the application does not match the supporting documents.
For example, your application may show a high monthly income while your bank statements show substantially different cash flows.
Better approach: Keep your income figures realistic and supported by documents such as ITRs, bank statements, invoices and payment records.
3. Ignoring ITR Documentation
Some freelancers focus only on bank transactions and overlook their tax records.
ITRs can provide useful evidence of reported income, particularly when income varies throughout the year.
Better approach: Keep relevant ITR and tax documents ready before beginning the application.
4. Depending on One Month's Income
A freelancer may have an unusually high-income month because of a large project. Using that month as proof of regular income can create an unrealistic picture of repayment capacity.
Better approach: Consider your income over a longer period and use consistent financial records wherever possible.
5. Having Too Many Existing EMIs
Another major mistake is taking a new loan without calculating current debt obligations.
If you already have several EMIs, adding another monthly payment may put pressure on your finances.
Before applying, calculate:
Existing EMIs + Proposed New EMI = Total Monthly Debt Obligation
Then compare this with your dependable income.
6. Applying for a Loan Amount That Is Too High
Being eligible for a particular loan amount does not necessarily mean you should borrow the maximum available amount.
A larger loan generally means a larger repayment obligation and potentially higher total interest.
Better approach: Borrow according to your actual requirement and repayment capacity.
7. Comparing Only the Interest Rate
A low advertised interest rate can look attractive, but it may not represent the complete cost of borrowing.
Depending on the loan, other costs may include:
-
Processing fees
-
Applicable taxes
-
Penal charges
-
Late-payment charges
-
Documentation charges
-
Prepayment or foreclosure charges, where applicable
Better approach: Compare the overall cost, including APR and other applicable charges.
8. Skipping the Key Facts Statement
Some borrowers accept a digital loan quickly without reading the loan documents carefully.
For applicable loans, the Key Facts Statement (KFS) can help borrowers understand important information such as the APR, charges, repayment terms and other key conditions.
Better approach: Read the KFS and loan agreement before accepting the offer.
9. Sharing Sensitive Banking Information
Freelancers applying through digital platforms should be particularly careful about fraud.
Never share sensitive credentials such as:
-
OTPs
-
UPI PIN
-
ATM PIN
-
Card PIN
-
Internet banking password
A legitimate loan process should not require you to disclose these confidential credentials to another person.
10. Not Checking Who the Actual Lender Is
A loan application may be presented through a digital platform or loan app, but borrowers should understand who is actually providing the credit.
Better approach: Verify the actual lender, read the terms and check whether the lending arrangement is legitimate before sharing documents or accepting a loan.
Common Documents Freelancers Should Keep Ready
Requirements vary between lenders, but freelancers may commonly be asked for:
| Document | Why It May Be Needed |
|---|---|
| PAN | Identity and financial verification |
| Aadhaar/Other KYC | Identity and address verification |
| Bank Statements | Income and cash-flow assessment |
| ITR | Income verification |
| Invoices | Evidence of freelance earnings |
| Client Contracts | Professional income evidence |
| GST Records | Business verification where applicable |
| Existing Loan Details | Assessment of current obligations |
A salary slip is not necessarily mandatory for every freelancer loan. Alternative income documents may be accepted depending on the lender's policy.
How to Avoid Loan Application Mistakes
Before submitting your application, follow this simple checklist:
-
Check your credit history.
-
Calculate your average and dependable income.
-
Keep recent ITRs ready.
-
Organize bank statements.
-
Prepare invoices or contracts if required.
-
Calculate all existing EMIs.
-
Estimate the proposed EMI.
-
Borrow only what you can afford.
-
Compare interest rates and APR.
-
Check processing and other applicable charges.
-
Read the KFS carefully.
-
Verify the actual lender.
-
Review permissions before sharing financial information.
-
Read the final loan agreement before accepting.
What If Your Loan Application Is Rejected?
A rejection does not necessarily mean you can never qualify for a loan.
First, understand the possible reason. It could relate to credit history, insufficient documentation, income inconsistency, high existing debt, loan amount or lender-specific criteria.
Avoid immediately submitting applications to many lenders. Multiple credit applications within a short period may affect your credit profile depending on how they are reported.
Instead, review your finances, correct documentation issues and consider applying only when your financial profile is better prepared.
FAQs
Can freelancers in Telangana get personal loans?
Yes. Freelancers may qualify if they meet the lender's income, credit, documentation and repayment requirements.
Is a salary slip required for freelancers?
Not always. Depending on the lender, ITRs, bank statements, invoices and other income records may be used instead.
Does ITR improve freelancer loan eligibility?
ITR can help provide documented evidence of reported income, although it does not guarantee loan approval.
Can irregular freelance income cause loan rejection?
It can make income assessment more difficult. Lenders may consider the consistency and sustainability of income along with other financial information.
Should freelancers take the maximum loan amount offered?
No. The eligible amount and affordable amount can be different. Borrow based on your actual requirement and repayment capacity.
What should I check besides the interest rate?
Check the APR, processing fee, applicable taxes, EMI, total repayment, penal charges and other terms.
Why is KFS important?
The KFS helps borrowers understand important loan costs and terms before accepting applicable credit products.
Can existing EMIs affect freelancer loan eligibility?
Yes. Existing debt obligations can affect how much additional repayment a lender considers affordable.
Published on : 7TH October 2026
Published by : shibam nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed