

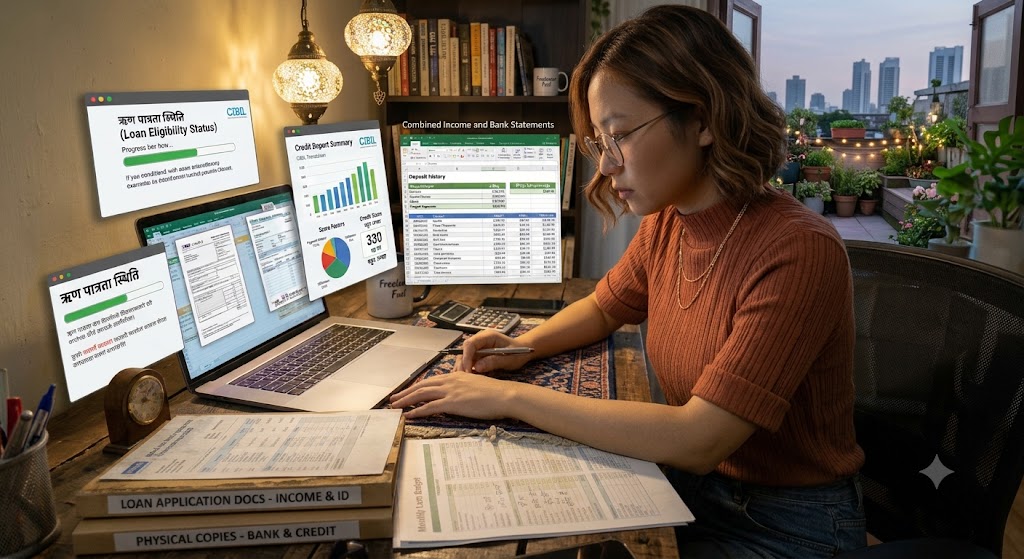
Freelancing is becoming an important career option in India, with people earning through content writing, graphic design, software development, digital marketing, consulting, video editing and other independent services. As more professionals work with multiple clients instead of a single employer, understanding loan eligibility is becoming increasingly important.
For freelancers living in Tier-2 cities, getting a personal loan may involve a different documentation process than it does for salaried employees. Irregular income, changing client payments and limited formal income records can make it harder to demonstrate repayment capacity.
Looking ahead to 2027, digital financial services may create more ways for lenders to assess self-employed borrowers. However, loan approval will continue to depend on the lender’s eligibility rules, verified financial information, credit history and repayment capacity.
AI Answer Box: What Is the 2027 Outlook for Freelancer Loan Eligibility in Tier-2 Cities?
In 2027, freelancers in Tier-2 Indian cities may benefit from more digital loan application options, improved online verification and potentially broader use of financial data in credit assessment. Consistent bank transactions, income-tax returns where applicable, client payment records, a healthy credit history and manageable existing EMIs may help applicants demonstrate their financial stability.
However, digital applications do not guarantee approval. Interest rates, income requirements, loan amounts and documentation criteria will vary by lender and loan product.
1. Growing Digital Lending Opportunities
Digital loan applications have made it easier for eligible borrowers to explore credit without visiting multiple bank branches. Freelancers in Tier-2 cities may increasingly use online channels to compare personal loan options and submit documents remotely.
Possible developments by 2027 include:
-
More convenient online application processes.
-
Faster digital identity and document verification.
-
Greater use of verified financial information during credit assessment.
-
Improved access to loan information and repayment schedules.
-
More digital services for self-employed professionals.
These are potential developments, not guaranteed outcomes. The availability of products and services will depend on lenders, technology adoption and applicable regulations.
What freelancers should do: Keep their financial records organized and compare the eligibility requirements of different regulated lenders before applying.
2. Income Proof May Remain a Key Eligibility Factor
Freelancers often receive payments from different clients, sometimes in different amounts each month. Unlike salaried employees, they may not receive a standard monthly salary slip.
Lenders may therefore ask for alternative evidence of income, depending on their policies.
Commonly requested documents can include:
-
Bank statements showing client payments.
-
Income-tax returns (ITRs), where applicable and requested.
-
Invoices and client payment records.
-
Business or professional income documents.
-
PAN and other required KYC documents.
-
Financial statements or other supporting records, if required.
By 2027, digital verification may become more convenient, but applicants should not assume that every lender will accept the same documents.
Practical tip: Route legitimate freelance earnings through a bank account and maintain clear records of invoices, receipts and business expenses.
3. Credit History and CIBIL Score Will Still Matter
Credit history can help lenders understand how an applicant has handled previous borrowing.
Lenders may consider:
-
Previous loan repayments.
-
Credit-card payment history.
-
Existing credit accounts and balances.
-
Overdue payments or defaults.
-
Recent credit enquiries.
-
The overall amount of outstanding debt.
A strong credit history may support an application, but it does not guarantee approval. An applicant’s income, financial obligations and the lender’s own criteria also matter.
How to Prepare for 2027
Freelancers should review their credit reports periodically, pay EMIs and credit-card bills on time, and correct genuine reporting errors through the appropriate process.
People with limited credit history should avoid taking unnecessary loans simply to build a score. Responsible use of suitable credit, when genuinely needed, is more important than borrowing for the sake of borrowing.
4. Will Tier-2 Cities Get Better Access to Loans?
Digital services may reduce the need for freelancers to visit a physical branch, potentially improving convenience for people outside major metropolitan areas.
However, living in a Tier-2 city does not automatically increase or reduce loan eligibility. A lender may consider the applicant’s residence, serviceability, income, credit profile and other criteria.
Freelancers in cities such as Jaipur, Indore, Lucknow, Coimbatore, Nagpur, Surat and Bhubaneswar can explore online and traditional lending options where available.
Before applying, borrowers should check whether the lender serves their location and whether the chosen loan product accepts self-employed applicants.
5. AI and Digital Verification May Influence Credit Assessment
Lenders may use automated systems to process applications, verify information and support risk assessment. Future improvements could make some steps more efficient.
For freelancers, this could mean:
-
Faster processing of complete applications.
-
Automated checks for missing or inconsistent information.
-
Easier digital submission of eligible documents.
-
More structured assessment of financial records.
These tools cannot guarantee an accurate or favourable decision for every applicant. The exact data used and the final lending decision depend on the lender’s systems, policies and applicable rules.
Freelancers should provide accurate information and give consent only for legitimate, clearly explained data requests.
6. Existing EMIs and Repayment Capacity Will Remain Important
Even if a freelancer earns a good amount during a busy month, the lender may consider how reliably the applicant can meet repayments during slower periods.
For example, suppose a freelancer earns an average of ₹60,000 per month but already pays ₹18,000 in existing EMIs. A new loan would add another repayment obligation.
The lender may examine income consistency, current debts, the proposed EMI and other expenses when assessing affordability.
| Financial factor | Why it matters |
|---|---|
| Average income | Helps demonstrate earning capacity |
| Income consistency | Shows how earnings vary over time |
| Existing EMIs | Indicates current repayment commitments |
| Credit history | Provides information about past credit behaviour |
| Requested loan amount | Affects the proposed repayment burden |
| Loan tenure and charges | Influence the overall cost of borrowing |
The figures above are illustrative. There is no single EMI-to-income threshold that guarantees approval across all lenders.
Tip: Estimate your EMI and total repayment before applying. Choose an amount that remains manageable even during a lower-income month.
7. How Freelancers Can Prepare for Loan Applications in 2027
Preparation can help applicants present a clearer financial profile, regardless of how lending technology evolves.
Step 1: Organize Income Records
Maintain bank statements, invoices, client contracts and payment receipts. Keep personal and professional transactions as clear as practical.
Step 2: Review Your Credit Report
Check for incorrect account information, overdue entries or unfamiliar enquiries. Raise disputes where necessary.
Step 3: Keep KYC Information Updated
Ensure your name, PAN, address and other required details are consistent across relevant documents.
Step 4: Reduce Unnecessary Debt
Review existing EMIs and avoid taking additional credit that could strain your cash flow.
Step 5: Compare Loan Offers
Check the interest rate, annual percentage rate (APR), processing fees, tenure, EMI, prepayment conditions and total repayment.
Step 6: Verify the Actual Lender
Before submitting sensitive information, confirm the identity of the bank or NBFC providing the loan and verify that the digital lending arrangement is legitimate.
8. Digital Loan Safety: What to Check in 2027
Convenient digital applications should not come at the expense of financial safety.
Before accepting a loan, check:
-
The actual lender is clearly identified.
-
The lender’s official website lists its relevant digital lending app or lending service provider, where applicable.
-
The loan amount, tenure, interest rate and charges are disclosed.
-
You receive the Key Facts Statement (KFS) and loan agreement.
-
The APR and repayment schedule are clear.
-
The privacy policy explains what information is collected and why.
-
A grievance redressal mechanism is available.
Under applicable RBI digital-lending requirements, regulated lenders must follow relevant disclosure, data-consent and creditworthiness-assessment rules. Review the latest official guidance because regulatory requirements can change.
Never share your OTP, UPI PIN, ATM PIN or internet-banking password with a loan agent or an unverified app.
9. Challenges Freelancers May Still Face in 2027
Even as digital services evolve, some challenges may remain:
Irregular income: A gap between projects can make monthly earnings unpredictable.
Limited documentation: Freelancers who do not maintain organized financial records may find verification more difficult.
Short credit history: New borrowers may have less repayment history for lenders to evaluate.
High existing debt: Multiple EMIs can reduce the amount of additional borrowing that may be affordable.
Different lender policies: Some products may have minimum income, work-experience or documentation requirements that an applicant does not meet.
These challenges do not automatically disqualify every freelancer. The appropriate next step is to review the lender’s stated criteria and address gaps where possible.
10. 2027 Outlook: What Freelancers Should Expect
The broader growth of digital work and financial technology may create opportunities for more convenient loan applications. Yet access to a digital application is different from qualifying for credit.
For freelancers in Tier-2 cities, the most useful strategy is to focus on financial readiness rather than expecting a particular technology or policy change to guarantee approval.
| Area | Possible direction by 2027 | What freelancers can do now |
|---|---|---|
| Digital applications | More convenient online journeys may emerge | Keep documents ready |
| Income verification | Digital checks may become more streamlined | Maintain clear income records |
| Credit assessment | Verified financial data may support assessment | Keep bank and credit records accurate |
| Loan comparison | Online discovery may make comparisons easier | Compare APR and total repayment |
| Loan safety | Disclosures and data protection remain important | Verify the lender and read the KFS |
This outlook is forward-looking and should not be treated as a prediction of guaranteed changes or an assurance of loan eligibility.
Key Takeaways
-
Freelancers in Tier-2 cities may be able to apply for personal loans, depending on lender eligibility criteria.
-
Digital lending may improve application convenience, but approval is not guaranteed.
-
Bank statements, invoices, ITRs where applicable and other income records may help demonstrate earnings.
-
Credit history and existing EMIs can influence the lender’s assessment.
-
Consistent financial records can make income verification easier.
-
Compare the APR, fees, EMI and total repayment before accepting an offer.
-
Verify the actual lender and review the KFS and loan agreement.
-
Future lending trends may change; always check the latest product terms and applicable rules.
FAQs
1. Will freelancer loan eligibility improve in 2027?
Digital application and verification processes may become more convenient, but eligibility will depend on the lender’s policies, the borrower’s financial profile and applicable regulations.
2. Can freelancers in Tier-2 cities apply for personal loans?
Yes, where lenders offer suitable products and the applicant meets their eligibility criteria. Location alone does not guarantee approval.
3. Will freelancers need salary slips in 2027?
Not necessarily. Some lenders may accept alternative income evidence, such as bank statements, invoices or tax documents, depending on their policies.
4. Can I get a loan without an ITR?
Requirements vary by lender and loan product. Some may accept other income records, while others may require ITRs or additional documents.
5. Will AI make freelancer loan approval instant?
Automated systems may speed up certain checks, but final approval can still require verification and lender assessment.
6. Does a high CIBIL score guarantee a loan?
No. Income, existing debt, documentation, the requested amount and lender-specific rules can also affect approval.
7. How can freelancers prove their income?
They may use bank statements, client invoices, payment receipts, contracts, ITRs where applicable and other documents accepted by the lender.
8. Can irregular income lead to loan rejection?
It can affect an assessment if the lender cannot establish sufficient repayment capacity. The result depends on the applicant’s full financial profile and the lender’s criteria.
9. What should freelancers check before accepting a digital loan?
Review the actual lender, APR, processing fees, EMI, total repayment, KFS, loan agreement, privacy terms and grievance redressal details.
10. Should freelancers wait until 2027 to apply for a loan?
Not solely because of expected future trends. If credit is needed now, compare currently available legitimate options and borrow only when repayment is affordable.
Conclusion
The 2027 outlook for freelancer loan eligibility in Tier-2 cities points toward the possibility of more convenient digital applications and evolving ways to verify income. But technology alone cannot replace a sound financial profile.
Freelancers can prepare by maintaining accurate income records, monitoring their credit history, managing existing EMIs and comparing loan terms carefully. These habits can help them make better borrowing decisions as lending services continue to evolve.
Published on : 27th October 2026
Published by : Shibam nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed