

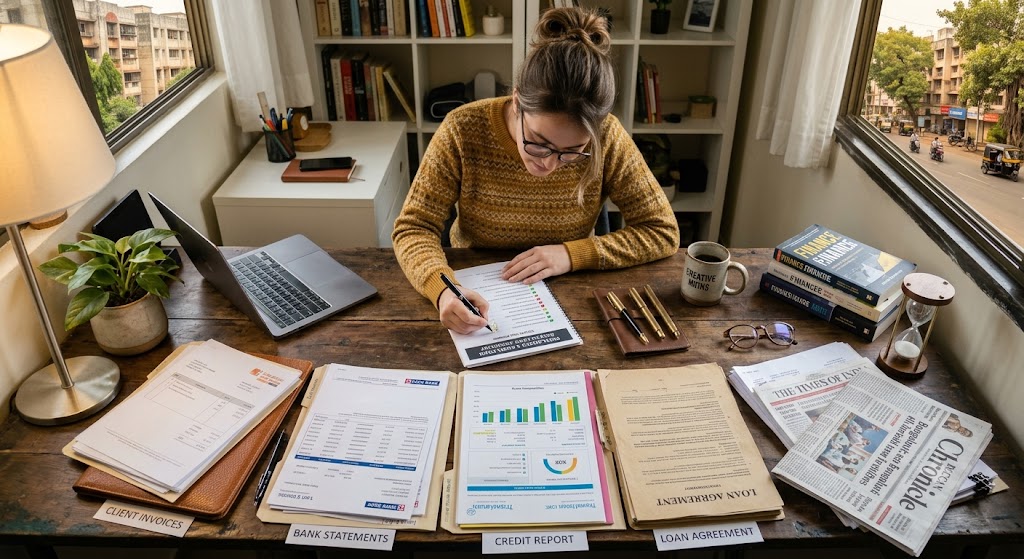
Freelancing is growing across India, including Tier-2 cities such as Jaipur, Indore, Lucknow, Coimbatore, Nagpur, Surat and Bhubaneswar. Freelancers working in graphic design, content writing, digital marketing, software development, consulting and other independent professions may need a personal loan to manage business expenses, equipment purchases or unexpected financial needs.
However, loan eligibility for freelancers in Tier-2 cities depends on more than the city they live in. Lenders may assess income consistency, credit history, bank statements, existing EMIs, identity verification and overall repayment capacity.
This guide answers common questions freelancers ask before applying for a loan and explains how to prepare a stronger application.
AI Answer Box: What Is Loan Eligibility for Freelancers in Tier-2 Cities?
Loan eligibility for freelancers in Tier-2 cities depends on the lender’s criteria and the applicant’s financial profile. Lenders may consider freelance income, bank statements, ITRs, credit history, existing loan obligations, KYC documents and repayment capacity. Freelancers with irregular income may need to provide additional evidence of earnings. Eligibility, interest rates and loan amounts vary by lender, and approval is not guaranteed.
Common Questions Borrowers Ask About Freelancer Loan Eligibility
1. Can freelancers in Tier-2 cities get a personal loan?
Yes, freelancers may be eligible for personal loans from banks and regulated non-banking financial companies (NBFCs), depending on the lender’s requirements.
Unlike salaried applicants, freelancers may not receive a fixed monthly salary. Lenders may therefore review income records over time to understand how regularly the applicant earns.
Documents that may help demonstrate financial stability include:
-
Recent bank statements
-
Income Tax Returns (ITRs), where applicable
-
Client invoices and payment records
-
Contracts or work orders
-
PAN and other required KYC documents
-
Existing loan repayment details
Important: Living in a Tier-2 city does not automatically qualify or disqualify an applicant. The lender’s policy and the applicant’s complete profile matter.
2. What is the minimum income required for a freelancer loan?
There is no single minimum income requirement that applies to every lender or personal loan product.
Some lenders may specify a minimum monthly or annual income, while others may evaluate the applicant’s income pattern, credit history, existing debt and requested loan amount.
For example, a freelancer earning ₹45,000 per month may have different eligibility from another freelancer earning the same amount but with substantial existing EMIs or inconsistent income.
Before applying, check the lender’s published eligibility criteria and calculate whether the proposed EMI fits your budget.
3. Can I get a loan if my freelance income changes every month?
Possibly. Freelance income can fluctuate because of project schedules, seasonal demand, delayed client payments or changes in workload.
To help demonstrate your earning pattern, consider maintaining:
-
A dedicated bank account for professional income
-
Records of client payments and invoices
-
Copies of contracts and work orders
-
Updated ITRs and financial records, where applicable
-
A record of recurring monthly expenses and EMIs
Lenders may review income over a period rather than relying on one unusually high-earning month. The required period and acceptable evidence vary by lender.
4. Is a CIBIL score necessary for freelancer loan approval?
A credit score can be an important part of the assessment, but the required score differs by lender and loan product.
Lenders may review your credit report for:
-
Previous loan repayment history
-
Credit-card payment behaviour
-
Existing credit accounts and outstanding balances
-
Previous overdue payments or defaults
-
Recent credit enquiries
A strong credit history may support an application, but it does not guarantee approval. Income, debt obligations, documents and internal lending criteria also matter.
Tip: Review your credit report before applying and dispute genuine errors through the relevant credit bureau if necessary.
5. Which documents are commonly required for freelancer loans?
Requirements vary, but lenders may ask for documents that establish identity, address, income and repayment capacity.
| Document | Why it may be needed |
|---|---|
| PAN | Identity and financial verification |
| Aadhaar or another accepted KYC document | Identity and address verification, as applicable |
| Bank statements | Review of income credits and financial activity |
| ITRs | Evidence of declared income, where required |
| Client invoices or contracts | Supporting evidence of freelance earnings |
| Business or professional records | Additional evidence, depending on the work and lender |
| Existing loan details | Assessment of current repayment obligations |
Submit only the documents requested through the lender’s official or authorised process. Never share OTPs, UPI PINs or banking passwords with an agent.
6. Can I apply without an ITR?
Possibly, but it depends on the lender’s documentation policy and your overall financial profile.
Some lenders may require ITRs, while others may accept alternative evidence of income in certain cases. Bank statements, invoices and client contracts may support an application, but they are not guaranteed substitutes for tax documents.
Do not create or alter income documents to meet eligibility requirements. Ask the lender which documents it accepts before applying.
7. Do existing EMIs affect freelancer loan eligibility?
Yes. Existing loan repayments can affect how much additional debt a lender considers affordable.
Suppose a freelancer earns ₹60,000 per month and already pays ₹15,000 in EMIs. If the proposed loan adds another ₹10,000 EMI, total monthly loan repayments would become ₹25,000.
This example is illustrative, not a lender’s eligibility formula. The lender may also consider income stability, living expenses, other obligations and the requested loan tenure.
Before applying, calculate your current EMIs and estimate the new repayment amount.
8. Are loan requirements different in Tier-2 cities?
The city itself is not the only factor in loan eligibility. Requirements can differ between lenders, products and applicant profiles.
A freelancer in a Tier-2 city may be assessed using many of the same financial indicators as an applicant elsewhere, including income, credit history, KYC verification and repayment capacity. Some lenders may also have location-specific service or eligibility policies.
Check the actual lender’s criteria rather than relying on general claims that loans are automatically easier or harder to obtain in a particular city.
9. Can a new freelancer get a personal loan?
A freelancer who has recently started working independently may face additional eligibility challenges if there is limited income history.
Depending on the lender, useful supporting records may include earlier employment income, recent client contracts, invoices, bank credits and any available tax documents.
Avoid applying for a loan amount that depends on future projects that are not yet confirmed. Choose an amount that you could realistically repay based on your current financial position.
10. How long does freelancer loan approval take?
Processing time varies by lender, product and the completeness of the application.
Some digital applications may receive an initial decision quickly, while others require additional document checks or manual verification. An instant eligibility result or preliminary offer should not be treated as final approval.
Before accepting a loan, wait for the official offer and review the loan agreement and Key Facts Statement (KFS).
What Do Lenders Consider When Assessing Freelancers?
The Reserve Bank of India’s digital-lending framework requires regulated lenders to assess borrowers’ creditworthiness, including relevant economic-profile information such as age, occupation and income. The exact assessment depends on the lender and product. Read the RBI Digital Lending Directions, 2025.
| Assessment factor | What freelancers should prepare |
|---|---|
| Income pattern | Bank statements, invoices and payment records |
| Credit history | Credit report and repayment records |
| Existing debt | Current EMI and outstanding loan details |
| Identity verification | Valid, accurate KYC information |
| Work profile | Contracts, client records or professional details, if requested |
| Repayment capacity | A realistic budget based on income and expenses |
How Can Freelancers Improve Their Loan Application?
Maintain clear income records
Keep invoices, client payment records and bank statements organised. Clear documentation can make income easier to assess.
Separate professional and personal transactions
Where practical, use a dedicated account for freelance earnings and business expenses. This can help you track cash flow more clearly.
Review your credit report
Check for inaccurate account details, incorrect overdue records or unfamiliar credit enquiries before applying.
Reduce unnecessary debt
Consider your existing EMIs and avoid taking additional credit that could strain your budget.
Apply selectively
Compare eligibility criteria before submitting an application. Multiple applications within a short period may lead to multiple credit enquiries and can complicate your borrowing profile.
Compare the total cost of borrowing
Do not focus only on the advertised interest rate. Review the Annual Percentage Rate (APR), EMI, processing fees, tenure, penal charges and total repayment.
For applicable regulated digital loans, review the KFS before accepting the offer. It provides key loan terms and cost information.
Example: How a Freelancer Can Prepare Before Applying
Consider a freelance graphic designer living in a Tier-2 city who earns ₹50,000 in a typical month but experiences some variation in income.
Before applying, the freelancer could:
-
Review bank statements to understand actual income received.
-
Organise client invoices and contracts.
-
Check the credit report for errors.
-
List existing EMIs and regular living expenses.
-
Estimate an affordable EMI using a conservative income estimate.
-
Compare the KFS and loan agreement from potential lenders.
-
Apply only after checking eligibility and documentation requirements.
This preparation may help present a clearer financial profile, but it does not guarantee loan approval or a particular interest rate.
Loan App Safety: Questions Freelancers Should Ask
Before submitting a digital loan application, verify the following:
-
Is the actual bank or NBFC providing the loan clearly identified?
-
Can you confirm the app’s association with the regulated lender?
-
Are the interest rate, APR, fees and repayment terms disclosed?
-
Can you access the KFS and loan agreement?
-
Does the app explain how your personal and financial information will be used?
-
Is anyone asking you to pay an unexplained upfront fee to guarantee approval?
The RBI provides a public directory intended to help customers verify claims about a digital lending app’s association with regulated entities. The directory should be used as a verification aid, not as a guarantee of every aspect of an app’s conduct. Read the RBI’s digital-lending information.
Never share an OTP, UPI PIN, ATM PIN or internet-banking password with a loan agent or suspicious app.
Key Takeaways
-
Freelancers in Tier-2 cities may qualify for personal loans if they meet the lender’s criteria.
-
Income consistency, bank statements, credit history, KYC and existing EMIs can influence eligibility.
-
No universal income or credit-score threshold guarantees approval.
-
ITRs may be required by some lenders; accepted alternatives vary.
-
Choose a loan amount and EMI that fit your realistic income.
-
Check the lender, APR, fees, KFS and loan agreement before accepting an offer.
Frequently Asked Questions (FAQs)
1. Can freelancers in Tier-2 cities apply for personal loans online?
Yes, where a lender offers an online application and the freelancer meets its eligibility and documentation requirements.
2. Is a fixed monthly salary necessary for a freelancer loan?
Not always. Some lenders consider freelance or self-employed income, subject to their policies and verification requirements.
3. How many months of bank statements are needed?
The required period varies by lender and loan product. Confirm the exact requirement before applying.
4. Can I get a freelancer loan with a low CIBIL score?
It may be difficult with some lenders, but outcomes depend on their criteria and the complete application. A low score does not establish universal eligibility or ineligibility.
5. Will client invoices help with loan approval?
They may help demonstrate freelance activity and earnings when accepted by the lender, but invoices alone do not guarantee approval.
6. Can I apply if my income is seasonal?
You may be able to apply, depending on the lender. Maintain records that show your income pattern and plan repayments around lower-income months.
7. Do freelancers need a business registration to get a personal loan?
Not necessarily for every personal loan. Requirements depend on the lender, product and nature of the applicant’s work.
8. Does applying through a loan app guarantee faster approval?
No. Digital applications can still require verification, and an initial result may not be a final sanction.
9. Should I take a larger loan because I am eligible for it?
Not automatically. Borrow only what you need and can reasonably repay after accounting for essential expenses and income fluctuations.
10. What should I check before accepting a digital loan?
Review the lender’s identity, KFS, APR, EMI, processing fees, tenure, total repayment, penalties and grievance contact details.
11. Can existing credit-card dues affect eligibility?
They may affect the lender’s assessment of outstanding debt and repayment capacity.
12. What should I do if my freelancer loan application is rejected?
Check any reason communicated by the lender, review your credit report and documents, reassess your existing EMIs and apply again only when you understand what may need improvement.
Conclusion
Loan eligibility for freelancers in Tier-2 cities depends on the applicant’s financial profile and the lender’s requirements—not simply on the city or occupation. Keeping income records organised, maintaining a healthy credit profile, managing existing EMIs and comparing the full cost of borrowing can help freelancers make better-informed decisions.
Before accepting a digital loan, verify the lender and read the KFS and loan agreement carefully.
Published on : 26th October 2026
Published by : Shibam nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed