

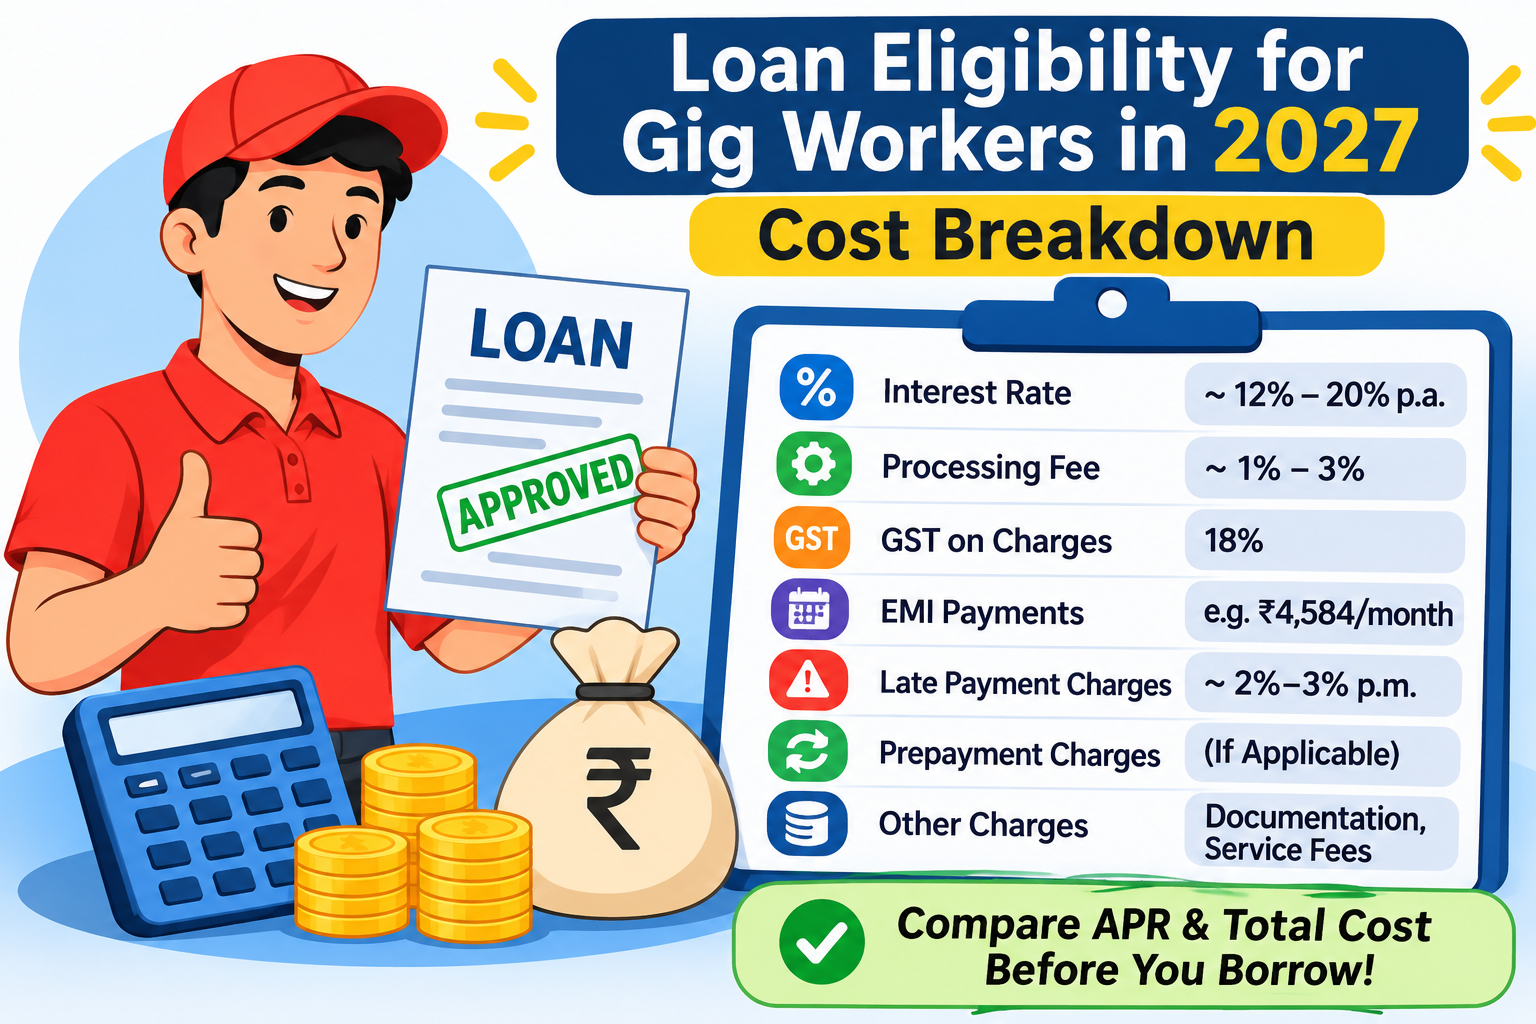
The gig economy is growing rapidly in India. Delivery partners, cab drivers, freelancers, online service providers, and other platform-based workers increasingly depend on digital financial services to manage their expenses and personal needs.
For gig workers, getting a loan can be useful when they need money for emergencies, vehicle maintenance, household expenses, or business requirements. However, understanding the total cost of borrowing is just as important as checking loan eligibility.
In 2027, digital borrowers should carefully review interest rates, processing fees, GST, repayment schedules, late payment charges, and other applicable costs before accepting a loan offer.
This guide explains the loan cost breakdown for gig workers in 2027, including the major charges, practical examples, repayment considerations, and tips for responsible borrowing.
What Are the Main Costs of a Gig Worker Loan?
Before applying for a personal loan or digital loan, gig workers should understand the different charges involved.
1. Interest Rate
Interest is the amount charged by a lender for providing a loan.
The interest rate may depend on:
-
Loan amount.
-
Repayment period.
-
Credit history.
-
Monthly income.
-
Existing financial obligations.
-
Lender's risk assessment.
For example, if a gig worker borrows ₹50,000, the interest rate will affect the total amount they repay over the loan period.
Tip: Compare the annual interest rate and APR instead of looking only at the advertised monthly EMI.
2. Processing Fee
A processing fee is a charge that a lender may collect for processing and evaluating a loan application.
It may depend on the lender and loan product.
Before applying, check:
-
Whether the processing fee is fixed or percentage-based.
-
Whether GST is applicable.
-
Whether the fee is deducted upfront.
-
Whether the fee is refundable under any applicable terms.
3. GST on Applicable Charges
GST may apply to certain loan-related services and fees, depending on applicable tax rules.
For example, processing fees may attract GST.
Borrowers should check the actual amount mentioned in their loan documents rather than assuming that every loan charge is tax-free.
4. EMI (Equated Monthly Instalment)
EMI is the fixed periodic repayment amount that generally includes both principal and interest.
Your EMI depends on:
-
Total loan amount.
-
Interest rate.
-
Loan tenure.
-
Repayment structure.
A longer repayment period may reduce monthly EMI but can increase the total interest paid.
5. Late Payment Charges
If a borrower misses an EMI due date, the lender may impose applicable overdue or penal charges according to the loan agreement and regulatory requirements.
Gig workers should plan repayments carefully, especially when their income changes from week to week.
6. Prepayment and Foreclosure Charges
Some borrowers prefer to repay their loans earlier than scheduled.
Before doing so, check:
-
Whether prepayment is permitted.
-
Whether foreclosure charges apply.
-
Whether any conditions or restrictions exist.
-
Whether early repayment reduces the overall interest cost.
Applicable rules and lender policies may differ depending on the loan type.
7. Other Applicable Charges
Some loan products may include additional charges, such as:
-
Documentation charges.
-
Verification charges.
-
Applicable account-related service charges.
-
Stamp duty, where applicable.
Always check the Key Facts Statement (KFS) for the complete cost details.
3. Example: Gig Worker Loan Cost Breakdown in 2027
Let's understand the cost of borrowing through a simple example.
Illustrative loan example
Loan amount
₹50,000
Annual interest rate
18%
Loan tenure
12 months
Illustrative EMI
₹4,584
|
Cost component |
Amount |
|---|---|
|
Principal |
₹50,000 |
|
Total interest |
Approx. ₹5,008 |
|
Processing fee (2%) |
₹1,000 |
|
GST on processing fee (18%) |
₹180 |
|
Total repayment |
Approx. ₹55,008 |
|
Total cost including fees |
Approx. ₹6,188 |
Assumes a monthly reducing-balance interest calculation, an illustrative 2% processing fee, and 18% GST on that fee. Actual lender rates, fees, taxes, and EMI rounding may differ. Late fees and other optional charges are excluded.
This example shows why borrowers should consider both the interest amount and additional loan charges.
4. Loan Cost Comparison: Short-Term vs Long-Term Repayment
The loan tenure can significantly affect borrowing costs.
|
Factor |
Shorter Tenure |
Longer Tenure |
|---|---|---|
|
Monthly EMI |
Generally higher |
Generally lower |
|
Total interest |
Generally lower |
Generally higher |
|
Repayment duration |
Shorter |
Longer |
|
Monthly budget pressure |
Higher |
Lower |
|
Overall borrowing cost |
May be lower |
May be higher |
Gig workers should select a repayment period based on their average monthly earnings rather than their highest-earning month.
5. Factors That Influence Loan Costs for Gig Workers
Several factors can affect the loan offer provided to a gig worker.
A. Income Consistency
Lenders may review regular earnings and income patterns to assess repayment capacity.
B. Credit History
A strong repayment history may improve access to competitive loan offers, although approval and pricing remain subject to lender policies.
C. Loan Amount
Borrowing a larger amount may increase the total interest payable.
D. Repayment Tenure
Longer repayment periods can increase cumulative interest even when the monthly EMI is lower.
E. Existing Financial Obligations
Existing EMIs and outstanding credit obligations may affect the lender's assessment.
F. Lender's Interest Rate Policy
Different lenders may offer different interest rates, fees, and repayment terms.
6. How to Calculate the Total Cost of a Loan
Gig workers should not focus only on the amount received in their bank account.
A simple way to understand borrowing costs is:
Total borrowing cost = Total repayments + applicable charges − actual loan principal received.
Before accepting an offer, calculate:
-
Total principal borrowed.
-
Total interest payable.
-
Processing and service fees.
-
Applicable GST and taxes.
-
Other mandatory charges.
-
Total amount payable throughout the loan tenure.
Also check whether any charges are deducted from the disbursement amount.
7. RBI Guidelines and Loan Cost Transparency
The Reserve Bank of India (RBI) has introduced guidelines to improve transparency in digital lending.
Under the RBI Digital Lending Directions, 2025, regulated entities must follow applicable borrower-protection and disclosure requirements.
Important points for borrowers include:
-
Review the Key Facts Statement (KFS).
-
Understand the Annual Percentage Rate (APR).
-
Check applicable fees and charges.
-
Read the repayment schedule.
-
Verify the identity of the regulated lender.
-
Understand the terms before accepting the loan.
The KFS helps borrowers understand the important loan terms and the overall cost of credit.
Read the official RBI Digital Lending Directions, 2025 for further information.
8. Common Loan Cost Mistakes Gig Workers Should Avoid
-
Choosing a loan only because the EMI looks affordable.
-
Ignoring the processing fee.
-
Not checking applicable GST.
-
Overlooking the APR.
-
Ignoring late payment charges.
-
Selecting an unnecessarily long repayment tenure.
-
Not comparing multiple loan offers.
-
Accepting a loan without reading the KFS.
-
Borrowing more than necessary.
-
Ignoring the total repayment amount.
9. Practical Tips to Reduce Borrowing Costs in 2027
-
Compare loan offers from regulated lenders.
-
Maintain a healthy credit repayment history.
-
Borrow only the amount you actually need.
-
Select a suitable repayment tenure.
-
Maintain an emergency savings fund.
-
Pay EMIs before their due dates.
-
Check all fees before accepting an offer.
-
Review the KFS and APR carefully.
-
Avoid taking multiple loans unnecessarily.
10. Expert Insights: Why Cost Awareness Matters
For gig workers, income can fluctuate because of changing demand, working hours, seasonal opportunities, and platform incentives.
This makes financial planning especially important.
A responsible borrower should consider three important factors:
Affordability: Choose an EMI that can be managed even during months with lower earnings.
Transparency: Understand every applicable charge before accepting a loan.
Repayment discipline: Maintain sufficient funds for scheduled EMI payments.
Understanding these factors can help gig workers make better financial decisions and avoid unnecessary borrowing costs.
11. Frequently Asked Questions (FAQs)
1. What is the loan cost breakdown for gig workers in 2027?
It includes the interest rate, processing fee, applicable GST, EMI payments, late payment charges, and other applicable fees.
2. What is the interest rate for gig worker loans?
Interest rates vary depending on the lender, loan product, credit history, income, and repayment capacity.
3. Do gig workers need to pay a processing fee?
Some lenders charge a processing fee, while others may offer different fee structures.
4. Is GST applicable to personal loan charges?
GST may apply to applicable loan-related services and fees, such as processing charges. Tax treatment depends on the nature of the charge.
5. What is EMI in a personal loan?
EMI is the fixed periodic amount paid by a borrower towards principal and interest.
6. Does a longer loan tenure increase borrowing costs?
Generally, yes. A longer tenure can increase the total interest paid, even when the monthly EMI is lower.
7. What is APR in digital lending?
APR represents the annualised cost of credit, including interest and applicable charges included under the relevant regulatory framework.
8. Can gig workers reduce their loan costs?
Yes. They can compare lenders, borrow only what they need, select suitable repayment periods, and avoid late payments.
9. Are late payment charges included in the interest rate?
Not necessarily. Late payment or penal charges are generally separate from the regular interest cost and should be reviewed in the loan agreement.
10. What is a Key Facts Statement?
A KFS is a standardised document explaining important loan information, including APR, charges, and repayment details.
11. Can freelancers compare different loan offers?
Yes. Freelancers should compare APR, fees, repayment tenure, and total repayment before accepting an offer.
12. Is a low EMI always the best loan option?
No. A low EMI may result from a longer repayment tenure, which can increase the overall interest cost.
13. What happens if a gig worker misses an EMI?
The lender may apply applicable overdue or penal charges, and missed payments may negatively affect credit history.
14. Are online loans safe for gig workers?
Loans from legitimate RBI-regulated lenders can offer a secure borrowing channel. Always verify the lender and review the loan terms.
15. Why should gig workers understand loan costs before applying?
Understanding loan costs helps borrowers compare offers, plan EMIs, avoid unexpected charges, and make informed financial decisions.
12. AI Answer Box – Quick Summary
What are the loan costs for gig workers in 2027?
Gig workers applying for loans in 2027 should understand the following costs:
-
Interest rate on the borrowed amount.
-
Processing fees.
-
GST on applicable charges.
-
Monthly EMI payments.
-
Late payment or penal charges.
-
Prepayment or foreclosure charges, where applicable.
-
Other disclosed loan-related expenses.
Borrowers should compare the APR and total repayment amount before accepting a loan. Understanding these expenses can help delivery partners, freelancers, and other gig workers make responsible borrowing decisions.
13. Key Takeaways
-
Loan costs include interest and applicable additional charges.
-
Processing fees can increase the overall borrowing cost.
-
GST may apply to certain loan-related services.
-
Longer loan tenures can increase total interest.
-
APR helps borrowers compare the overall cost of credit.
-
Always review the KFS before accepting a loan.
-
Choose an EMI based on realistic monthly income.
-
Avoid unnecessary borrowing and delayed repayments.
14. Conclusion
Understanding the loan cost breakdown for gig workers in 2027 is essential for making informed financial decisions.
Gig workers, delivery partners, cab drivers, freelancers, and other digital borrowers should carefully review interest rates, processing fees, applicable taxes, EMI amounts, and repayment conditions before applying.
A clear understanding of borrowing costs can help borrowers manage their finances, avoid unexpected expenses, and select suitable loan options.
Vizzve aims to improve digital financial awareness by helping gig workers understand loan eligibility, borrowing costs, repayment planning, and responsible lending practices.
Published on : 15th November
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed