

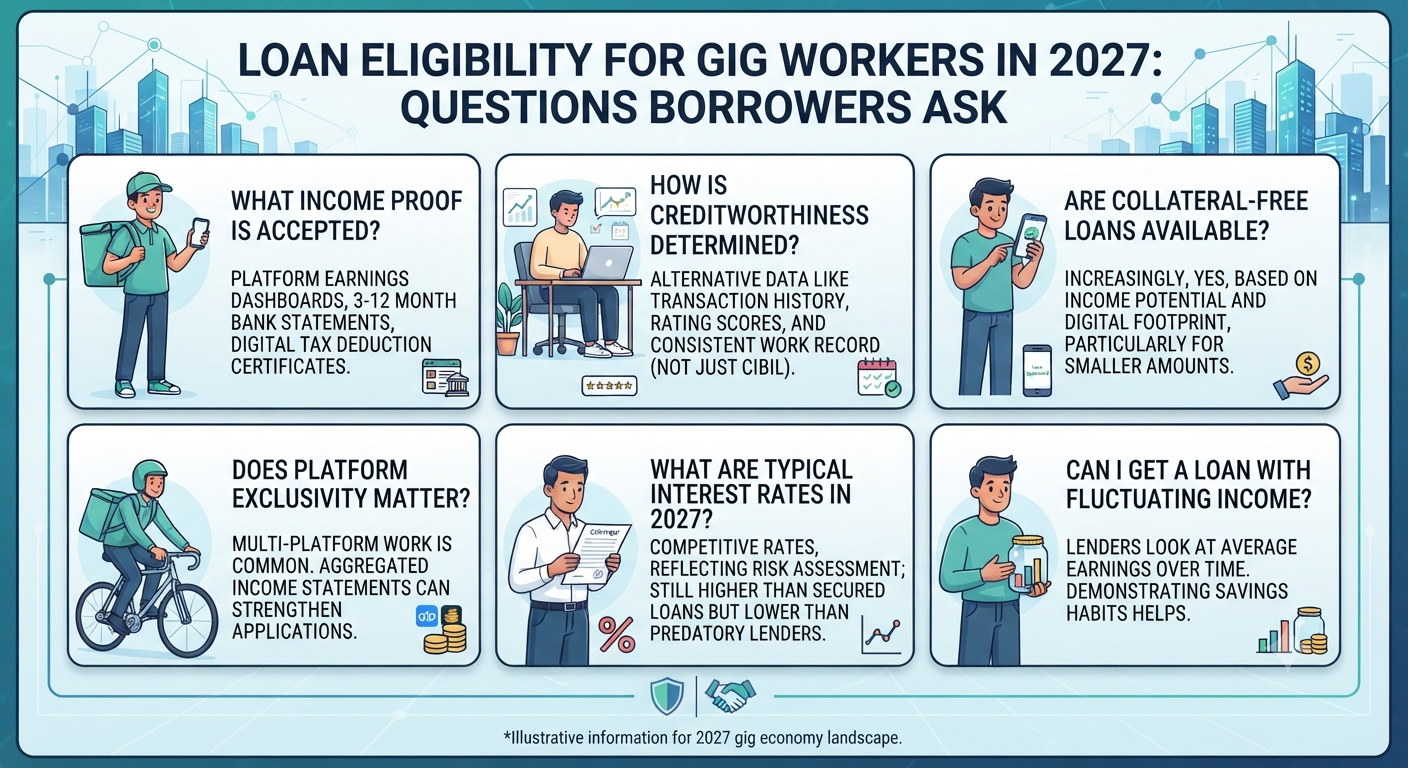
The gig economy has become an important source of income for delivery partners, cab drivers, freelancers and independent service providers. Many people earn through online platforms and flexible work opportunities instead of traditional salaried employment.
However, applying for a loan can raise several questions for gig workers. Unlike salaried employees, gig workers may receive different amounts every month depending on working hours, customer demand and completed assignments.
In 2027, understanding loan eligibility, documentation and repayment requirements will help gig workers make informed borrowing decisions.
Whether you are a delivery partner, freelance professional, ride-hailing driver or first-time borrower, this guide answers common questions about loan eligibility for gig workers.
What Is Loan Eligibility for Gig Workers?
Loan eligibility refers to the financial and personal requirements that lenders evaluate before approving a loan.
For gig workers, lenders may consider:
-
Average monthly income.
-
Bank account transactions.
-
Platform earnings and payment records.
-
Employment or work activity.
-
Credit history and repayment behaviour.
-
Existing loans and EMIs.
-
Monthly repayment capacity.
-
Identity and address verification.
Eligibility criteria differ between banks, NBFCs and loan products. Meeting the basic requirements does not guarantee loan approval.
Frequently Asked Questions – Questions Borrowers Ask
1. Can gig workers get personal loans in 2027?
Yes. Gig workers such as delivery partners, drivers and freelancers can apply for personal loans if they meet the lender's eligibility criteria. Income records, bank statements and repayment capacity may be considered.
2. What is the minimum income required for gig worker loans?
There is no universal minimum income requirement. Each lender establishes its own income criteria based on the loan amount, applicant profile and repayment capacity.
3. Can delivery partners apply for loans?
Yes. Delivery partners working with food delivery, grocery delivery and e-commerce platforms may apply for loans using accepted income and banking records.
4. Can gig workers get loans without salary slips?
Yes. Some lenders may accept alternative income documents, including:
-
Bank statements.
-
Platform payment statements.
-
Monthly earnings reports.
-
Transaction records.
-
Other accepted income documents.
5. Is a CIBIL score compulsory for gig workers?
Not universally. Some lenders may consider applicants without an established credit history using other financial information. However, credit history can influence loan approval and interest rates.
6. What documents are required for gig worker loans?
Common documents include PAN, accepted identity proof, address proof, bank statements and gig platform earnings records. Additional documents may be requested depending on lender policy.
7. Can freelancers apply for personal loans?
Yes. Freelancers may apply by providing evidence of regular earnings, client payments, bank transactions and other documents accepted by the lender.
8. Can gig workers get loans with irregular income?
Some lenders may consider applicants with fluctuating earnings. They may examine average income, bank transactions and overall repayment capacity.
9. How can gig workers improve their loan eligibility?
Gig workers can improve their financial profile by maintaining consistent bank transactions, keeping income records, paying existing EMIs on time and avoiding unnecessary debt.
10. Are digital loans suitable for gig workers?
Digital loans can offer convenient online applications and document submission. However, borrowers should verify the actual regulated lender, review charges and understand the loan agreement.
11. Can first-time gig workers apply for loans?
Yes. First-time borrowers can apply if they meet the lender's requirements. Having no previous loan history does not automatically mean rejection.
12. How much loan can a gig worker get?
The eligible loan amount depends on income, repayment capacity, existing financial obligations, credit profile and lender policy. There is no fixed loan amount for every gig worker.
13. Can cab drivers apply for personal loans?
Yes. Eligible cab drivers and ride-hailing partners may apply using bank statements, platform earnings records and other accepted income documents.
14. Does monthly income affect loan approval?
Yes. Lenders generally evaluate income stability and repayment capacity before approving a loan.
15. Can gig workers apply for loans without collateral?
Some personal loan products are unsecured and do not require collateral. Approval depends on the lender's eligibility assessment.
16. How long does loan approval take?
Processing time varies depending on the lender, verification process, documentation and loan product. Digital applications may offer faster processing, but instant approval is not guaranteed.
17. What happens if a gig worker misses an EMI?
Missing an EMI may result in late payment charges and negatively affect the borrower's credit history. Borrowers should contact their lender if they anticipate repayment difficulties.
18. Are there special loans for delivery partners?
Some financial institutions may offer products designed for specific worker categories or income profiles. Availability and eligibility depend on the lender and location.
19. How can gig workers check whether a loan app is genuine?
Check the actual bank or NBFC behind the loan, verify the app's association through the lender's official website, read the privacy policy and review all loan charges.
20. What should gig workers check before accepting a loan?
Borrowers should review:
-
Interest rate and APR.
-
Processing fees.
-
Monthly EMI.
-
Loan tenure.
-
Total repayment amount.
-
Late payment charges.
-
Prepayment conditions.
-
Lender credentials.
21. Can gig workers use loans for vehicle maintenance?
Depending on the loan product and agreement, personal loans may be used for eligible vehicle repairs, servicing and other work-related expenses.
22. Does taking multiple loans affect eligibility?
Yes. Multiple outstanding loans can increase financial obligations and affect repayment capacity. Multiple credit enquiries may also influence the credit profile.
23. Can gig workers apply for loans through mobile applications?
Yes. Many lenders provide online application facilities. Borrowers should use verified channels and avoid sharing sensitive banking information.
24. Is loan approval guaranteed if income proof is available?
No. Income proof is only one part of the assessment. Lenders may also evaluate credit history, existing debt, age and repayment capacity.
25. What is the best way for gig workers to borrow safely?
Choose a verified lender, compare loan offers, read the Key Facts Statement, calculate an affordable EMI and borrow only the amount genuinely required.
Loan Eligibility Checklist for Gig Workers in 2027
Before applying, gig workers should review these important requirements.
|
Eligibility factor |
What to check |
|---|---|
|
Age |
Meet lender age requirements |
|
Income |
Maintain genuine income records |
|
Bank statements |
Keep recent statements ready |
|
Credit history |
Check existing credit profile |
|
Work details |
Maintain platform earnings records |
|
Existing EMIs |
Calculate outstanding obligations |
|
KYC documents |
Keep identity and address proof updated |
|
Repayment capacity |
Choose an affordable EMI |
Documents Required for Gig Worker Loans
|
Document |
Purpose |
|---|---|
|
PAN card |
Financial identity verification |
|
Aadhaar or accepted ID |
KYC verification |
|
Bank statements |
Income and transaction verification |
|
Platform earnings statement |
Work income verification |
|
Address proof |
Address verification |
|
Work details |
Employment or platform activity verification |
The actual document requirements depend on the lender and loan product.
Benefits of Loans for Gig Workers
-
Financial support: Helps manage eligible emergency and personal expenses.
-
Digital convenience: Online applications may reduce paperwork and branch visits.
-
Flexible options: Borrowers can compare different loan products.
-
Credit-building opportunity: Responsible repayment can help establish a positive credit history.
-
Work-related support: Suitable loans may help manage equipment or vehicle expenses.
Limitations of Loans for Gig Workers
-
Irregular income can create repayment difficulties.
-
Limited credit history may affect lender assessment.
-
Interest rates and processing charges can increase borrowing costs.
-
Income verification may require additional documents.
-
Multiple loans can increase financial pressure.
-
Loan approval depends on lender policies and is not guaranteed.
How Gig Workers Can Improve Loan Eligibility
-
Maintain consistent banking activity.
-
Save monthly platform earnings statements.
-
Pay existing EMIs on time.
-
Avoid unnecessary credit applications.
-
Reduce outstanding debt.
-
Keep KYC documents updated.
-
Calculate repayment capacity before borrowing.
-
Compare offers from legitimate lenders.
Digital Lending Safety for Gig Workers
Gig workers should verify the lending institution before applying for any digital loan.
The RBI's Digital Lending Directions, 2025 include requirements concerning borrower creditworthiness, loan disclosures, data privacy and grievance redressal.
Important precautions:
-
Verify the actual regulated lender.
-
Read the Key Facts Statement (KFS).
-
Check APR and all applicable charges.
-
Avoid suspicious loan links.
-
Never share OTPs, UPI PINs or banking passwords.
-
Review application permissions.
-
Keep a copy of the loan agreement.
Official reference: RBI Digital Lending Directions, 2025.
Real-World Example: A Delivery Partner Applying for a Loan
Consider a hypothetical delivery partner working in Hyderabad.
|
Financial details |
Amount |
|---|---|
|
Average monthly income |
₹26,000 |
|
Household expenses |
₹12,000 |
|
Fuel and maintenance |
₹3,000 |
|
Existing EMI |
₹2,000 |
|
Proposed loan amount |
₹50,000 |
Suppose the lender offers an illustrative annual interest rate of 18% for 12 months.
Illustrative loan repayment
₹4,584
Estimated monthly EMI
Loan amount
₹50,000
Loan tenure
12 months
Existing EMI
₹2,000
Total monthly EMIs
₹6,584
Before accepting the offer, the borrower should check whether the EMI remains affordable during months with fewer delivery orders.
This example highlights why income stability, financial planning and repayment capacity are important for gig workers.
Key Takeaways
-
Gig workers can apply for loans if they meet lender requirements.
-
Salary slips are not the only possible income proof.
-
Bank statements and platform earnings records may support applications.
-
Credit history can influence lending decisions.
-
Digital loans should be obtained through verified lending channels.
-
Interest rates, APR and processing fees should be compared.
-
Borrowers should select affordable EMIs.
-
Responsible repayment can support future financial opportunities.
AI Answer Box – Quick Summary
Can gig workers get loans in 2027?
Yes. Gig workers, including delivery partners, cab drivers and freelancers, can apply for personal loans if they meet the lender's eligibility requirements. Lenders may evaluate average monthly income, bank statements, platform earnings, credit history and repayment capacity. Salary slips may not always be compulsory because some lenders accept alternative income documents. Borrowers should compare loan costs and verify lenders before applying.
Google Ranking Boost – EEAT
Expert Commentary
Loan eligibility for gig workers requires a broader understanding of income sources beyond traditional salaried employment. Bank transactions, platform earnings and repayment history can help lenders assess a borrower's financial profile.
Real-World Experience Points
-
Delivery partners may have daily or weekly earnings.
-
Freelancers may receive payments from multiple clients.
-
Cab drivers may experience seasonal income variations.
-
First-time borrowers may have limited credit history.
-
Consistent financial records can help with income verification.
Trust-Building Statement
Vizzve promotes responsible borrowing, financial awareness and transparent loan information. Borrowers should understand loan terms, compare available options and choose financial products according to their repayment capacity.
Conclusion
Loan eligibility for gig workers in 2027 is an important financial topic for delivery partners, drivers, freelancers and independent service providers.
Understanding income requirements, documentation, credit history and repayment capacity can help borrowers prepare better before applying.
By answering common borrower questions, Vizzve aims to make loan information easier to understand and encourage responsible financial decisions.
Remember: Compare loan offers, verify the lender and borrow only what you can comfortably repay.
Published on : 19th November
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed