

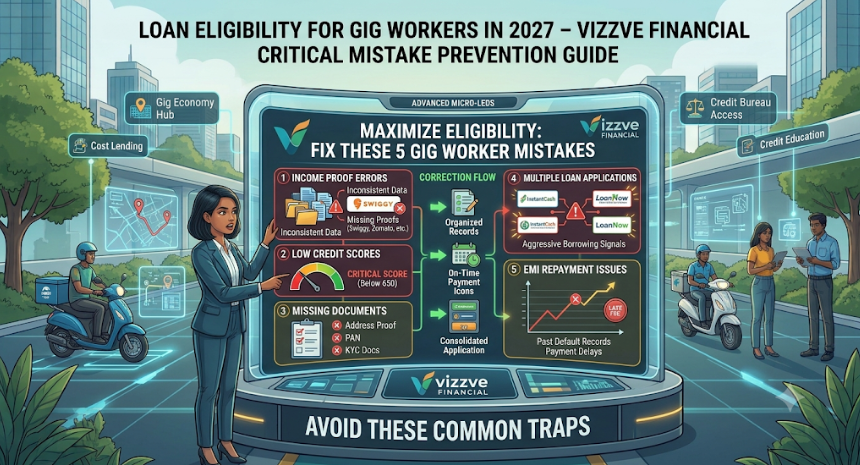
Introduction
India’s gig economy includes people working through delivery platforms, ride-hailing services, freelance marketplaces and other flexible work arrangements. Unlike salaried employees, many gig workers do not receive a fixed monthly salary or a traditional salary slip.
This can make personal loan applications more challenging. However, irregular income does not automatically mean a person is ineligible for a loan. Some lenders consider bank statements, platform payout records, invoices and other evidence of earnings.
The important thing is to present accurate financial information and choose a loan that matches your repayment capacity.
In 2027, gig workers should pay particular attention to the mistakes that can weaken an application. A small error, such as an incorrect monthly income figure or missing bank statement, may delay the process or lead to rejection.
AI Answer Box: What Are the Common Loan Eligibility Mistakes Gig Workers Should Avoid in 2027?
Gig workers should avoid these common mistakes when applying for a personal loan:
-
Reporting estimated income instead of actual earnings.
-
Failing to provide bank statements or platform payout records.
-
Applying without checking their credit report.
-
Ignoring existing EMIs and outstanding debts.
-
Applying to multiple lenders within a short period.
-
Choosing a loan amount they cannot comfortably repay.
-
Submitting incorrect personal or bank details.
-
Accepting loan offers without checking the interest rate, APR, fees and repayment terms.
Quick answer: Gig workers can improve their loan application by maintaining consistent banking records, documenting their earnings, reducing existing debt and selecting a lender that accepts their type of income.
Why Is Loan Eligibility Different for Gig Workers?
Traditional salaried employees usually provide salary slips, employment letters and Form 16 as income evidence. Gig workers may receive payments daily, weekly or monthly, depending on their platform, projects and working hours.
For example, a delivery partner may earn different amounts during weekdays and weekends. A freelance designer may receive three payments in one month and none in the next.
Lenders may therefore examine several factors together:
-
Average monthly income.
-
Consistency of bank credits.
-
Work history and earning pattern.
-
Existing loans and repayment obligations.
-
Credit history and repayment behaviour.
-
Age, identity and address verification.
-
The lender's own occupation and income policy.
There is no single universal income threshold or credit score that guarantees approval for every gig worker. Each regulated lender sets its own eligibility criteria.
Why is gig work becoming important in India's lending market?
NITI Aayog's report India's Booming Gig and Platform Economy estimated 7.7 million gig workers in 2020–21 and projected that the number could reach 23.5 million by 2029–30. These are estimates and projections from the report, not a confirmed count of workers in 2027.
As flexible work grows, lenders may encounter more applicants whose income does not fit the traditional monthly salary model. However, the availability of a loan still depends on the lender's underwriting policy.
15 Common Loan Eligibility Mistakes Gig Workers Should Avoid in 2027
1. Showing an Incorrect Monthly Income
One of the biggest mistakes is declaring a higher income than the amount actually earned.
Gig workers may calculate their income using their best earning week or busiest month. This can create an unrealistic picture of their regular financial position.
Example:
|
Month |
Actual earnings |
|---|---|
|
January |
₹22,000 |
|
February |
₹18,000 |
|
March |
₹20,000 |
|
April |
₹16,000 |
|
Four-month average |
₹19,000 |
In this example, the average monthly earning is ₹19,000, not ₹22,000.
How to avoid it:
-
Calculate average income over a reasonable period.
-
Use bank credits and platform payout statements.
-
Separate business expenses from personal income.
-
Do not inflate earnings to qualify for a larger loan.
2. Not Maintaining Proper Bank Statements
Cash withdrawals, wallet transfers and payments across several accounts can make income difficult to verify.
Some lenders may ask for recent bank statements to understand income and expenses.
How to avoid it:
-
Use one primary bank account for receiving work payments where practical.
-
Keep digital payout records.
-
Avoid unnecessary transfers between accounts.
-
Download and preserve statements regularly.
3. Not Providing Platform Payout Records
Delivery partners, drivers and online freelancers may have access to weekly or monthly earning statements.
These records can help explain where their income comes from.
Useful records may include:
-
Delivery or ride-hailing payout summaries.
-
Freelance invoices.
-
Client payment confirmations.
-
Work-platform transaction histories.
-
Bank statements showing corresponding credits.
The lender decides which documents it accepts. A platform statement does not automatically guarantee loan approval.
4. Ignoring Credit Score and Credit History
A credit report can show previous loans, credit card balances, repayment delays and other credit activity.
Some gig workers focus only on their current earnings and overlook their repayment history.
How to avoid it:
-
Review your credit report before applying.
-
Pay existing EMIs and credit card dues on time.
-
Check whether closed loans are correctly reported.
-
Raise disputes if you find inaccurate information.
-
Avoid using too much of your available credit.
A particular score does not guarantee approval. Lenders may consider several factors beyond the score.
5. Applying to Too Many Lenders at Once
Submitting several loan applications within a short period can lead to multiple lender enquiries on a credit report. This may affect how lenders assess a borrower's credit profile.
How to avoid it:
-
Check your eligibility before applying.
-
Compare lenders and loan terms.
-
Shortlist suitable offers.
-
Submit a formal application only after reviewing the conditions.
Remember that checking your own credit report is different from making several formal credit applications.
6. Choosing a Loan Amount That Is Too High
A larger loan may appear attractive, but the EMI must fit the borrower's actual income.
Gig workers should consider low-earning months, fuel costs, vehicle maintenance, platform charges and other essential expenses.
Example: A worker earning an average of ₹20,000 per month may find a ₹9,000 EMI difficult to manage if monthly expenses are already high.
How to avoid it:
-
Borrow only what you need.
-
Estimate your EMI before applying.
-
Keep room for essential expenses.
-
Consider income fluctuations before choosing a tenure.
7. Hiding Existing Loans or Credit Card Dues
Some applicants believe that not mentioning an existing loan will improve their eligibility. However, lenders may review credit bureau information and bank transactions.
Hiding obligations can create inconsistencies and weaken the application.
Better approach: Disclose existing loans accurately and calculate how much you can afford after paying current EMIs.
8. Submitting Incomplete or Incorrect Documents
An application may be delayed if the documents are missing, unclear or inconsistent.
Common examples include:
-
An outdated address.
-
A bank account number entered incorrectly.
-
Blurred identity documents.
-
Missing pages in bank statements.
-
Different names across records without supporting explanation.
-
Expired or invalid documents where current documents are required.
How to avoid it: Check every document before uploading it. Ensure that your personal details match the information in your application.
9. Not Explaining Irregular Income
Income changes are normal in gig work. A delivery partner may earn more during a festive period, while a freelancer may receive a large project payment in one month.
The mistake is submitting records without explaining unusual variations when the lender requests clarification.
How to avoid it:
-
Maintain several months of payout records.
-
Identify seasonal or one-time payments.
-
Provide supporting invoices or platform statements.
-
Report regular and occasional income separately.
10. Depending Only on Cash Income
Cash earnings may be legitimate, but they can be harder for a lender to verify than documented payments.
If a worker receives a significant part of their income in cash, they should maintain accurate records and follow the lender's documentation requirements.
Do not create artificial bank deposits or false income records to make earnings appear higher.
11. Ignoring Work History
Some gig workers change platforms frequently or move between freelance clients. This does not automatically make them ineligible, but a lender may need evidence of a continuing income pattern.
How to avoid it:
-
Preserve old and current payout statements.
-
Keep invoices and client payment records.
-
Maintain a clear record of work activity.
-
Explain genuine gaps in earnings if asked.
12. Applying Through Unverified Loan Apps
An attractive advertisement or instant approval promise does not establish that a loan provider is legitimate.
Before sharing financial or identity information, check the actual lender and its relationship with any lending service provider.
The RBI's Digital Lending Directions, 2025 set requirements for regulated entities and their lending service provider arrangements, including borrower disclosures, creditworthiness assessment, data use and grievance redressal.
How to avoid it:
-
Identify the bank or NBFC that will provide the loan.
-
Check the lender's official website.
-
Read the privacy policy and loan terms.
-
Avoid apps demanding unnecessary access to contacts or personal data.
-
Never pay an unknown person a fee to guarantee approval.
13. Not Checking Interest Rates and Additional Charges
A low advertised interest rate may not represent the full cost of borrowing.
Look at the Annual Percentage Rate (APR), processing fees, applicable taxes on fees, late-payment terms and other disclosed charges.
How to avoid it: Read the Key Fact Statement (KFS) and compare the total repayment amount before accepting an offer.
14. Ignoring EMI Payment Dates
Gig workers may receive payouts on different dates. If the EMI date falls before the expected payout, the bank account may not have enough balance.
This can result in a missed payment and additional charges.
How to avoid it:
-
Choose a repayment date that suits your income cycle, where the lender allows it.
-
Keep an EMI reserve in your bank account.
-
Set reminders before the due date.
-
Maintain sufficient balance for automatic repayment.
15. Not Reading the Loan Agreement
Some borrowers accept a loan offer without checking the conditions.
This can lead to confusion about repayment schedules, fees, penalties, prepayment conditions and the lender's grievance process.
Before accepting a loan, read:
-
Key Fact Statement.
-
Loan agreement.
-
Repayment schedule.
-
Interest rate and APR.
-
Processing and other applicable charges.
-
Late-payment and penal-charge conditions.
-
Customer support and grievance details.
Summary Table: Common Mistakes and Better Practices
|
Common mistake |
Better practice |
|---|---|
|
Inflating monthly income |
Report realistic average earnings |
|
Missing bank statements |
Maintain regular banking records |
|
No payout proof |
Save platform and client records |
|
Ignoring credit history |
Review credit reports regularly |
|
Applying everywhere |
Compare before submitting applications |
|
Borrowing too much |
Choose an affordable loan amount |
|
Hiding existing debt |
Disclose current obligations |
|
Incorrect documents |
Verify details before uploading |
|
Unverified loan apps |
Check the actual regulated lender |
|
Ignoring loan costs |
Review APR and KFS |
Documents Gig Workers May Need for a Personal Loan in 2027
The exact document list varies by lender, applicant profile and loan product. The following are examples of records a gig worker may be asked to provide.
|
Document |
Why it may be required |
|---|---|
|
PAN card |
Identity and financial verification |
|
Aadhaar or other accepted ID |
Identity verification |
|
Address proof |
Address verification |
|
Bank statements |
Income and transaction review |
|
Platform payout statements |
Evidence of gig earnings |
|
Freelance invoices |
Evidence of client work |
|
Client payment records |
Supporting income evidence |
|
Existing loan details |
Assessment of repayment obligations |
|
Photograph or other forms |
As required by the lender |
How to organise income proof
For delivery partners and drivers:
-
Download payout statements from the work platform.
-
Maintain bank statements showing payments.
-
Keep records of work activity where available.
-
Record regular expenses such as fuel and vehicle maintenance.
For freelancers:
-
Keep invoices and payment receipts.
-
Maintain client agreements where available.
-
Track payments received through bank transfers.
-
Keep records of recurring projects and income gaps.
For workers using multiple platforms:
-
Maintain separate payout records for each platform.
-
Use bank statements to reconcile incoming payments.
-
Avoid counting the same transfer twice when calculating income.
How Lenders May Assess Gig Worker Loan Eligibility
There is no single eligibility formula used by every lender. However, a lender may examine the following areas before making a decision.
|
Eligibility factor |
What the lender may review |
|---|---|
|
Age |
Whether the applicant meets its age policy |
|
Occupation |
Whether gig or freelance work is accepted |
|
Income |
Amount and consistency of earnings |
|
Bank statements |
Credits, expenses and financial behaviour |
|
Credit history |
Past borrowing and repayment record |
|
Existing debt |
Current EMIs and outstanding balances |
|
Documents |
Accuracy and completeness of submitted records |
What matters most?
A gig worker with moderate but well-documented income may present a clearer application than someone reporting higher income without supporting records. This is a practical observation, not a guarantee of approval.
Lenders make decisions based on their own credit policies and risk assessments.
Comparison: Salaried Employees vs Gig Workers
|
Factor |
Salaried employee |
Gig worker |
|---|---|---|
|
Income pattern |
Often fixed monthly salary |
May vary by month |
|
Income proof |
Salary slips and Form 16 |
Payout records, invoices and bank statements |
|
Employment proof |
Employer letter or ID |
Platform or client work records |
|
Bank credits |
Often regular salary credits |
May be daily, weekly or irregular |
|
Eligibility assessment |
Based on lender's salary criteria |
Based on lender's accepted gig-income criteria |
|
Main challenge |
Existing debt or credit history |
Income verification and fluctuations |
Important: This comparison does not mean gig workers always have lower eligibility. Lenders differ in how they assess self-employed and platform-based applicants.
Pros and Cons of Applying for a Personal Loan as a Gig Worker
Pros
-
Flexible work can provide multiple income sources.
-
Digital payout histories may help demonstrate earnings.
-
Freelancers can document income through invoices and bank credits.
-
Some lenders offer products that consider non-salaried applicants.
-
A well-managed credit history can support future borrowing opportunities.
Cons
-
Monthly earnings may fluctuate.
-
Some lenders may not accept every type of gig occupation.
-
Traditional salary slips may not be available.
-
Income verification can take additional time.
-
A weak credit history or high existing debt can affect approval.
Step-by-Step Guide: How Gig Workers Can Improve Loan Eligibility in 2027
Step 1: Calculate Your Average Monthly Income
Review your recent earnings and calculate a realistic average. Do not use only your highest-earning month.
For example, if your earnings were ₹18,000, ₹21,000, ₹19,000 and ₹22,000 over four months:
This gives you a more useful starting point for planning.
Step 2: Maintain Consistent Financial Records
Keep your bank statements, platform payout summaries and invoices organised. Ensure that the records are genuine and can be verified.
Step 3: Review Your Credit Report
Check for missed payments, incorrect outstanding balances or accounts that have not been updated correctly. Resolve errors through the relevant lender or credit bureau.
Step 4: Reduce Existing Financial Obligations
Where possible, pay down expensive outstanding debt and avoid taking on unnecessary new credit. Do not use one high-cost loan simply to make another loan application look stronger.
Step 5: Choose an Affordable Loan Amount
Estimate how much you can repay even during a lower-income month.
For example, a worker earning ₹20,000 on average should not decide on an EMI based only on the average. They should also consider essential expenses, work-related costs and income variation.
Step 6: Compare Suitable Lenders
Check whether the bank or NBFC accepts gig-worker income. Compare interest rates, APR, processing fees, tenure and repayment terms.
Step 7: Submit Accurate Information
Provide genuine details about your occupation, earnings, bank account and existing loans. Upload clear and complete documents.
Step 8: Read the Offer Before Accepting
Review the KFS, loan agreement and repayment schedule. Make sure you understand the total cost and the date on which repayment will be collected.
Important RBI Digital Lending Rules Borrowers Should Know
Gig workers applying through digital platforms should understand basic borrower-protection requirements.
The Reserve Bank of India's Digital Lending Directions, 2025 cover regulated banks, NBFCs and other specified regulated entities involved in digital lending. They address matters such as creditworthiness assessment, disclosures, loan disbursal, repayment, data collection and grievance redressal.
Some important points for borrowers:
-
Know the actual lender: A lending app or service provider may connect you with a bank or NBFC. Identify the regulated entity providing the loan.
-
Read the KFS: Review the APR, repayment schedule and applicable charges before accepting the offer.
-
Understand data permissions: Check why the app requests access to your information and whether the request is necessary.
-
Check disbursal details: RBI directions generally require digital loan disbursal to go directly to the borrower's bank account, subject to specified exceptions.
-
Know the complaint process: Check the lender's grievance redressal contact details.
For more information, refer to the official RBI Digital Lending Directions, 2025.
Real-World Example: How a Small Mistake Can Affect a Loan Application
Consider Ravi, a delivery partner who earns different amounts every month.
|
Month |
Earnings |
|---|---|
|
January |
₹17,000 |
|
February |
₹20,000 |
|
March |
₹23,000 |
|
April |
₹18,000 |
|
Average |
₹19,500 |
Ravi applies for a personal loan and reports that he earns ₹25,000 every month. However, his payout records and bank statements show an average closer to ₹19,500.
The difference may lead the lender to ask for clarification or reassess his application.
What could Ravi do better?
-
Report his actual average income.
-
Submit the relevant bank statements.
-
Provide platform payout records.
-
Declare any existing EMIs.
-
Select a loan amount that fits his repayment capacity.
This example is illustrative. Actual approval depends on the lender's eligibility criteria and credit assessment.
Expert Commentary: What Should Gig Workers Focus on Before Applying?
A strong loan application is not simply about showing a high income. It is about demonstrating that the income is genuine, reasonably consistent and sufficient to manage repayments.
For gig workers, maintaining a clear record of earnings can be particularly useful. Bank statements, payout summaries and invoices help explain income patterns that may not appear in a traditional salary slip.
From a responsible borrowing perspective, applicants should also compare the full cost of a loan instead of choosing an offer based only on a low advertised EMI or quick-disbursal promise.
Practical recommendation: Prepare your income records first, check your existing financial commitments and then apply only to a lender whose eligibility requirements match your circumstances.
How to Identify a Safe Digital Loan Offer
Before proceeding with any digital loan application, use this checklist:
How Vizzve Financial Can Help
Understanding loan eligibility can be confusing when you work independently or earn through multiple platforms. Reviewing your income records, comparing loan terms and understanding the application process can help you make a more informed borrowing decision.
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Before applying, review the available lender's eligibility conditions, interest rate, fees and repayment terms. Loan approval is subject to the relevant lender's assessment and applicable requirements.
Key Takeaways
-
Gig workers can apply for personal loans if they meet the lender's eligibility requirements.
-
Irregular income does not automatically mean loan rejection.
-
Accurate income reporting is essential.
-
Bank statements and platform payout records may help verify earnings.
-
Check your credit history before submitting an application.
-
Avoid making several formal loan applications in a short period.
-
Declare existing loans and credit card dues honestly.
-
Borrow only an amount you can repay comfortably.
-
Compare APR, processing fees and repayment terms.
-
Apply through a verified lender and read the KFS before accepting a loan.
Frequently Asked Questions (FAQs)
1. Can gig workers get a personal loan in 2027?
Yes. Gig workers may qualify for personal loans if they meet the lender's income, credit history, documentation and repayment-capacity requirements. Approval depends on the lender's policy.
2. Can delivery partners apply for personal loans?
Yes. Delivery partners may apply if the lender accepts platform-based income and the applicant meets its eligibility conditions.
3. Can I get a loan without a salary slip?
Some lenders accept alternative income evidence, such as bank statements, platform payout records, freelance invoices and client payment records.
4. What is the minimum income required for a gig worker loan?
There is no universal minimum income requirement. Each bank or NBFC sets its own income criteria based on its loan product and risk assessment.
5. Does a gig worker need a credit score to get a loan?
Lenders may review credit history and credit scores when assessing an application. Their requirements differ, and some may consider additional financial information.
6. What documents are required for a gig worker personal loan?
Commonly requested documents may include PAN, accepted identity and address proof, bank statements and platform payout records. The exact requirements depend on the lender.
7. Can a freelancer apply for a personal loan?
Yes. Freelancers may apply through lenders that accept freelance income. Invoices, client payment records and bank statements can help demonstrate earnings.
8. Why do personal loans get rejected for gig workers?
Possible reasons include insufficient verified income, incomplete documents, poor repayment history, high existing debt or not meeting the lender's occupation criteria.
9. Does irregular income affect loan eligibility?
It can. A lender may review income consistency and repayment capacity. Maintaining organised records can help explain fluctuations in earnings.
10. Can gig workers apply for loans using bank statements?
Some lenders accept bank statements as part of income verification. They may also request additional documents, such as platform payout summaries or invoices.
11. Does applying to multiple loan apps affect my credit score?
Multiple formal credit applications can result in several credit enquiries, which may influence how lenders assess your credit profile. Compare offers before submitting applications.
12. How can gig workers improve their loan approval chances?
Maintain accurate income records, pay existing EMIs on time, review your credit report, reduce unnecessary debt and apply for an affordable loan amount.
13. Can I get a loan if I work on two delivery platforms?
Possibly. Some lenders may consider income from multiple platforms if they accept the applicant's occupation and the earnings can be verified. Their documentation rules may differ.
14. Is e-Shram registration enough to get a personal loan?
No. Registration alone does not guarantee loan eligibility or approval. Lenders may still assess income, credit history, repayment capacity and other documents.
15. What should I check before accepting a digital loan?
Check the regulated lender's identity, APR, KFS, processing charges, repayment schedule, privacy policy and grievance redressal details before accepting the loan.
Conclusion
Loan eligibility for gig workers in 2027 depends on more than the amount earned in a month. Income consistency, genuine financial records, credit history, existing obligations and repayment capacity can all influence a lender's decision.
Avoiding common mistakes can make the application process clearer and help you borrow responsibly. Keep your documents organised, report your income accurately, compare loan costs and never accept a loan without understanding its terms.
Planning to apply for a personal loan? Visit Vizzve Financial to explore available loan support options and understand the application process. Always check the relevant lender's eligibility conditions before applying.
Published on : 6th November
Published by : Reddy kumar
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed