

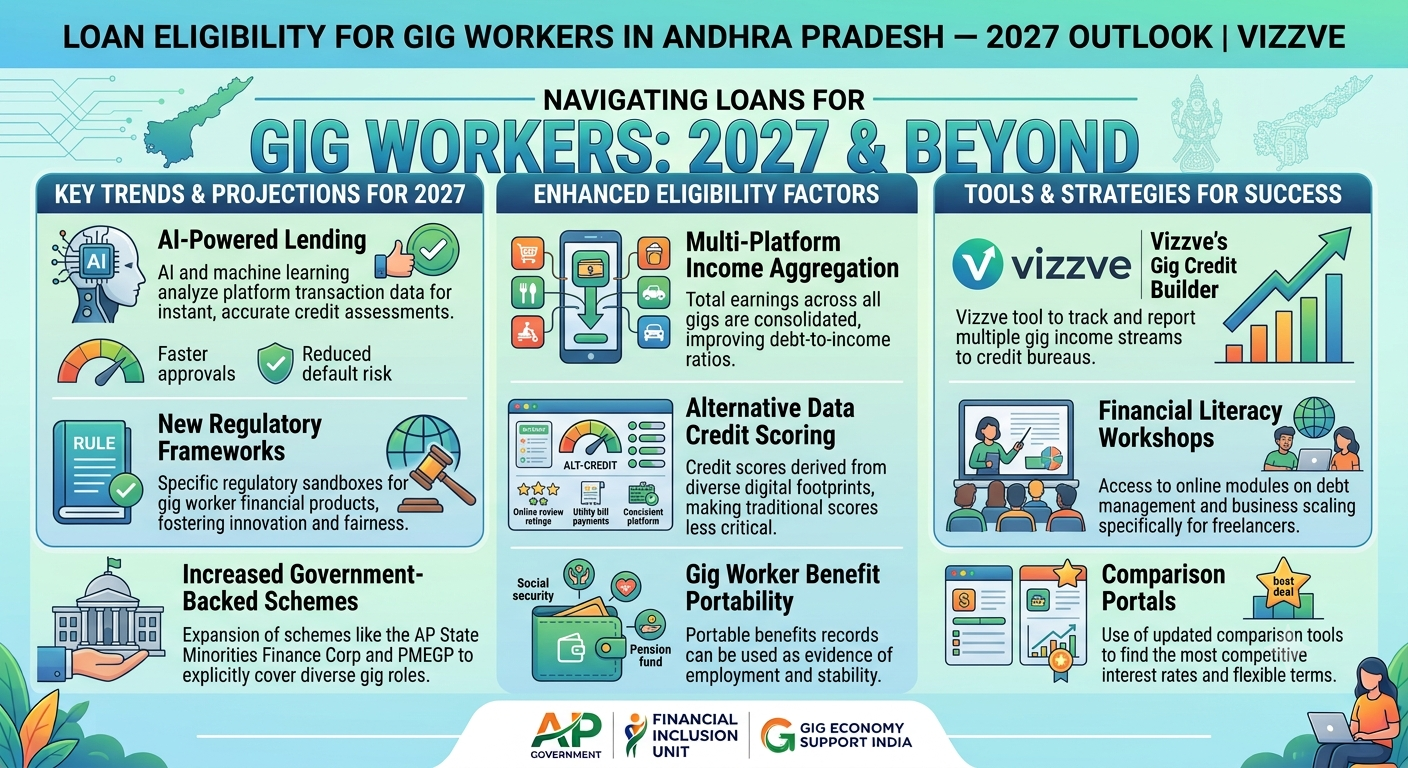
Gig work has become an important source of income for delivery partners, app-based drivers, freelancers, and independent service providers. For these workers, accessing formal credit can be challenging when earnings vary each month or traditional salary documents are unavailable.
Looking ahead to 2027, one area worth watching is the use of digital financial records to assess borrowers whose income comes from platform work. The Reserve Bank Innovation Hub has reported pilot work exploring consent-based use of gig-platform work history, earnings, and performance data for credit assessment. This points to a possible direction for lending, but it does not guarantee wider loan access or approval for every gig worker.

For gig workers in Andhra Pradesh, the practical priority remains the same: keep income records organised, understand lender requirements, compare total loan costs, and borrow only what can be repaid comfortably.
4. AI Answer Box: What Is the 2027 Outlook for Gig Worker Loans?
The 2027 outlook for gig worker loans in Andhra Pradesh may be shaped by digital lending, alternative income verification, and efforts to improve access to formal credit. Bank statements, platform earnings records, and other permitted financial information may help some lenders assess applicants who do not have regular salary slips.
However, eligibility rules, interest rates, documentation requirements, and loan availability will depend on the lender and the product. Gig workers should not assume that digital records guarantee approval. They should verify the lender, review the APR and Key Fact Statement, and choose an EMI that remains affordable when earnings fluctuate.

5. Key Trends to Watch in 2027

1. Greater attention to income patterns
Lenders may continue exploring ways to understand irregular earnings. Consistent bank credits and genuine platform payment records could be useful where a lender accepts them.

2. Digital financial information
Consent-based sharing of financial data may help eligible applicants demonstrate their financial activity. Borrowers should understand what information is being shared and why.

3. More focus on transparent loan costs
RBI's Digital Lending Directions, 2025 set out requirements for regulated entities engaged in digital lending. Borrowers should continue checking disclosures, fees, APR, and repayment terms before accepting an offer.

4. Greater importance of financial preparedness
Clear income records, manageable existing debt, and a realistic repayment budget can help applicants prepare for lender assessments, regardless of how lending products develop.
These are trends to monitor, not promises that every lender will introduce new products or relax eligibility criteria during 2027.
6. How Loan Eligibility May Be Assessed in 2027
The following factors are likely to remain relevant to loan applications, although each lender may use different criteria.
|
Eligibility factor |
What gig workers can prepare |
|---|---|
|
Income consistency |
Keep bank statements and genuine earnings records. |
|
Platform work history |
Save available work and payment summaries. |
|
Credit history |
Pay existing EMIs on time and review credit records. |
|
Existing debt |
Calculate total monthly repayments before applying. |
|
Identity and address |
Keep required documents current. |
|
Repayment capacity |
Budget for low-earning weeks and unexpected expenses. |
|
Loan purpose |
Choose a loan suited to the intended expense. |
There is no universal income requirement or credit score that guarantees loan approval for gig workers in Andhra Pradesh.
7. Will Salary Slips Still Be Necessary?
Not necessarily for every product. Some lenders may consider alternative evidence of income, depending on their policies and the applicant's circumstances.
Potential supporting records include:
-
Bank statements showing income deposits
-
Delivery-platform or driver earnings reports
-
Freelance invoices and payment receipts
-
Records of work activity, where accepted
-
Existing loan repayment history
Alternative documentation does not automatically replace every lender's requirements. Ask the lender which documents it accepts before submitting an application.
8. Loan Options Gig Workers Can Explore
|
Loan category |
Potential purpose |
Important consideration |
|---|---|---|
|
Personal loan |
Eligible personal expenses |
Compare APR, fees, and repayment terms. |
|
Small-ticket credit |
Smaller financial needs |
Check the total cost relative to the amount borrowed. |
|
Vehicle loan |
Buying an eligible vehicle |
Review the down payment and security conditions. |
|
Business loan |
Eligible work-related expenses |
Check business eligibility and permitted use. |
Availability and approval depend on the lender, the product, and the applicant's circumstances. A larger loan limit is not necessarily a better financial choice.
9. How Gig Workers in Andhra Pradesh Can Prepare
-
Maintain income records. Keep bank statements, platform payment summaries, and invoices organised.
-
Build healthy repayment habits. Pay existing credit obligations on time where possible and contact lenders early if repayment difficulties arise.
-
Estimate affordable EMIs. Calculate income after household costs, fuel, maintenance, and other work-related expenses.
-
Compare loan offers. Review APR, processing fees, total repayment, late charges, and prepayment terms.
-
Verify the lender. Use official channels to confirm which regulated entity provides the loan.
-
Share financial data carefully. Understand the purpose of consent requests before authorising access to your information.
10. Digital Lending Safety in 2027
Digital applications may make loan processes more convenient, but borrowers still need to protect themselves from misleading offers and fraudulent apps.
The Indian government has highlighted the RBI's Digital Lending App directory, operational since July 2025, as a resource for checking claims that an app is associated with a regulated entity. Verify the app and the actual lender through official sources before applying.
Use this checklist before accepting an offer:
-
Read the Key Fact Statement and loan agreement.
-
Compare the APR and total repayment amount.
-
Check the lender's identity and complaint channels.
-
Avoid agents promising guaranteed approval.
-
Never share OTPs, PINs, or banking passwords.
-
Save copies of loan documents and receipts.
11. Potential Benefits and Challenges
Potential benefits
-
Digital records may help some workers demonstrate income.
-
Online applications may simplify document submission.
-
Alternative assessment methods may offer another way to evaluate applicants without conventional salary slips.
-
Better financial recordkeeping can support loan preparation.
Potential challenges
-
Irregular income can make fixed EMIs difficult to manage.
-
Not every lender accepts platform earnings as income proof.
-
Data sharing raises privacy and consent considerations.
-
Loan costs and eligibility requirements vary.
-
Wider use of digital lending does not guarantee more affordable credit for every borrower.
12. Real-World Example
Imagine a delivery partner in Visakhapatnam who earns different amounts each month and wants to borrow money for a vehicle repair.
The worker collects several months of bank statements and platform earnings records, calculates essential monthly expenses, and compares two loan offers. Before applying, the worker checks the APR, total repayment, fees, and whether the EMI remains affordable in a slow month.
This example illustrates a practical approach, not a prediction about how a lender will approve a future application. The safest decision depends on the actual offer and the borrower's financial circumstances.
13. Vizzve Financial
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
For any loan application, check the current eligibility conditions, applicable fees, repayment terms, and the identity of the lender providing the loan. Approval is subject to the relevant lender's assessment.
14. Frequently Asked Questions
1. What is the outlook for gig worker loans in Andhra Pradesh in 2027?
Digital income records and alternative credit assessment are areas to watch, but future loan availability and eligibility rules will depend on lenders and applicable regulations.
2. Will gig workers get easier loan approval in 2027?
That cannot be guaranteed. Eligibility will depend on the lender, income evidence, credit history, existing debt, and repayment capacity.
3. Can delivery partners apply for personal loans?
Yes, delivery partners may apply if they meet the lender's eligibility criteria and provide acceptable documentation.
4. Will salary slips be compulsory in 2027?
Requirements will vary. Some lenders may accept bank statements or platform earnings records, while others may request different documents.
5. Can platform earnings help demonstrate loan eligibility?
They may help when a lender accepts those records as part of its income assessment.
6. Will digital lending apps offer loans to all gig workers?
No. Digital access does not guarantee eligibility, approval, or disbursal.
7. Does credit score affect loan approval?
Credit history can influence a lender's decision, but lenders may also assess income, existing obligations, and other factors.
8. What documents should gig workers keep ready?
Common documents include identity and address proof, bank statements, income records, and details of existing debts. Requirements differ by lender.
9. Are loans for gig workers available in Vijayawada and Visakhapatnam?
Applicants in these cities may explore lenders operating in their area. Product availability and eligibility should be confirmed directly with the lender.
10. How can gig workers compare loan costs?
Compare APR, processing fees, the net amount received, total repayment, EMI schedule, and applicable charges.
11. What is alternative credit assessment?
It refers to assessing creditworthiness using additional permitted information, potentially including cash-flow records or platform earnings data, rather than relying only on conventional documents.
12. Is it safe to share platform earnings data?
Only share data through verified channels after understanding the purpose, scope, and consent terms. Avoid providing information to unverified agents or apps.
13. Can a gig worker with irregular income repay a personal loan safely?
It depends on the amount borrowed, essential expenses, income variability, and EMI. Build a budget that allows for lower-earning periods.
14. How can gig workers avoid loan app scams?
Verify the actual lender through official sources, read the loan disclosures, avoid guaranteed-approval promises, and never share banking credentials.
15. Should gig workers wait until 2027 to apply for a loan?
Not solely because of a future outlook. Compare the options currently available, assess affordability, and apply only when the loan is necessary and manageable.
15. Key Takeaways
-
The 2027 outlook is uncertain; do not assume loan rules or approval rates will change.
-
Digital income records may help some gig workers demonstrate earnings.
-
Eligibility depends on lender requirements and individual repayment capacity.
-
Compare APR, fees, and total repayment—not just the EMI.
-
Verify digital lenders and protect financial information.
-
Maintain income records and borrow only what you can afford.
16. Conclusion
The 2027 outlook for gig worker loans in Andhra Pradesh will depend on developments in digital lending, income verification, and access to formal credit. New assessment methods may create opportunities for some borrowers, but they will not guarantee approval or remove the need for careful financial planning.
For delivery partners, app-based drivers, and freelancers, the most useful steps are to maintain reliable income records, manage existing debt, compare transparent loan offers, and protect personal data. A responsible borrowing decision should always be based on actual lender terms—not future predictions.
Published on : 17th October
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed