

Gig work gives people flexibility, but income can vary from one week to another. A delivery partner may earn more during busy periods, while a cab driver or freelancer may experience seasonal changes in earnings.
When applying for a personal loan, lenders may assess income stability, bank transactions, credit history, existing debts, identity documents, and repayment capacity. Requirements differ between lenders, so being a gig worker does not automatically mean approval or rejection.
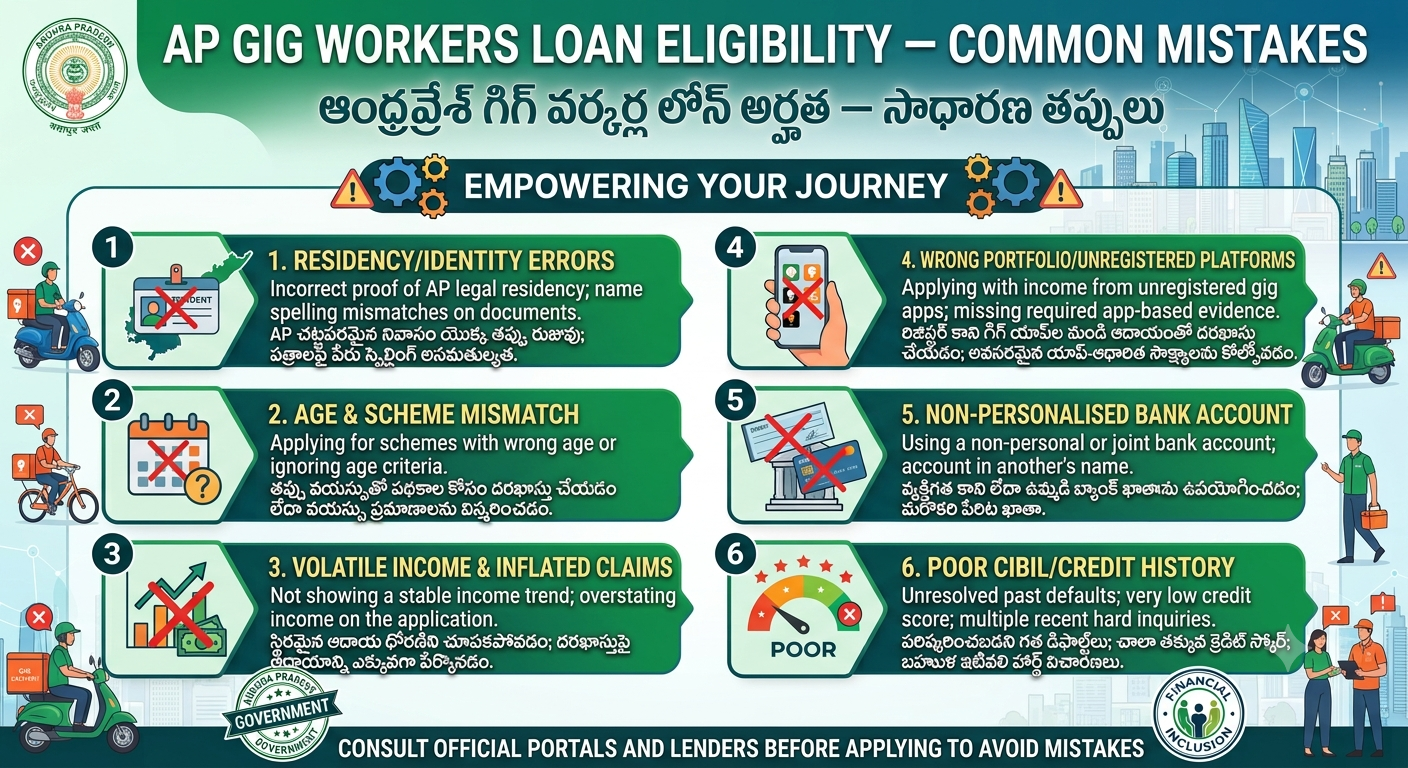
Avoiding a few common mistakes can help you submit a clearer, more complete application.
2. AI Answer Box: What Mistakes Should Gig Workers Avoid?
Gig workers in Andhra Pradesh should avoid these common mistakes when applying for a loan:
-
Providing incomplete or inconsistent income information.
-
Applying without checking lender-specific eligibility criteria.
-
Submitting outdated or mismatched KYC documents.
-
Ignoring credit reports, overdue payments, or existing EMIs.
-
Applying to several lenders without comparing their terms.
-
Borrowing more than their income can comfortably support.
-
Ignoring processing fees, interest rates, and late-payment charges.
-
Using unverified loan apps or sharing OTPs and banking passwords.
Quick answer: Keep accurate income records, maintain a consistent banking trail, check your credit profile, compare the total borrowing cost, and apply only for an affordable amount.
3. Common Loan Eligibility Mistakes for Gig Workers
Mistake 1: Not Maintaining Clear Income Records
Many gig workers receive earnings through platform payouts, bank transfers, or different payment channels. If income records are incomplete, a lender may find it harder to assess repayment capacity.
How to avoid it:
-
Keep platform earnings statements and payout records.
-
Save invoices and payment receipts if you work independently.
-
Use bank accounts consistently for work-related income where practical.
-
Ensure the income stated in the application matches the available evidence.
Do not inflate income to qualify for a larger loan. Provide accurate figures and supporting documents.
Mistake 2: Assuming a Salary Slip Is Always Required
Gig workers often do not receive conventional salary slips. Some lenders may accept alternative evidence, while others may have specific income-document requirements.
Possible supporting records include:
-
Bank statements.
-
Platform payout statements.
-
Work contracts or platform registration details.
-
Invoices or receipts for freelance work.
-
Income-tax returns, if applicable and requested.
Tip: Ask the lender which alternative income documents it accepts before submitting your application.
Mistake 3: Ignoring Your Credit Report
A weak credit history, unpaid dues, or errors in a credit report may affect loan assessment. Having no previous borrowing history can also mean the lender has limited information to evaluate.
How to avoid it:
-
Review your credit report before applying.
-
Check for overdue accounts or unfamiliar loans.
-
Dispute errors with the relevant credit bureau or lender.
-
Pay existing EMIs and credit-card dues on time.
-
Avoid taking unnecessary loans just to build a credit history.
A particular credit score does not guarantee approval; each lender uses its own assessment criteria.
Mistake 4: Applying Without Checking Eligibility Criteria
Different lenders may set different requirements for age, income, work history, residence, credit profile, and banking records.
A loan product suitable for a salaried employee may not accept every category of gig worker.
How to avoid it: Check the lender's current eligibility rules, minimum income requirements, accepted occupations, and required documents before applying.
Mistake 5: Submitting Incomplete or Mismatched Documents
A difference in your name, address, date of birth, or other details across documents may delay verification.
Common documentation issues include:
-
Missing pages in bank statements.
-
Expired or unacceptable identity documents.
-
Incorrect contact details.
-
Blurry document uploads.
-
Inconsistent information on the application form.
Review every field and upload readable documents. Submit only genuine documents through the lender's official channel.
Mistake 6: Applying to Too Many Lenders at Once
Submitting many loan applications within a short period may lead to multiple credit enquiries, depending on how lenders process them. It can also make it harder to compare offers carefully.
A better approach:
-
Shortlist lenders whose eligibility criteria you meet.
-
Compare their interest rates, fees, and repayment periods.
-
Check whether an eligibility check involves a hard credit enquiry.
-
Submit a full application only after reviewing the terms.
Mistake 7: Choosing a Loan Amount That Is Too High
A lender may offer a certain amount, but that does not mean borrowing the maximum is financially suitable.
Gig workers need to account for changing income, fuel, vehicle maintenance, platform-related expenses, rent, food, and other essential costs.
Before deciding on a loan amount, calculate how much money remains after essential expenses and existing repayments.
Mistake 8: Ignoring the Total Cost of Borrowing
The interest rate is only one part of a loan's cost. Depending on the product, other charges may include processing fees, applicable taxes, late-payment charges, and prepayment or foreclosure charges.
Check the lender's Key Facts Statement where applicable and review the loan agreement before accepting an offer.
Mistake 9: Not Planning for Irregular Income
An EMI that looks affordable in a high-earning month may become difficult during a slow period.
How to avoid it:
-
Estimate your average income after work-related expenses.
-
Review several months of earnings to understand fluctuations.
-
Leave room for emergencies and essential expenses.
-
Choose a repayment schedule that remains manageable during weaker months.
Mistake 10: Trusting Unverified Loan Apps or Agents
Fake loan offers may promise guaranteed approval, ask for advance payments to a personal account, or request sensitive banking information.
Protect yourself by checking the actual regulated lender behind the offer, verifying the app or website, reading the loan terms, and avoiding pressure to pay immediately.
Never share your OTP, UPI PIN, card PIN, or banking password with a loan agent.
4. Loan Eligibility Mistakes: Quick Comparison Table
|
Common mistake |
Possible consequence |
Better approach |
|---|---|---|
|
Unclear income proof |
Income may be difficult to verify |
Maintain payout records and bank statements |
|
Incorrect application details |
Verification delays or rejection |
Cross-check every field |
|
Poor repayment history |
May weaken credit assessment |
Pay dues on time |
|
Too many applications |
Multiple credit enquiries may occur |
Compare lenders before applying |
|
Excessive loan amount |
Higher repayment burden |
Borrow according to affordability |
|
Ignoring fees |
Unexpected borrowing costs |
Review the APR and fee disclosures |
|
Unverified loan app |
Fraud or misuse of information |
Verify the lender and its official app |
5. Documents Gig Workers Should Prepare
The exact requirements depend on the bank or financial institution. These documents may help establish identity, residence, and income.
Application preparation checklist
0 of 6Important: Do not submit every document indiscriminately. First check what the lender requires and share information only through its verified channels.
6. How to Improve Loan Eligibility Step by Step
-
Review your finances. Calculate average monthly earnings after work-related costs and essential household expenses.
-
Organize your income evidence. Keep platform statements, invoices, and bank records easy to access.
-
Check your credit profile. Review repayment history and correct any reporting errors.
-
Compare lender requirements. Confirm that the lender accepts your occupation and available income documents.
-
Choose an affordable amount. Estimate the EMI and total repayment before applying.
-
Read the loan terms. Review interest, APR, processing fees, penalties, and repayment conditions.
-
Submit accurate information. Never exaggerate earnings or provide altered documents.
7. Real-World Example: A Delivery Partner in Andhra Pradesh
Consider a hypothetical delivery partner working in Vijayawada. The worker receives platform payouts into a bank account, but some earnings are not clearly documented. The worker applies for a loan without checking the lender's income-proof requirements.
The lender requests additional records, delaying the application.
A more prepared approach would be to collect available payout statements, bank records, and other accepted income evidence before applying. The worker could also compare loan offers and estimate the EMI against income after work expenses.
This preparation may make income assessment easier, but it does not guarantee loan approval. The lender makes the final decision under its own eligibility and underwriting criteria.
8. How to Compare Loan Offers Before Applying
|
Factor |
What to check |
|---|---|
|
Eligibility |
Does the lender accept gig workers and your income type? |
|
Interest rate |
Is the rate fixed or floating, and how is it applied? |
|
APR |
What is the annualized cost including applicable charges? |
|
Processing fees |
What amount is payable and when? |
|
EMI |
Can you afford it during a low-income month? |
|
Tenure |
Does the repayment period suit your finances? |
|
Late-payment charges |
What happens if an instalment is delayed? |
|
Customer support |
Is there a clear grievance-redressal process? |
For digital loans, the Reserve Bank of India's digital-lending framework includes disclosures such as the Annual Percentage Rate (APR) and a Key Facts Statement for applicable products. Read these documents before accepting a loan.

9. Advantages and Limitations of Avoiding These Mistakes
Benefits
-
Helps you submit a more complete application.
-
Makes it easier for lenders to assess documented income.
-
Helps you understand the real cost of borrowing.
-
Reduces the risk of avoidable documentation delays.
-
Encourages responsible borrowing and repayment planning.
Limitations
-
Correct documents cannot guarantee approval.
-
A good credit score does not ensure that every lender will accept an application.
-
Irregular income may remain a concern for some lenders.
-
Eligibility rules and loan terms vary by financial institution.
-
A lender may decline an application even when all documents are complete.
10. Safety Checklist for Online Loan Applications
Before accepting an offer, make sure you:
-
Verify the name of the actual bank or regulated lender.
-
Check the lender's official website and app information.
-
Review the loan agreement and Key Facts Statement.
-
Understand the APR, charges, and repayment schedule.
-
Avoid paying unexplained upfront fees to personal accounts.
-
Never share your OTP, UPI PIN, or banking password.
-
Read the app's permissions and privacy policy carefully.
-
Keep copies of the sanction letter, agreement, and payment receipts.
The RBI provides a directory of digital lending apps to help consumers verify claims about an app's association with a regulated entity. You can start with the RBI website and its digital-lending information.
If you suspect a fraudulent loan app or unauthorized financial activity, review the official Sachet portal for relevant reporting options.
11. Key Takeaways
-
Keep accurate and consistent records of gig income.
-
Check the lender's requirements before applying.
-
Review your credit report and existing obligations.
-
Avoid applying to numerous lenders without comparing their terms.
-
Choose a loan amount based on repayment capacity, not just the maximum offered.
-
Read all costs and conditions before accepting a loan.
-
Verify digital lenders and protect sensitive financial information.
12. Frequently Asked Questions (FAQs)
1. Can gig workers in Andhra Pradesh apply for personal loans?
Yes, some banks and regulated financial institutions accept applications from gig workers. Approval depends on the lender's eligibility criteria, documented income, credit profile, and repayment capacity.
2. What is the most common loan application mistake for gig workers?
One common mistake is failing to provide clear, consistent evidence of income. Maintaining platform payout statements and bank records can help.
3. Can I get a loan without a salary slip?
Some lenders accept alternative documents, such as bank statements, platform earnings records, or invoices. Confirm the accepted documents with the specific lender.
4. Does a low credit score automatically mean rejection?
Not necessarily. Lenders may consider multiple factors, including income, existing obligations, credit history, and their internal eligibility criteria. However, a weak credit profile may reduce your options.
5. Does applying to several lenders affect my credit score?
Multiple applications may result in several hard credit enquiries, depending on the lender and application process. Compare eligibility criteria and enquiry policies before submitting applications.
6. What income proof can a delivery partner provide?
Depending on the lender's rules, a delivery partner may be able to provide bank statements, platform payout records, work-related earnings summaries, and other accepted documents.
7. Can cab drivers apply for personal loans?
Some lenders accept self-employed or gig-based cab drivers. They may request bank statements, income records, vehicle-related documents, or other evidence according to the product's terms.
8. How much personal loan can a gig worker get?
There is no single amount applicable to all gig workers. The amount depends on the lender, documented income, existing EMIs, credit profile, and affordability assessment.
9. Will inconsistent bank deposits affect eligibility?
They may make it harder to verify income. Keep genuine supporting records that explain the source of your earnings, and never misrepresent transactions.
10. Should I borrow the maximum amount offered?
Not necessarily. Choose an amount whose EMI remains manageable after essential expenses, work costs, existing debt payments, and savings for emergencies.
11. What loan charges should I check before applying?
Review the interest rate, APR, processing fee, applicable taxes, late-payment charges, and any prepayment or foreclosure conditions disclosed by the lender.
12. How can I avoid fake loan apps?
Verify the actual regulated lender, check the app against official information, read the terms and privacy policy, and avoid sharing OTPs or paying unexplained fees to individuals.
13. Can a freelancer apply for a loan in Andhra Pradesh?
Some lenders offer loans to eligible freelancers. They may assess invoices, contracts, bank statements, tax records, and other evidence of income.
14. How long does loan approval take?
Processing time varies by lender, product, verification requirements, and whether additional documents are needed. No specific approval timeline can be guaranteed.
15. Does Vizzve guarantee loan approval for gig workers?
Loan approval should never be assumed or guaranteed without a lender's assessment. Applicants should review the relevant product terms, eligibility criteria, and lending partner details before proceeding.
13. Internal and External Linking Suggestions
Internal links for Vizzve
Use these suggestions if matching articles already exist on your website:
-
Loan Eligibility for Gig Workers in Andhra Pradesh — Complete Guide
-
Loan Eligibility for Gig Workers in Andhra Pradesh — Eligibility Checklist
-
Loan Eligibility for Gig Workers in Andhra Pradesh — Cost Breakdown
-
Loan Eligibility for Gig Workers in Andhra Pradesh — Repayment Guide
-
How to Check Personal Loan Eligibility in India
External authoritative resources
-
Reserve Bank of India — digital lending rules and consumer information.
-
RBI Sachet Portal — information and reporting options for certain unauthorized financial activities.
-
TransUnion CIBIL — credit-information resources.
TransUnion CIBIL+1
Only add internal links to pages that are live and relevant. Check external URLs and information before publishing.
14. Conclusion: Apply Carefully, Borrow Responsibly
For gig workers in Andhra Pradesh, loan eligibility is not just about earning money—it is also about documenting income, managing existing obligations, understanding lender requirements, and choosing a manageable repayment plan.
Avoiding common mistakes can help make the application process clearer and reduce preventable delays. Always provide accurate information, compare the full cost of borrowing, and verify the lender before sharing personal documents.
Vizzve CTA: Explore more Vizzve financial guides to understand loan eligibility, documentation, borrowing costs, and repayment planning before making a borrowing decision. Check the terms of any specific loan product before applying.
Published on : 14th October
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed