

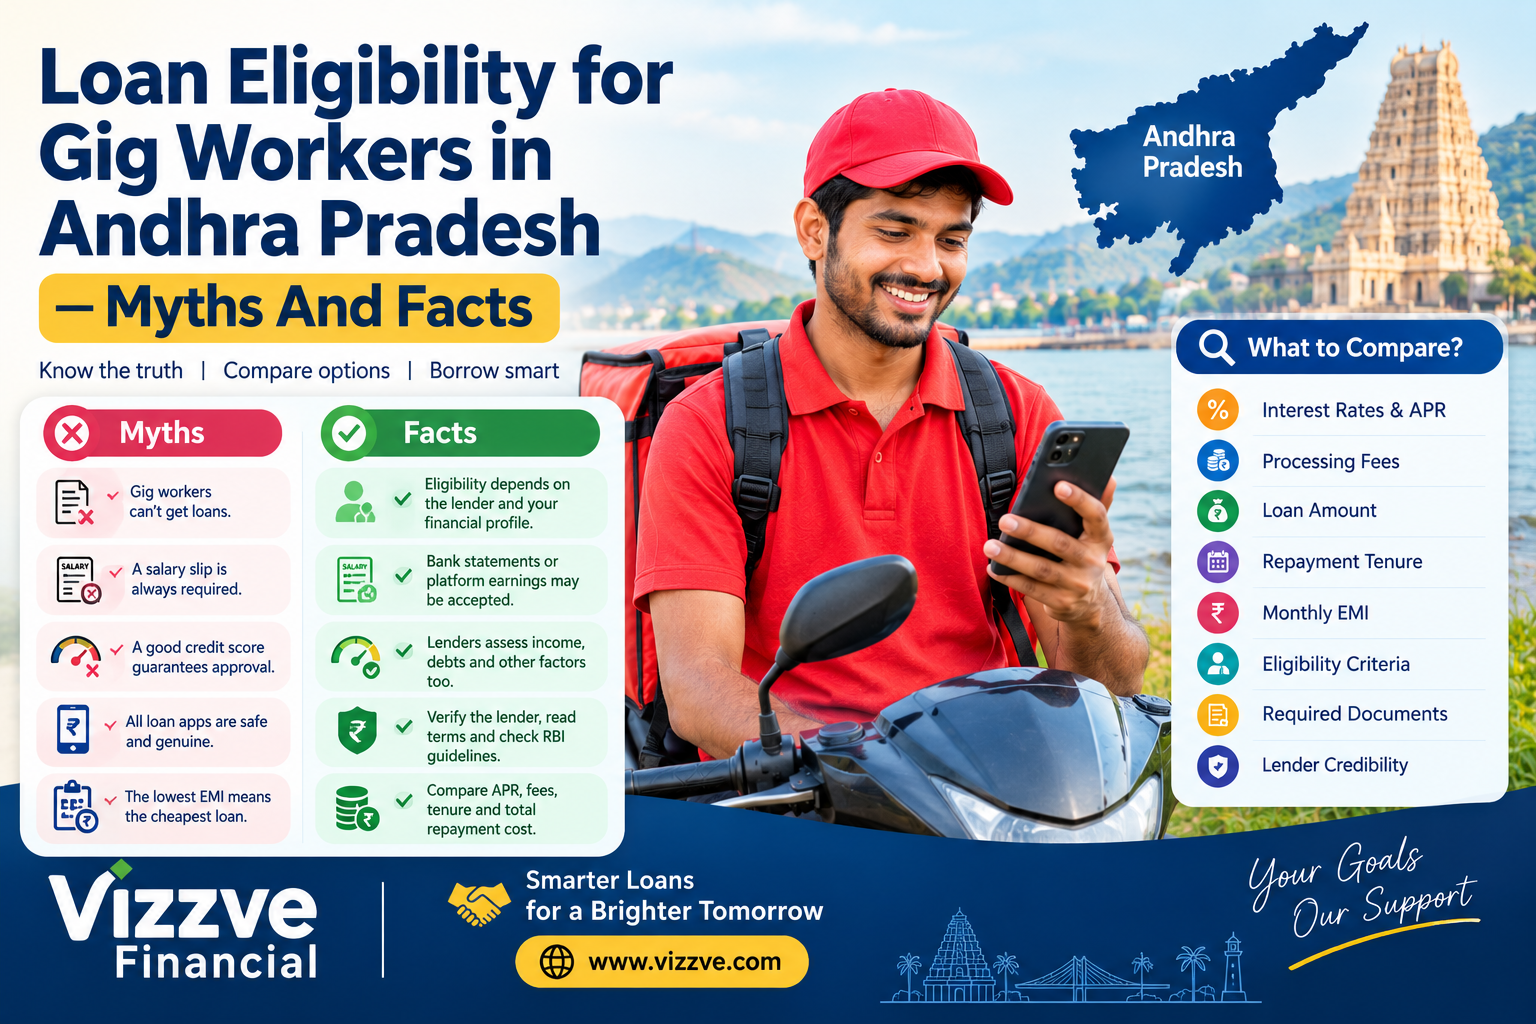
Gig work gives people the flexibility to earn through delivery services, ride-hailing platforms, freelancing, courier services, and independent work. However, gig workers may face questions when they need a personal loan.
Some borrowers believe that a loan is impossible without a salary slip. Others assume that a good credit score guarantees approval or that every digital loan app is safe.
These assumptions can lead to missed opportunities or risky borrowing decisions.
The fact is that gig workers may qualify for loans if they meet a lender's eligibility criteria and demonstrate their ability to repay. Requirements differ between banks, non-banking financial companies (NBFCs), and loan products.
This guide from Vizzve Financial explains the most common myths and facts about loan eligibility for gig workers in Andhra Pradesh.
3. AI Answer Box: Can Gig Workers Get Loans in Andhra Pradesh?
Yes, gig workers in Andhra Pradesh may qualify for personal loans or other suitable credit products, depending on the lender's requirements. Lenders may evaluate income, bank statements, work history, credit history, existing debts, age, and identity documents.
A traditional salary slip is not the only possible evidence of income. Some lenders may accept platform payout records or bank statements. However, approval, interest rates, and loan amounts are never guaranteed solely because an applicant works as a gig worker.
Before accepting an offer, review the interest rate, annual percentage rate (APR), fees, repayment schedule, and Key Facts Statement (KFS).
4. Common Myths and Facts About Gig Worker Loans

Myth 1: Gig workers cannot get personal loans
Gig workers may qualify for eligible loan products. Lenders assess each application according to their policies, including income, repayment capacity, credit history, and documentation.

Myth 2: A salary slip is always compulsory
Some lenders may accept bank statements, platform payout records, or other income evidence. The accepted documents depend on the specific lender and loan product.

Myth 3: A good credit score guarantees approval
A good credit history may help, but lenders also assess income, existing EMIs, affordability, and other eligibility conditions. No credit score guarantees approval.

Myth 4: Every instant loan app is safe
Not every app or lending offer is trustworthy. Verify the actual lender, review the loan agreement, and check the RBI's resources for verifying digital lending apps and regulated entities.

Myth 5: The lowest EMI means the cheapest loan
A low EMI can result from a longer tenure, which may increase total interest. Compare APR, fees, tenure, and total repayment—not just the monthly instalment.
5. Myth vs Fact: Quick Comparison Table
|
Common myth |
The fact |
|---|---|
|
Gig workers are automatically rejected |
Eligibility depends on the lender and the applicant's financial profile |
|
Salary slips are always required |
Alternative income evidence may be accepted |
|
A high credit score guarantees approval |
Lenders assess multiple factors |
|
Every digital loan app is legitimate |
The actual lender and app relationship must be verified |
|
All lenders charge the same interest rate |
Rates and charges vary by product and borrower |
|
A larger loan is always better |
Borrow only what you need and can repay |
|
Applying to many lenders guarantees approval |
Multiple applications do not guarantee approval and may create additional credit enquiries |
|
Missing one EMI has no consequences |
Late payment may result in charges and affect credit history |
|
Loan approval is guaranteed if a fee is paid |
Upfront payment demands and guaranteed-approval claims should be treated cautiously |
6. Myth: Gig Workers Need a Fixed Monthly Salary
Fact: Gig workers may have daily, weekly, or fluctuating income. Some lenders can consider alternative income records, although others may require specific documentation.
For example, a delivery partner working in Visakhapatnam might receive earnings through platform payouts several times a week. Bank statements and platform earnings summaries could help document that income if the lender accepts them.
Useful records may include:
-
Recent bank statements
-
Platform payout summaries
-
Earnings statements from delivery or ride-hailing apps
-
Income-tax returns, where applicable
-
Records of work history
-
Details of existing loan repayments
Keep the information accurate and consistent. Never edit financial records to make earnings appear higher.
7. Myth: Every Gig Worker Has the Same Loan Eligibility
Fact: Two people doing the same job may receive different decisions.
A lender may consider:
-
Average monthly income
-
Consistency of earnings
-
Existing loans and EMIs
-
Credit history
-
Age and identity verification
-
Employment or platform records
-
The requested loan amount and tenure
A delivery partner earning ₹25,000 per month with low existing debt may have a different financial profile from someone earning the same amount but already paying several EMIs. These figures are illustrative, not an eligibility threshold.
8. Myth: A Loan Application Requires No Documents
Fact: Most formal loan applications require identity verification and an assessment of repayment capacity.
|
Possible document |
Why it may be needed |
|---|---|
|
PAN card |
Tax and financial identification |
|
Accepted identity proof |
Identity verification |
|
Address proof |
Address verification |
|
Bank statements |
Review of transactions and income |
|
Platform earnings records |
Evidence of gig-work income |
|
Existing loan information |
Assessment of financial commitments |
The precise requirements depend on the lender. Check its official document list before applying.
9. Myth: All Loan Offers Have Similar Costs
Fact: Loan offers can differ significantly in interest rates, fees, repayment terms, and other charges.
Compare these details before accepting an offer:
-
Interest rate: Understand how interest is calculated.
-
APR: Review the overall annualised cost.
-
Processing fees: Check the amount and applicable taxes.
-
Tenure: Understand how long repayment will continue.
-
EMI: Confirm that the payment fits your budget.
-
Late-payment charges: Read the applicable terms.
-
Prepayment conditions: Check whether early repayment is allowed and whether charges apply.
The RBI's Key Facts Statement framework is intended to help eligible borrowers understand important loan terms and costs before making a decision.
10. Myth: Digital Loans Are Always Approved Instantly
Fact: A digital application does not guarantee instant approval or disbursement.
A lender may need to verify the applicant's identity, income, bank details, credit profile, and other information. Incomplete documents or additional checks can delay a decision.
Be careful with messages claiming that approval is guaranteed if you pay an advance fee to an agent. Use verified official channels and read the loan agreement before accepting an offer.
11. Myth: Gig Workers Do Not Need to Check Their Credit Reports
Fact: Credit reports can help applicants understand how lenders may view their borrowing history.
Before applying, consider:
-
Reviewing your credit report for incorrect information
-
Checking whether old loans are shown as closed when appropriate
-
Paying current EMIs on time
-
Reducing outstanding debt where possible
-
Avoiding unnecessary applications
-
Keeping copies of repayment receipts
A limited credit history does not automatically mean every lender will reject an applicant, but available products and terms can vary.
12. How Gig Workers in Andhra Pradesh Can Improve Their Loan Readiness
Whether you work in Vijayawada, Guntur, Tirupati, Visakhapatnam, Kurnool, or another part of Andhra Pradesh, preparation can make the application process clearer.
-
Track earnings: Maintain a record of income received from different platforms or customers.
-
Maintain bank records: Use consistent, accurate records to demonstrate cash flow.
-
Review current debt: Calculate how much income is already committed to EMIs.
-
Choose a realistic loan amount: Borrow for a specific need rather than accepting the maximum offered.
-
Compare lenders: Review eligibility, APR, fees, and repayment conditions.
-
Verify the lender: Confirm which bank or NBFC is actually providing the loan.
-
Read the KFS and agreement: Understand the total cost and obligations before signing.
13. Digital Lending Safety Checklist
Before submitting an online loan application, confirm the following:
-
The actual lender is clearly identified.
-
The lender's relationship with the app or platform can be verified.
-
The KFS and loan agreement disclose important terms.
-
The APR, fees, EMI, and repayment dates are clear.
-
You understand the data permissions being requested.
-
You have not been asked to share your OTP, PIN, or password.
-
You are not being pressured to transfer money to a personal account to secure approval.
The RBI's digital lending rules include borrower-protection requirements around disclosures, data consent, and lending arrangements. Consult official RBI information for the applicable requirements.

14. Benefits and Limitations of Loans for Gig Workers
|
Potential benefits |
Potential limitations |
|---|---|
|
May help cover essential expenses |
Approval is not guaranteed |
|
Can provide funds for planned purchases |
Interest and fees increase repayment costs |
|
Responsible repayment may support credit history |
Irregular earnings can make payments difficult |
|
Some lenders may accept alternative income evidence |
Documentation requirements vary |
|
Digital applications may be convenient |
Unverified apps and misleading offers pose risks |
A loan should support a manageable financial need—not create a cycle of borrowing to repay previous borrowing.
15. Frequently Asked Questions (FAQs)
1. Can gig workers in Andhra Pradesh get personal loans?
Yes, they may qualify for suitable loan products if they meet the lender's eligibility requirements. Approval depends on factors such as income, credit history, existing debt, and documentation.
2. Is a salary slip compulsory for gig workers?
Not always. Some lenders may accept bank statements or platform earnings records, while others may require different documents.
3. Does a good credit score guarantee loan approval?
No. A good credit score can help, but the lender may also assess income, existing EMIs, affordability, and other criteria.
4. Can delivery partners apply for loans?
Delivery partners may apply for eligible products if they satisfy the lender's requirements and provide acceptable evidence of income.
5. What documents may be needed?
Commonly requested documents include PAN, accepted identity and address proof, bank statements, and earnings records. Requirements vary by lender.
6. Can gig workers with irregular income qualify?
They may qualify, depending on the lender's assessment. Accurate income records can help demonstrate their financial position.
7. Are instant loan apps safe?
Not all apps are safe. Verify the actual regulated lender, check the app's relationship with that lender, and read the loan terms before proceeding.
8. Does applying for multiple loans improve approval chances?
Not necessarily. Multiple applications do not guarantee approval and may result in additional credit enquiries.
9. Is the lowest EMI always the best option?
No. A longer tenure may reduce the EMI but increase total interest. Compare the overall borrowing cost.
10. Can I get a loan without a credit history?
Some lenders may consider applicants with limited credit history, but availability, eligibility, and terms vary.
11. What happens if I miss an EMI?
A missed payment may lead to applicable charges and affect your credit history. Contact your lender promptly if you expect difficulty paying.
12. Should gig workers pay an advance fee to guarantee approval?
Be cautious. A guaranteed-approval claim tied to a suspicious upfront payment can be a warning sign. Verify all charges through the lender's official channels.
13. Can gig workers apply online?
Some banks and NBFCs offer online applications. Use verified channels and confirm the identity of the actual lender.
14. How can gig workers improve loan eligibility?
Maintain accurate income records, pay existing debts on time, review credit reports, reduce unnecessary debt, and apply for an amount that fits your repayment capacity.
15. Where can I check official digital lending guidance?
Visit the Reserve Bank of India website for digital lending regulations and borrower-protection information.
Conclusion
Loan myths can prevent gig workers from exploring suitable financial options or encourage them to trust unsafe offers. The important facts are that eligibility varies by lender, alternative income documents may be accepted, and a credit score alone does not guarantee approval.
Gig workers in Andhra Pradesh should keep accurate earnings records, compare the full cost of borrowing, verify the lender, and read the KFS before accepting a loan.
Vizzve Financial reminder: Make financial decisions based on verified terms and your actual repayment capacity—not promises of guaranteed approval.
Published on : 18th October
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed