

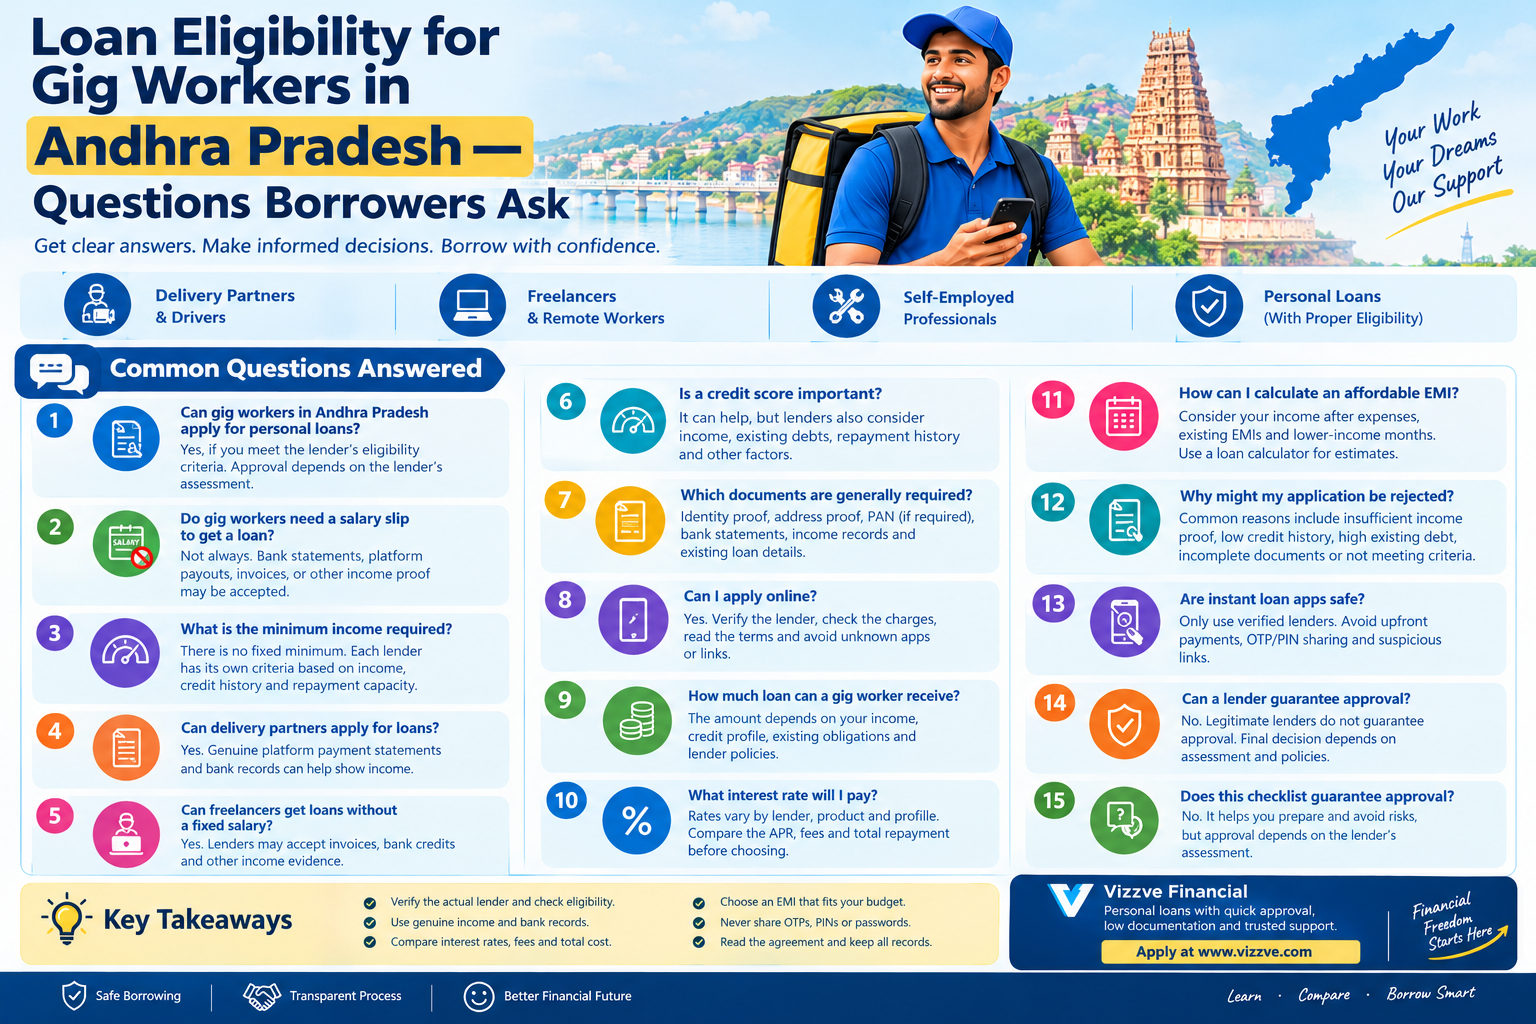
Gig work has created income opportunities for delivery partners, cab drivers, freelancers, home-service professionals, and other platform-based workers across Andhra Pradesh. However, when these workers need a personal loan, they may have questions about eligibility, income proof, credit scores, interest rates, and repayment requirements.
Unlike salaried employees, gig workers may receive payments at different intervals and may not have traditional salary slips. Lenders can assess their applications using different criteria, including bank transactions, earnings records, credit history, and repayment capacity.
This guide answers common questions borrowers ask about loan eligibility for gig workers in Andhra Pradesh, helping readers understand what to prepare before applying.
AI Answer Box: Can Gig Workers in Andhra Pradesh Get a Personal Loan?
Yes, gig workers in Andhra Pradesh may qualify for a personal loan if they meet the lender’s eligibility requirements. Depending on the lender, they may need identity and address proof, bank statements, gig-platform payment records, and evidence of regular income.
Approval, loan amount, interest rate, and repayment period depend on the lender’s policies, credit assessment, income stability, and existing financial obligations. No particular loan amount or approval is guaranteed.
Why Do Gig Workers Have Questions About Loan Eligibility?
Gig workers often have different financial circumstances from salaried employees. Their earnings can change because of working hours, demand, incentives, platform fees, fuel costs, and other business expenses.
Common concerns include:
-
Whether a salary slip is compulsory.
-
How lenders evaluate irregular earnings.
-
Whether a low or limited credit history affects approval.
-
Which documents should be submitted.
-
How to calculate an affordable EMI.
-
How to identify legitimate digital lenders.
-
What to do if a loan application is rejected.
Understanding these points before applying can help borrowers make informed financial decisions.
Frequently Asked Questions: Loan Eligibility for Gig Workers
1. Can gig workers in Andhra Pradesh apply for personal loans?
Yes. Gig workers such as delivery partners, cab drivers, freelancers, and platform-based service providers can apply for personal loans. The lender will assess their income, documents, credit profile, repayment capacity, and other eligibility requirements.
2. Do gig workers need a salary slip to get a loan?
Not always. Some lenders may accept alternative income evidence, such as bank statements, platform earnings reports, invoices, or payment records. Requirements differ by lender, so applicants should confirm the accepted documents before applying.
3. What is the minimum income required for a gig worker loan?
There is no single minimum income requirement for every lender. Some providers may specify a minimum monthly income, while others consider income patterns, existing debts, credit history, and repayment capacity.
Always check the actual lender’s current eligibility criteria.
4. Can delivery partners apply for personal loans?
Delivery partners working with food delivery, e-commerce, grocery, or other service platforms may apply if they satisfy the lender’s requirements. Genuine platform payment statements and bank transactions may help demonstrate income.
5. Can freelancers get loans without a fixed monthly salary?
Potentially, yes. Some lenders assess freelancers using bank statements, invoices, contracts, transaction history, or other evidence of earnings. Irregular income may affect the lender’s decision and the loan terms offered.
6. Is a credit score important for gig workers?
A credit score can be an important part of the assessment. Lenders may also review repayment history, existing loans, income evidence, and other factors. A strong score does not guarantee approval, and a limited credit history does not automatically mean every lender will reject the application.
7. Which documents are generally required?
Depending on the lender, applicants may need:
-
Identity proof, such as an accepted government-issued document.
-
PAN, where required.
-
Address proof.
-
Recent bank statements.
-
Gig-platform earnings records or payment statements.
-
Freelance invoices or business transaction records, where relevant.
-
Details of existing loans and repayment commitments.
Only submit genuine documents through verified channels.
8. Can a gig worker apply online?
Yes, many lenders offer online applications. Before uploading documents, verify the lender’s identity, understand its privacy practices, check all charges, and read the loan terms. Avoid unfamiliar apps or links that promise guaranteed approval.
9. How much loan can a gig worker receive?
The eligible amount depends on the lender’s policies and assessment of the applicant’s income, credit profile, existing obligations, and repayment capacity. Do not assume that a particular income level guarantees a specific loan amount.
10. What interest rate will a gig worker pay?
Interest rates vary by lender, loan product, applicant profile, and prevailing terms. Compare the annual interest rate, processing fees, applicable taxes, and total repayment amount rather than choosing a loan based only on an advertised rate.
11. How can gig workers calculate an affordable EMI?
Start by estimating reliable monthly income after work-related expenses, such as fuel, vehicle maintenance, platform charges, and equipment costs. Subtract essential household expenses and existing debt repayments before deciding whether a new EMI is manageable.
Because earnings can fluctuate, leave room for lower-income periods and unexpected expenses.
12. Can gig workers apply if they have an existing loan?
Possibly. The lender may consider the outstanding balance, current EMIs, payment history, and income available after existing obligations. Taking on another loan is sensible only if the additional repayment remains affordable.
13. Why might a gig worker’s loan application be rejected?
Possible reasons include insufficient income evidence, a low or limited credit history, high existing debt, inconsistent bank transactions, incomplete documentation, or not meeting the lender’s eligibility criteria.
Applicants should ask the lender about the reason for rejection, correct any errors, and avoid submitting repeated applications without addressing the underlying issue.
14. Are instant loan apps safe for gig workers?
Not all apps are legitimate. Verify the actual bank or Non-Banking Financial Company (NBFC) providing the loan, review the agreement and privacy policy, and check the provider’s official contact and grievance details.
Never share an OTP, PIN, or password with an unknown person. Avoid suspicious advance-fee demands and offers that guarantee approval without checks.
15. How can gig workers improve their chances of loan approval?
Applicants can improve their preparation by maintaining accurate income records, keeping bank transactions organized, paying existing EMIs on time, reducing unnecessary debt, checking their credit report for errors, and applying for an amount that fits their repayment capacity.
These steps can support a stronger application but cannot guarantee approval.
Quick Comparison: Salaried Employees vs Gig Workers
|
Factor |
Salaried employee |
Gig worker |
|---|---|---|
|
Income pattern |
Often fixed monthly salary |
May vary by day, week, or month |
|
Salary slip |
Commonly available |
May not be available |
|
Alternative income proof |
May be less necessary |
May include platform payouts or invoices |
|
Credit assessment |
Depends on the lender |
Depends on the lender |
|
Repayment planning |
Based on regular take-home pay |
Should account for income fluctuations |
|
Loan approval |
Not guaranteed |
Not guaranteed |
Both groups must satisfy the selected lender’s eligibility criteria.
Documents Checklist for Gig Workers
Use this practical list before applying.
Application preparation
0/8 checked
This is a general preparation list, not a universal document requirement. Confirm the actual lender’s requirements before applying.
Example: A Gig Worker Planning a Loan
Consider a delivery partner in Visakhapatnam who earns different amounts each week and needs money for a vehicle repair.
Before applying, the worker should:
-
Review recent platform earnings and bank statements.
-
Estimate income after fuel and maintenance costs.
-
Check current household expenses and existing EMIs.
-
Compare offers from verified lenders.
-
Calculate whether the proposed EMI remains manageable during a slow month.
-
Read the loan agreement and check all applicable charges before accepting.
This is an illustrative example, not a real borrower testimonial or a promise of loan approval.
Common Mistakes Borrowers Should Avoid
-
Assuming every lender follows the same eligibility criteria.
-
Applying without checking income-document requirements.
-
Providing inaccurate income or employment information.
-
Borrowing more than necessary.
-
Ignoring processing fees and other charges.
-
Accepting a loan without reading the agreement.
-
Trusting unsolicited offers that promise guaranteed approval.
-
Sharing confidential information with unverified agents.
-
Taking a new loan without accounting for existing EMIs.
How Vizzve Can Help Borrowers Make Informed Decisions
Vizzve-related financial education content can help readers understand loan eligibility, documentation, EMI planning, and responsible borrowing.
Before proceeding with any specific loan offer associated with Vizzve, verify the actual lender, current eligibility requirements, charges, loan terms, and official application channel. Do not rely on assumed interest rates or guaranteed approval claims.
Conclusion
Understanding loan eligibility is an important first step for gig workers in Andhra Pradesh. Whether you work as a delivery partner, driver, freelancer, or platform-based professional, organize your income records, compare loan terms, verify the lender, and plan repayments realistically.
Borrow smart, check every term, and choose a loan only when the repayment fits your budget.
Published on : 16th October
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed