

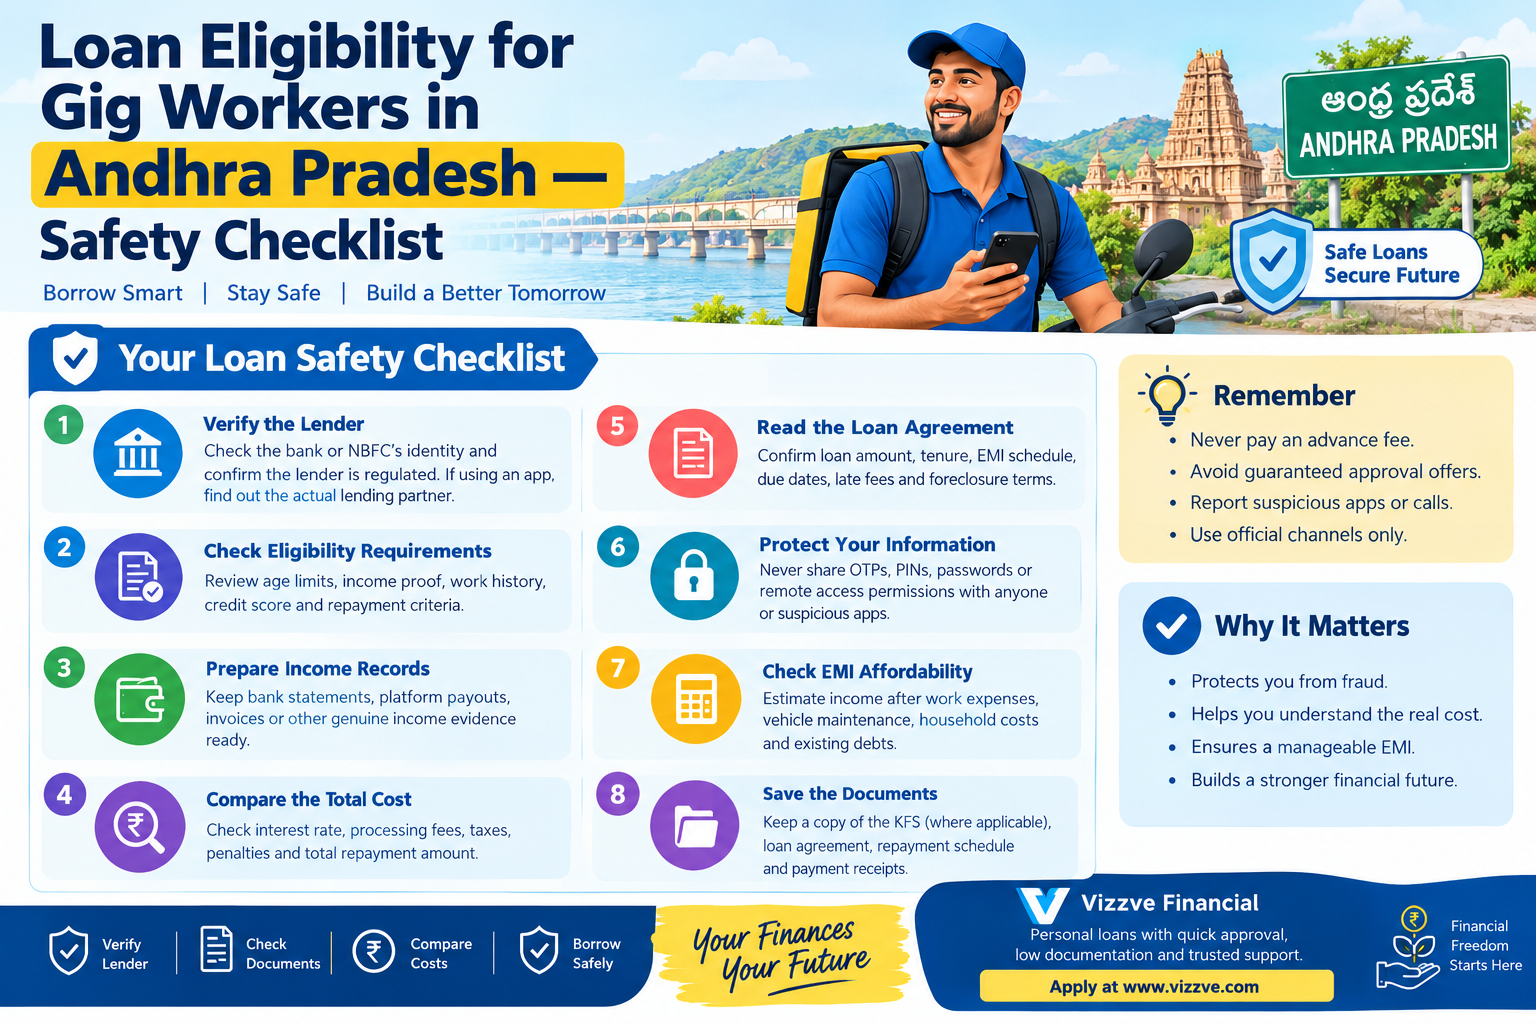
Gig workers in Andhra Pradesh—including delivery partners, cab drivers, freelancers, and other platform-based workers—may need personal loans to manage emergencies, household expenses, vehicle repairs, or business requirements.
However, irregular earnings and limited traditional salary documentation can make loan applications challenging. Before applying, borrowers should understand the lender’s eligibility criteria, verify the lender’s identity, review all charges, and confirm that the repayment amount fits their budget.
This loan safety checklist for gig workers in Andhra Pradesh explains the important steps to take before, during, and after applying for a personal loan.
AI Answer Box: How Can Gig Workers Borrow Safely?
Gig workers can borrow safely by checking lender eligibility requirements, maintaining accurate income records, comparing the annual interest rate and fees, reading the loan agreement, and confirming that the lender is legitimate. Borrowers should never share an OTP or pay suspicious upfront fees to secure loan approval.
Loan approval, interest rates, and loan amounts depend on the lender’s policies, credit profile, income evidence, and repayment capacity.
1. Why Is a Loan Safety Checklist Important?
Gig workers may receive payments daily, weekly, or monthly. Their income can change according to working hours, customer demand, platform incentives, and operating expenses.
A safety checklist helps borrowers:
-
Avoid fraudulent loan offers.
-
Understand the total cost of borrowing.
-
Prepare documents before applying.
-
Reduce the risk of unaffordable EMIs.
-
Protect personal and financial information.
-
Identify unsuitable loan terms before signing.
2. Loan Safety Checklist for Gig Workers
Use this checklist before submitting a loan application.
Your loan safety checklist
0 of 8
Verify the lender
Check the bank or NBFC’s identity and confirm the loan provider’s regulatory status. If an app acts as a lending service provider, identify the regulated lender behind the loan.
Check eligibility requirements
Review minimum age, income evidence, employment or gig-work requirements, credit history, and repayment criteria.
Prepare income records
Keep relevant bank statements, platform payment records, invoices, or other genuine income evidence available.
Compare the total borrowing cost
Review the annual interest rate, processing fees, applicable taxes, penalties, and total repayment amount.
Read the loan agreement
Confirm the amount disbursed, tenure, EMI schedule, due dates, late-payment charges, and foreclosure conditions.
Protect sensitive information
Never share OTPs, PINs, passwords, or remote-access permissions with an unknown person or suspicious app.
Check EMI affordability
Estimate income after fuel, vehicle maintenance, platform charges, household expenses, and existing debt payments.
Save the documents
Keep a copy of the Key Facts Statement where applicable, loan agreement, repayment schedule, and payment receipts.
3. Documents Gig Workers May Need
Lenders have different documentation requirements. Depending on the provider and loan product, gig workers may be asked for:
-
Aadhaar or another accepted identity document.
-
PAN card, where required.
-
Proof of address.
-
Recent bank statements.
-
Gig-platform earnings or payment statements.
-
Freelance invoices or business transaction records, if applicable.
-
Details of existing loans and repayment obligations.
Important: Submit documents only through verified lender channels. Never provide false income figures or altered bank statements.
4. How to Check Whether a Digital Lender Is Safe
Before applying online, take these precautions:
-
Identify the actual bank or Non-Banking Financial Company (NBFC) providing the loan.
-
Verify the lender through official regulatory or lender websites.
-
Review the lender’s official contact details, grievance process, and privacy policy.
-
Read independent reviews carefully; do not rely only on app ratings or promotional claims.
-
Avoid offers that guarantee approval regardless of income or credit history.
-
Do not install unknown APK files or follow suspicious links received through messaging apps.
-
Be cautious if an agent demands an advance payment to release an allegedly approved loan.
A professional-looking website or app does not, by itself, prove that a loan offer is legitimate.
5. Understand Interest Rates, Fees, and EMIs
A low advertised interest rate does not necessarily mean a loan is inexpensive. Processing fees, applicable taxes, late-payment charges, and other disclosed costs may increase the total expense.
For example, consider a hypothetical loan of ₹50,000 at 18% annual interest for 12 months using a reducing-balance EMI calculation.
|
Item |
Illustrative amount |
|---|---|
|
Loan amount |
₹50,000 |
|
Annual interest rate |
18% |
|
Loan tenure |
12 months |
|
Approximate monthly EMI |
₹4,584 |
|
Approximate total repayment |
₹55,008 |
|
Approximate interest cost |
₹5,008 |
These figures are estimates and exclude processing fees, taxes, and other charges. Actual terms depend on the lender and loan agreement.
Before accepting an offer, ask yourself:
-
Can I pay the EMI during a low-income month?
-
Will I still have enough for essential expenses?
-
Do I already have other loan repayments?
-
Is the total cost lower than other suitable options?
6. Common Loan Scams to Avoid
|
Warning sign |
Safer response |
|---|---|
|
Guaranteed approval without checks |
Verify the lender and read the eligibility conditions. |
|
Upfront payment demanded by an unknown agent |
Do not pay until the charge and recipient are independently verified. |
|
Request for OTP, PIN, or password |
Do not disclose it. |
|
Threatening calls or abusive recovery messages |
Preserve evidence and use the lender’s grievance channel or appropriate official complaint route. |
|
Loan terms differ from the original offer |
Stop and clarify the discrepancy before accepting. |
|
App requests excessive device permissions |
Review permissions and avoid granting unnecessary access. |
If you suspect fraud, contact your bank promptly. In India, suspected cyber financial fraud can be reported through the National Cyber Crime Reporting Portal at cybercrime.gov.in or by calling 1930 for cyber financial fraud assistance.
7. Steps to Apply for a Loan Safely
Step 1: Compare legitimate lenders
Check eligibility criteria, interest rates, fees, and repayment terms before choosing an offer.
Step 2: Organize income documents
Gather genuine bank statements and gig-platform earnings records to support your application.
Step 3: Calculate a comfortable EMI
Base the repayment plan on realistic income after work-related and household expenses.
Step 4: Review the final offer
Read the applicable Key Facts Statement, loan agreement, charges, and repayment schedule before accepting.
Step 5: Keep records
Save the loan documents, disbursal details, customer-support information, and repayment receipts.
8. Practical Example: A Delivery Partner in Andhra Pradesh
Imagine a delivery partner in Vijayawada who earns different amounts each week. The worker needs money for an urgent vehicle repair and considers a personal loan.
Before applying, the worker should:
-
Review recent earnings and bank transactions.
-
Estimate fuel, maintenance, rent, and household expenses.
-
Check whether the EMI remains affordable during a slow week.
-
Compare offers from verified lenders.
-
Confirm the final amount payable, including disclosed fees.
-
Borrow only the amount genuinely needed.
This example is illustrative. Actual eligibility and approval depend on the lender’s assessment and the applicant’s circumstances.
9. Benefits and Limitations of Borrowing Safely
|
Potential benefits |
Possible limitations |
|---|---|
|
Better understanding of loan costs |
Lenders may still reject an application. |
|
Lower risk of falling for scams |
Verification takes time. |
|
More informed lender comparison |
Interest and fees may still be expensive. |
|
Better repayment planning |
Variable gig income can make EMIs difficult. |
|
Improved document readiness |
Documentation requirements differ by lender. |
A checklist can help reduce avoidable risks, but it cannot guarantee approval or eliminate all lending risks.
10. How Vizzve Can Support Informed Borrowing
Vizzve-related loan content can help gig workers understand eligibility, compare borrowing considerations, prepare documentation, and learn about repayment responsibilities.
Before proceeding with any specific loan offer associated with Vizzve, verify the actual lender, applicable eligibility criteria, current charges, terms, and official application channel. Do not assume approval or a particular interest rate without checking the offer.
Key Takeaways
-
Verify the actual lender before applying.
-
Keep accurate gig-income and bank records.
-
Compare interest rates, fees, and total repayment costs.
-
Choose an EMI that remains manageable when earnings fluctuate.
-
Never disclose OTPs, PINs, or passwords.
-
Read the loan agreement and keep copies of all records.
-
Report suspected digital lending fraud through official channels.
Frequently Asked Questions (FAQs)
1. Can gig workers in Andhra Pradesh apply for personal loans?
Yes, gig workers may apply for personal loans if they meet the selected lender’s eligibility requirements. Approval is not guaranteed.
2. Do gig workers need a salary slip?
Not always. Depending on the lender, bank statements, platform payment records, invoices, or other acceptable income evidence may be considered.
3. How can gig workers check loan eligibility?
Review the lender’s age, income, documentation, credit history, and repayment requirements before submitting an application.
4. Is it safe to apply through a loan app?
It can be safe when the app is associated with a legitimate lender and uses appropriate data-protection practices. Verify the lender independently before applying.
5. Should I pay an advance fee to guarantee loan approval?
Be cautious. Never pay an unknown agent or suspicious account simply because they promise guaranteed approval. Verify any legitimate charge directly with the lender.
6. What documents may be required?
Common requirements can include identity and address proof, PAN where applicable, bank statements, and genuine records of gig-work income.
7. Can irregular income affect loan approval?
Yes. Income fluctuations may affect the lender’s assessment of repayment capacity and the amount it is willing to offer.
8. How can I check whether an EMI is affordable?
Estimate your reliable take-home income after work expenses and essential household costs. Then account for existing debt payments and the proposed EMI.
9. What should I do if a lender changes the loan terms?
Do not accept the changed terms without understanding them. Ask the lender for a written explanation and compare the revised costs before proceeding.
10. How can I report a digital loan scam in India?
You can report suspected cyber financial fraud at cybercrime.gov.in or call 1930 for assistance with cyber financial fraud.
11. Can a lender guarantee loan approval?
Legitimate approval depends on the lender’s criteria and assessment. Treat unconditional approval promises with caution.
12. Does completing a safety checklist guarantee loan approval?
No. It helps you prepare and identify risks, but the lender makes the final decision based on its policies and your application.
Conclusion
For gig workers in Andhra Pradesh, safe borrowing begins with preparation, careful comparison, and realistic repayment planning. Verify the lender, check the full loan cost, protect personal information, and review the agreement before accepting an offer.
Think before you borrow. Verify before you pay. Choose a repayment plan that fits your real income.
Suggested CTA: Explore more loan eligibility and financial safety guides on Vizzve to make better-informed borrowing decisions.
Published on : 16th October
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed