

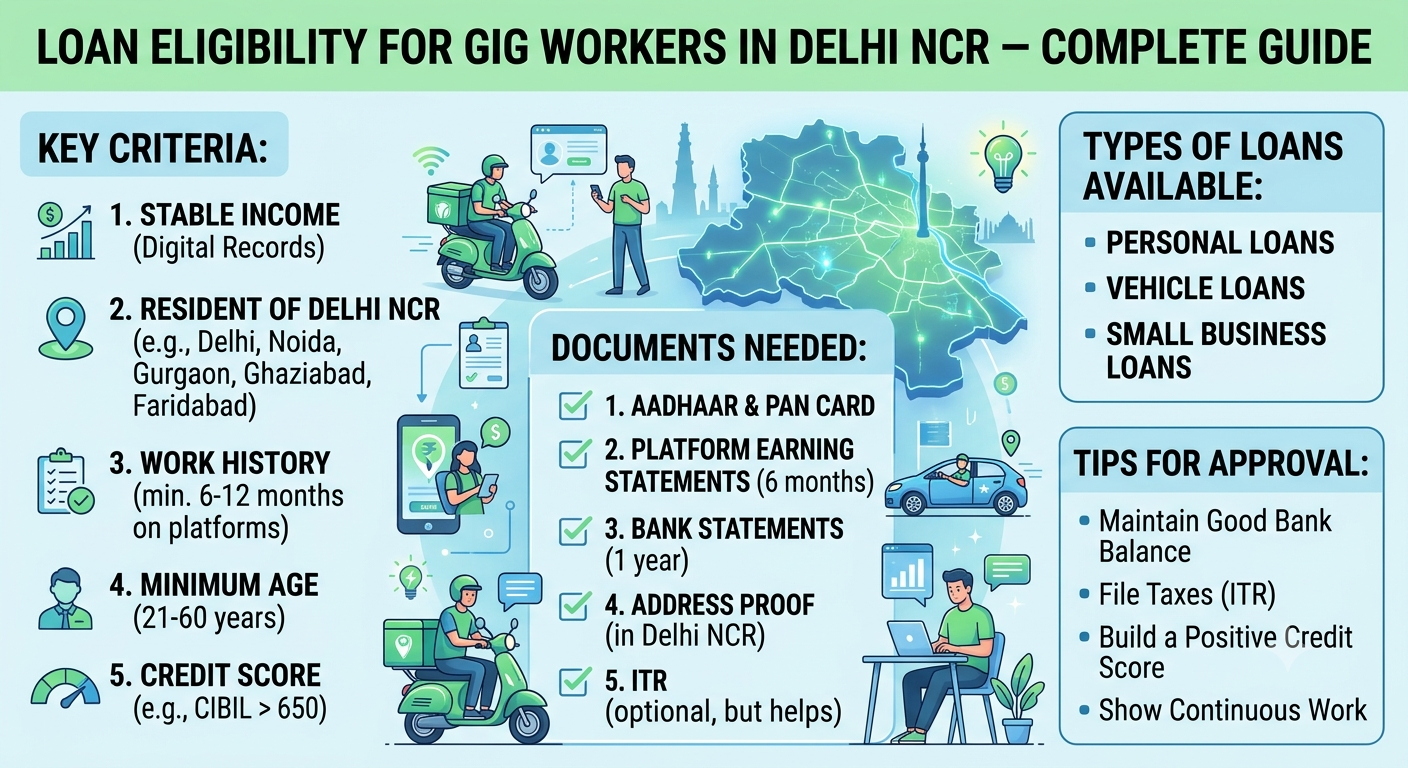
Gig workers are an important part of Delhi NCR’s economy. Delivery partners, cab drivers, e-commerce delivery agents, freelancers and other platform-based workers often depend on daily or weekly earnings rather than a fixed monthly salary.
This flexible working arrangement can make borrowing more complicated. Some lenders may ask for salary slips or employer certificates that gig workers do not have. However, not having a traditional salary slip does not automatically make a gig worker ineligible for a loan. Eligibility depends on the lender's policy, documented income, repayment capacity, credit history and other assessment criteria.
This guide explains how gig workers in Delhi, Noida, Gurugram, Ghaziabad and Faridabad can understand their loan eligibility, prepare documents and compare borrowing options responsibly.
What Is Loan Eligibility for Gig Workers?
Loan eligibility refers to the conditions a lender uses to determine whether an applicant qualifies for credit and how much they may be able to borrow.
For gig workers, lenders may evaluate several factors:
-
Age and identity verification
-
Residence and serviceability of the applicant's location
-
Regularity and stability of income
-
Bank statements and available earnings records
-
Credit score and previous repayment behaviour
-
Existing EMIs and other financial obligations
-
The requested loan amount and repayment period
Eligibility criteria differ between banks, non-banking financial companies (NBFCs) and other authorised lending arrangements. Meeting the basic requirements does not guarantee loan approval.
Who Can Apply for a Gig Worker Loan in Delhi NCR?
Depending on the lender's product and eligibility policy, the following workers may be able to apply.
1. Delivery Partners
Workers delivering food, groceries, parcels and e-commerce orders may be able to document earnings through platform statements, bank credits and other accepted records.
2. App-Based Cab and Auto Drivers
Drivers working through ride-hailing platforms may use earnings statements, bank statements and other business-income records to demonstrate their repayment capacity.
3. Freelancers and Independent Contractors
Freelancers earning from multiple clients may be assessed using invoices, payment receipts, bank statements and income-tax documents, where available and accepted.
4. Other Platform Workers
Task-based workers, home-service professionals and independent service providers may also qualify for suitable credit products if they meet the lender's requirements.
Important: A lender may accept some of these records but not others. Confirm its documentation policy before submitting an application.
Key Eligibility Factors
| Eligibility factor | What lenders may assess |
|---|---|
| Age | Whether the applicant falls within the lender's permitted age range |
| Income | Amount, frequency and consistency of earnings |
| Bank transactions | Whether income and existing obligations can be verified |
| Credit history | Previous loans, repayment records and credit utilisation |
| Existing EMIs | How much income is already committed to debt |
| Work history | Duration of gig work or available earnings records |
| Location | Whether the applicant's address is within the lender's service area |
| Documents | Whether identity, address and income details can be verified |
There is no single income threshold or credit score that guarantees approval across all lenders. Check the specific lender's published requirements.
Documents Required for Gig Worker Loans
Preparing documents in advance can make the application process smoother.
Identity and Address Proof
Commonly requested documents may include:
-
PAN card, where required
-
Aadhaar or another accepted identity document
-
Current address proof, where required
-
Recent photograph or digital verification, if requested
Submit only the documents required through the lender's verified application channel.
Income Proof
Gig workers may be able to provide one or more of the following, depending on the lender:
-
Recent bank statements
-
Earnings statements from delivery or ride-hailing platforms
-
Payment records and transaction histories
-
Client invoices and payment receipts
-
Income-tax returns or other financial records, where applicable
Bank Account Details
A bank account that receives regular work-related payments can help establish an income trail. Keep records accurate and avoid altering statements or documents.
Credit Information
The lender may review your credit history through a credit bureau, subject to applicable requirements. Check your credit report for errors before applying.
How to Improve Loan Eligibility
Gig workers can take practical steps to present a clearer financial profile.
Maintain a Consistent Income Trail
Where practical, receive work-related payments through a bank account and retain platform earnings statements. This can help demonstrate the amount and frequency of income.
Separate Business and Personal Records
Keeping clear records of work-related receipts, fuel, vehicle maintenance and other expenses can make it easier to understand your actual take-home income.
Review Your Credit Report
Check for incorrect loan entries, unfamiliar accounts or wrongly reported missed payments. Raise disputes through the relevant credit bureau or lender if necessary.
Reduce Existing Debt Where Possible
Multiple outstanding EMIs can reduce the amount available for another repayment. Consider your current obligations before applying for additional credit.
Choose a Realistic Loan Amount
Request an amount based on your verified income and essential expenses rather than the maximum amount advertised.
Avoid Multiple Unplanned Applications
Submitting many applications within a short period may lead to multiple credit enquiries, depending on the lender and product. Compare eligibility requirements first and apply selectively.
Step-by-Step Loan Application Process
Step 1: Estimate your take-home income. Calculate average earnings after fuel, vehicle maintenance, platform-related costs and other work expenses.
Step 2: Check the lender's criteria. Review minimum and maximum age, accepted income proof, service locations, credit requirements and applicable charges.
Step 3: Prepare your documents. Keep identity, address, bank and income records ready in the required format.
Step 4: Calculate an affordable EMI. Account for rent, food, family expenses, fuel, existing EMIs and savings.
Step 5: Apply through a verified channel. Confirm which regulated bank or NBFC will provide the loan and review the lender's terms.
Step 6: Read the loan documents. Check the interest rate, annual percentage rate (APR), processing fee, repayment schedule, late-payment charges and other applicable costs.
Step 7: Review the final offer. Borrow only if the amount, terms and instalments suit your financial situation.
Step 8: Keep repayment records. Track due dates and retain receipts, statements and the loan agreement.
Loan Eligibility Across Delhi NCR
Delhi NCR includes several cities and employment hubs. Local availability, lender service areas and address verification requirements may differ.
| Location | Examples of gig work | What to prepare |
|---|---|---|
| Delhi | Food delivery, courier services, cab driving and freelancing | Earnings records, bank statements and accepted address proof |
| Noida | E-commerce delivery, transport and service work | Platform statements and evidence of income |
| Gurugram | Ride-hailing, delivery, home services and freelance work | Income records, bank statements and existing EMI details |
| Ghaziabad | Parcel delivery, transport and independent services | Consistent payment records and identity documents |
| Faridabad | Delivery services, drivers and independent work | Earnings history and documents requested by the lender |
These examples describe common types of work, not guaranteed lending availability. Confirm that the selected lender serves your area.
Understanding Loan Costs and Repayment
Loan approval is only one part of borrowing responsibly. The total cost of the loan and the size of the EMI are equally important.
What to Compare Before Borrowing
| Cost or term | Why it matters |
|---|---|
| Interest rate | Determines interest charged on the outstanding principal |
| APR | Helps show the annualised overall cost, subject to the applicable calculation |
| Processing fee | May increase the upfront or overall borrowing cost |
| Loan tenure | A longer tenure may lower the EMI but increase total interest |
| Late-payment charges | Can increase the cost of missed or delayed payments |
| Foreclosure or prepayment terms | Affect the cost of repaying early, where permitted |
| Disbursal amount | Confirm how much you will actually receive after applicable deductions |
Illustrative EMI Example
Suppose a gig worker borrows ₹30,000 at an illustrative interest rate of 18% per year for 12 months, using a standard monthly reducing-balance calculation.
-
Approximate monthly EMI: ₹2,752
-
Approximate total of 12 EMIs: ₹33,024
-
Approximate interest paid: ₹3,024
These figures are estimates, not a loan offer. Fees, taxes, actual lender calculations and different repayment terms can change the total amount payable.
Before accepting an offer, compare the EMI against your average take-home income, not your highest earning day.
Safety Checklist for Digital Loans
The Reserve Bank of India (RBI) issued the Reserve Bank of India (Digital Lending) Directions, 2025 to consolidate and strengthen requirements for regulated digital lending. Borrowers should still verify the specific lender and terms before proceeding. See the RBI Digital Lending Directions, 2025.
Use these precautions:
-
Verify the bank or NBFC named in the loan agreement.
-
Check the relevant digital lending app against the RBI's public directory where applicable.
-
Read the Key Facts Statement and review the APR and charges.
-
Do not pay an unknown person a fee to “guarantee” loan approval.
-
Never share your OTP, UPI PIN or banking password.
-
Review app permissions and provide only necessary information with informed consent.
-
Keep a copy of the loan agreement, repayment schedule and payment receipts.
-
Use official grievance channels if you encounter misleading terms or improper recovery behaviour.
The Ministry of Finance has also highlighted consumer-protection measures and reporting options for fraudulent loan apps. For suspected cyber fraud in India, visit the National Cyber Crime Reporting Portal or call 1930 for the cybercrime helpline.
Common Reasons a Gig Worker Loan May Be Rejected
A lender may reject an application because of:
-
Insufficient or unverifiable income.
-
Incomplete or inconsistent documents.
-
A credit history that does not meet its requirements.
-
High existing debt obligations.
-
An application amount that exceeds assessed repayment capacity.
-
An address or work location outside its service area.
-
Information that does not match across the application and supporting records.
If an application is rejected, ask for the reason where available, correct errors and reassess affordability before applying elsewhere. Avoid taking expensive credit simply to cover another loan's EMI.
Real-World Example: A Delivery Partner in Noida
Consider a hypothetical delivery partner earning ₹28,000 in an average month before work-related expenses. After fuel, maintenance and other essential costs, the worker estimates take-home earnings of ₹20,000.
The worker already pays ₹3,000 per month toward an existing loan and household expenses of ₹11,000. That leaves approximately ₹6,000 before savings and unexpected costs.
A new EMI of ₹4,000 would consume a large portion of the remaining amount. A prudent approach would be to review the budget, preserve an emergency buffer and consider a smaller loan—or postpone borrowing—if the proposed EMI leaves too little room for income fluctuations.
This example is illustrative only. It does not represent a lender's eligibility formula or an approval promise.
Benefits and Limitations of Loans for Gig Workers
Potential Benefits
-
Access to funds for planned personal or emergency expenses.
-
An opportunity to build repayment history when credit is reported and payments are made on time.
-
Flexible application processes offered by some digital lenders.
-
The possibility of using alternative income records where the lender accepts them.
Potential Limitations
-
Variable income can make fixed monthly repayments difficult.
-
Interest rates and fees may vary significantly between lenders.
-
A thin or poor credit history can limit available options.
-
Frequent borrowing can increase financial pressure.
-
Digital convenience does not guarantee approval, affordability or safety.
Key Takeaways
-
Gig workers in Delhi NCR may qualify for loans even without conventional salary slips, depending on the lender.
-
Income consistency, bank statements, platform earnings records and repayment capacity can be important.
-
Requirements differ between lenders; there is no universal approval threshold.
-
Compare APR, fees, tenure and total repayment—not just the advertised interest rate.
-
Verify the lender, protect personal data and avoid guaranteed-approval claims.
-
Choose an EMI that remains manageable during lower-income weeks.
Frequently Asked Questions (FAQs)
1. Can gig workers get a personal loan in Delhi NCR?
Yes, some lenders may offer loans to eligible gig workers. Approval depends on their income verification, credit profile, documentation, repayment capacity and the lender's policy.
2. Can I apply without a salary slip?
Possibly. Some lenders accept bank statements, platform earnings records, invoices or other income documents. Confirm the accepted alternatives before applying.
3. What documents are required for a gig worker loan?
Common requirements include identity and address proof, bank statements, income records and PAN details where required. The exact list depends on the lender.
4. Is a credit score compulsory?
Requirements vary by lender and loan product. Some lenders rely on credit bureau information, while other aspects of the applicant's profile may also be considered. A particular score does not guarantee approval.
5. Can delivery partners apply for loans?
Delivery partners can apply for products whose eligibility rules cover their employment or income type. They should retain payment records and confirm which documents the lender accepts.
6. Can app-based cab drivers apply for personal loans?
Potentially, if the lender accepts their income documentation and they meet its other requirements. Earnings statements and bank records may help establish income.
7. Can freelancers with multiple clients apply?
Some lenders accept freelancer or self-employed income. Applicants may be asked for bank statements, invoices, tax documents or other evidence of earnings.
8. Does living in Noida or Gurugram affect eligibility?
It may affect serviceability, address verification and available loan products. Check the lender's service area and documentation requirements.
9. How much loan can a gig worker get?
There is no universal loan amount. The lender may consider verified income, existing EMIs, credit history, requested tenure and repayment capacity.
10. How can I improve my chances of approval?
Maintain clear income records, check your credit report, provide consistent information, manage existing debt and request a realistic loan amount.
11. Are instant loan apps safe?
Not all apps are safe. Verify the lending institution, review the loan agreement and APR, check applicable RBI information and avoid apps or agents demanding suspicious advance payments.
12. Can I apply if my income changes every month?
Possibly. Some lenders may assess income over a period rather than relying on one month's earnings. Keep enough records to show your earnings pattern and budget for lower-income months.
13. What should I check before accepting a loan offer?
Review the APR, interest rate, processing fee, EMI, total repayment, late-payment charges, prepayment terms, privacy practices and the identity of the actual lender.
14. What should I do if my application is rejected?
Review the stated reason, correct document or credit-report errors where possible and reconsider the amount requested. Avoid repeated applications without understanding the issue.
15. Does Vizzve guarantee loan approval?
No borrower should assume approval is guaranteed. Eligibility, terms and disbursal depend on the actual lending provider's assessment and applicable conditions. Review Vizzve's current product information and lender details before applying.
Conclusion
Loan eligibility for gig workers in Delhi NCR depends on more than having a fixed monthly salary. Clear income records, a manageable debt burden, suitable documentation and careful lender selection can help workers understand their available options.
Whether you work as a delivery partner in Delhi, a driver in Gurugram or a freelancer in Noida, review the eligibility criteria and total loan cost before applying. Borrow only what you can comfortably repay, even when your weekly earnings fluctuate.
Vizzve readers should always verify current product terms and the identity of the actual lender before sharing personal information or accepting a loan offer.
Published on : 27th October
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed