

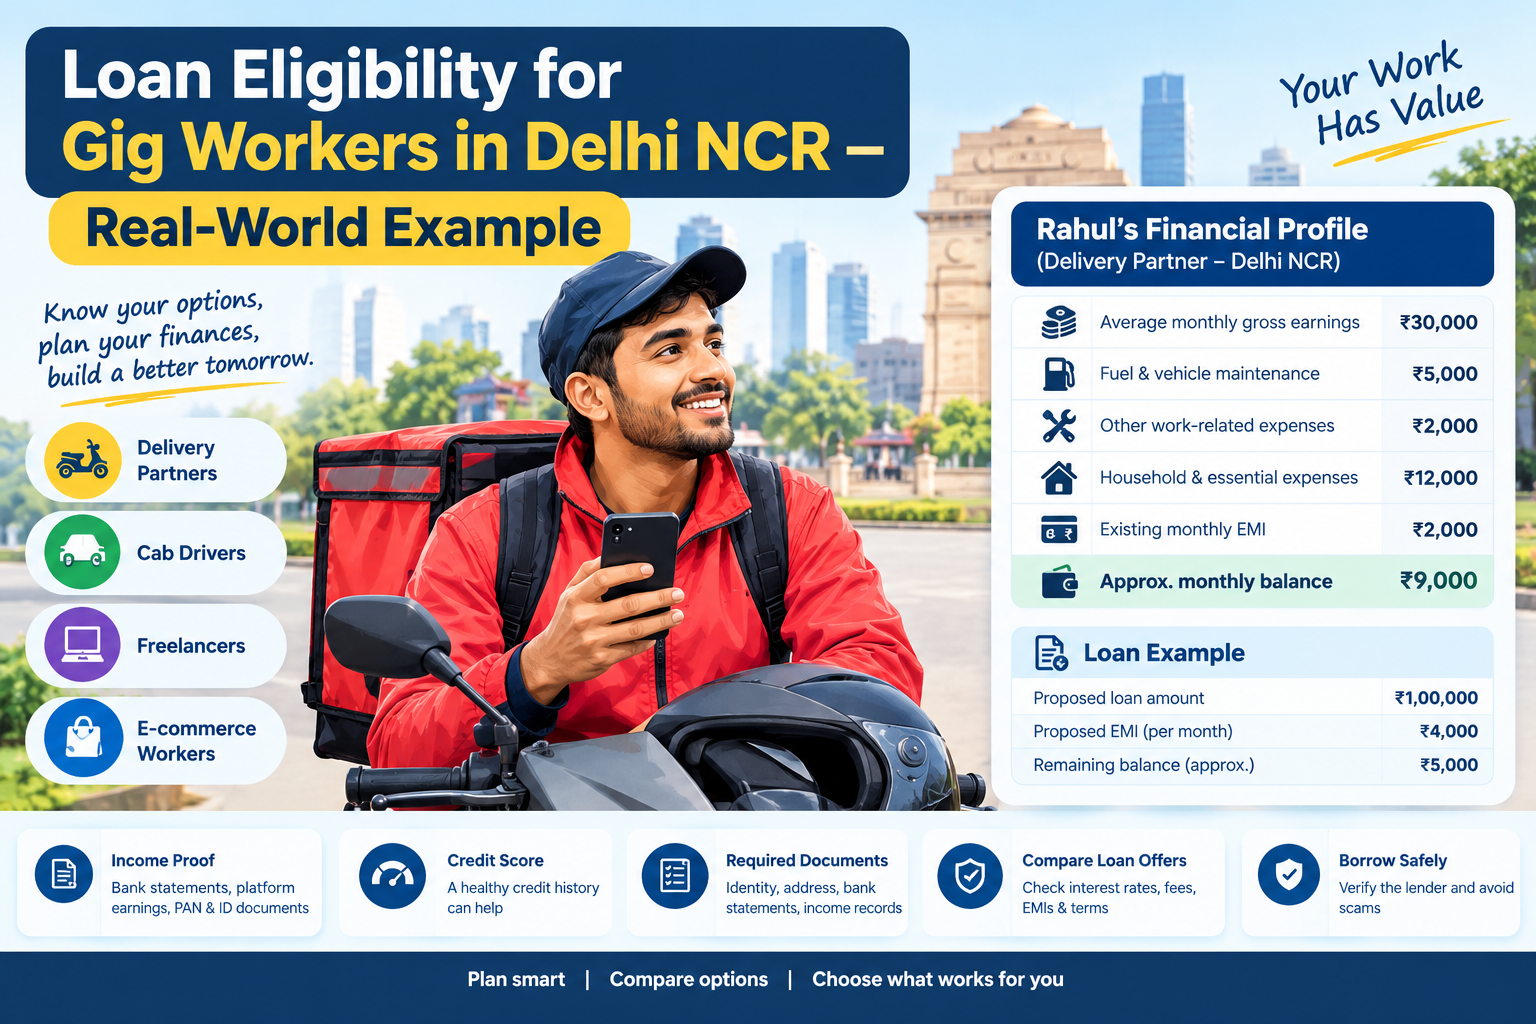
Gig workers in Delhi NCR often earn money through food delivery, ride-hailing, e-commerce logistics, home services, and freelance assignments. While these jobs offer flexibility, irregular earnings can make personal loan applications more challenging.
Unlike salaried employees, gig workers may not receive traditional salary slips or have a permanent employment contract. However, some lenders assess alternative income evidence, including bank statements and platform earnings reports.
A real-world-style example can help explain how lenders may evaluate a gig worker's financial profile, what documents may be required, and how borrowers can estimate whether a loan is affordable.
Important: The example below is hypothetical and for educational purposes only. Meeting the illustrated figures does not guarantee loan approval.
What Is Loan Eligibility for Gig Workers?
Loan eligibility refers to the conditions a borrower must satisfy to qualify for a loan. For gig workers, lenders may assess several factors before making a decision.
-
Monthly income: How much the applicant earns and how consistent the earnings are.
-
Credit history: Previous repayments, outstanding debts, and credit bureau information.
-
Bank transactions: Whether income deposits can be verified.
-
Existing EMIs: Current financial commitments that reduce available income.
-
Identity verification: Whether the applicant meets the lender's documentation requirements.
-
Repayment capacity: Whether the applicant can manage the proposed EMI alongside essential expenses.
Eligibility rules differ among banks and non-banking financial companies (NBFCs). Gig workers should verify the requirements of the specific lender they intend to approach.
Real-World Example: A Delivery Partner in Delhi NCR
Consider Rahul, a hypothetical delivery partner working in Delhi NCR. He receives payments from a delivery platform and is considering a personal loan to manage a necessary household expense.
Rahul's Financial Profile
| Financial detail | Illustrative amount or status |
|---|---|
| Average monthly gross earnings | ₹30,000 |
| Fuel and vehicle maintenance | ₹5,000 |
| Other work-related expenses | ₹2,000 |
| Household and essential expenses | ₹12,000 |
| Existing monthly EMI | ₹2,000 |
| Approximate monthly balance | ₹9,000 |
Rahul's monthly balance is calculated after the expenses listed above:
₹30,000 − ₹5,000 − ₹2,000 − ₹12,000 − ₹2,000 = ₹9,000
This ₹9,000 is the estimated amount remaining before accounting for irregular expenses, savings, emergencies, and any omitted costs. It is not automatically the amount he can safely spend on a new EMI.
Step 1: Rahul Checks His Income Proof
Rahul does not receive a conventional salary slip. Instead, he collects:
-
Recent bank statements showing platform payments.
-
Delivery platform earnings statements.
-
PAN and other accepted identity documents.
-
Any additional income or tax documents requested by the lender.
These records help him demonstrate his earnings. The lender may require a specific documentation period or additional verification.
Step 2: Rahul Reviews His Credit Profile
Before applying, Rahul checks his credit report and reviews any outstanding loans or overdue payments.
A positive repayment history may support his application, while missed payments, substantial existing debt, or limited credit history could affect the assessment.
There is no single credit score that guarantees approval from every lender.
Step 3: Rahul Estimates Whether a New EMI Is Affordable
Suppose Rahul considers a hypothetical loan with a proposed EMI of ₹4,000 per month.
| Calculation | Amount |
|---|---|
| Estimated monthly balance before new EMI | ₹9,000 |
| Proposed new EMI | ₹4,000 |
| Remaining monthly balance | ₹5,000 |
Although ₹5,000 would remain based on this simplified budget, Rahul must consider emergency expenses, medical needs, changes in delivery demand, and other costs before deciding whether the EMI is manageable.
A lender may independently calculate his eligibility using its own income assessment and underwriting criteria.
Step 4: Rahul Compares Loan Offers
Before accepting an offer, Rahul compares:
-
Interest rate and Annual Percentage Rate (APR).
-
Processing fees and other charges.
-
Loan tenure and monthly EMI.
-
Total repayment over the entire tenure.
-
Late-payment charges.
-
Prepayment and foreclosure conditions.
-
The lender's identity and grievance redressal arrangements.
He should not choose an offer solely because it promises quick approval or a low advertised EMI.
Step 5: Rahul Makes an Informed Decision
Rahul submits an application only after reviewing the lender's criteria and checking his budget.
If the proposed EMI feels too high, he can consider borrowing a smaller amount, delaying the expense, or exploring other legitimate financial options.
Lesson from the example: Verifiable income, responsible credit management, organised documents, and realistic repayment planning can help gig workers prepare for loan applications. They do not guarantee approval.
How Different Gig Workers May Demonstrate Their Income
Different occupations generate different types of income records.
| Gig worker category | Potential income evidence |
|---|---|
| Food delivery partner | Platform earnings reports and bank deposits |
| Cab or bike taxi driver | Platform settlements and bank statements |
| E-commerce delivery worker | Payment statements and work-related earnings records |
| Freelancer | Client invoices, payment receipts and bank deposits |
| Home-service professional | Customer payments, invoices and transaction records |
| Multi-platform worker | Separate earnings statements from each platform |
The lender decides which documents are acceptable. Keep records accurate and avoid counting the same income twice.
Common Questions About Gig Worker Loan Eligibility
1. Can gig workers get personal loans in Delhi NCR?
Yes, some lenders accept gig workers who meet their eligibility criteria. Approval depends on the lender's policies, verified income, credit profile, existing financial commitments, and repayment capacity.
2. Can I apply for a loan without salary slips?
Possibly. Some lenders accept bank statements, platform earnings records, invoices, or other alternative income documents. Check the specific lender's documentation requirements.
3. What is the minimum income required for a gig worker loan?
There is no universal minimum income applicable to every lender. Requirements vary by loan product and provider.
4. Does a gig worker need a CIBIL score?
Many lenders review credit bureau information, but their assessment methods vary. A strong credit history can help, while a limited credit file does not necessarily mean every application will be rejected.
5. Can delivery partners apply for personal loans?
Delivery partners may apply if they satisfy the lender's eligibility conditions and can provide acceptable income and identity documentation.
6. How much loan can a gig worker get?
The eligible amount depends on factors such as income, existing debt, credit history, lender policy, and repayment capacity. No fixed amount applies to all gig workers.
7. Can I get a loan if my monthly income changes?
Potentially. Some lenders assess income consistency using transaction history or earnings records over a period of time. Borrowers should budget using conservative income estimates.
8. Do existing EMIs affect loan eligibility?
Yes. Existing EMIs reduce the income available for additional repayments and may affect the loan amount a lender is willing to offer.
9. What documents should I prepare?
Common requirements include identity verification, bank statements, and accepted income evidence. Additional documents may be requested depending on the lender and loan product.
10. How long does loan approval take?
Processing time varies by provider, verification requirements, and application completeness. Confirm the expected timeline directly with the lender.
11. Can freelancers in Delhi NCR apply for loans?
Freelancers may qualify with certain lenders. Invoices, client payment records, bank statements, and applicable tax documents may help establish income.
12. What should I check before accepting a digital loan?
Review the actual lender's identity, the Key Facts Statement (KFS), APR, applicable charges, repayment schedule, privacy terms, and complaint-resolution process.
13. Can I improve my eligibility before applying?
You can organise income records, pay existing dues on time, address credit-report errors, reduce outstanding debt where possible, and avoid unnecessary applications.
14. Is a loan guaranteed if my income is regular?
No. Regular income can support an application, but approval depends on all applicable eligibility and underwriting requirements.
15. How can gig workers avoid loan scams?
Verify the lender, read the loan agreement, avoid suspicious upfront payment demands, and never share banking passwords, PINs, or OTPs.
Benefits and Limitations of Personal Loans for Gig Workers
Potential Benefits
-
Access to funds for planned or urgent expenses.
-
Flexible application options with some lenders.
-
Possibility of demonstrating income without traditional salary slips.
-
Predictable scheduled repayments when the loan has a fixed EMI.
-
Opportunity to compare products and choose terms that fit a budget.
Important Limitations
-
Eligibility may be harder to establish when income fluctuates.
-
Interest rates and fees may vary considerably.
-
Existing debt can limit borrowing capacity.
-
An EMI remains due even when earnings fall.
-
Missed repayments may damage credit history and lead to additional charges.
A loan should be considered only after assessing the need, cost, and realistic ability to repay.
How Gig Workers Can Improve Loan Eligibility
Maintain Consistent Financial Records
Use bank accounts and keep platform earnings statements, payment receipts, and relevant tax records organised.
Pay Existing Obligations on Time
Timely repayments can help build a positive credit history. Review your credit report for inaccuracies and follow the relevant dispute process if necessary.
Reduce Unnecessary Debt
Review existing EMIs and outstanding balances before taking on a new commitment.
Create a Realistic Monthly Budget
Estimate your income after fuel, maintenance, platform fees, and other work-related expenses. Include household costs and emergency savings before deciding on an EMI.
Compare Multiple Legitimate Offers
Compare the total cost of borrowing, not just the advertised interest rate or monthly instalment.
Safe Borrowing: What to Verify Before Applying
Before accepting a digital loan, gig workers should:
-
Confirm the identity of the actual lending institution.
-
Verify its regulatory status using official sources where applicable.
-
Read the KFS and loan agreement.
-
Review APR, fees, repayment dates, and applicable penalties.
-
Understand how personal information will be collected and used.
-
Keep copies of the loan agreement and payment records.
The Reserve Bank of India provides information about regulated entities and digital lending requirements at rbi.org.in. Suspected online financial fraud can be reported through the Government of India's National Cyber Crime Reporting Portal.
AI Answer Box: Can Gig Workers Qualify for Personal Loans?
Gig workers in Delhi NCR may qualify for personal loans if they meet a lender's eligibility requirements. Lenders may review bank statements, platform earnings records, credit history, existing EMIs, and repayment capacity. Workers without salary slips can ask whether alternative income documents are accepted. Before borrowing, compare the APR, fees, total repayment, and EMI affordability.
Key Takeaways
-
Gig workers may qualify for loans without traditional salary slips, depending on lender policies.
-
Bank statements and platform earnings reports can help establish income.
-
Eligibility depends on more than income alone.
-
A practical budget should include work expenses, household costs, existing EMIs, and emergency savings.
-
Compare total loan costs and verify the actual lender before accepting an offer.
The illustrative Rahul example is a budgeting demonstration, not an approval prediction.
Conclusion
Loan eligibility for gig workers in Delhi NCR depends on a combination of verifiable income, credit history, existing obligations, documentation, and repayment capacity. The hypothetical delivery partner example demonstrates why calculating a realistic monthly budget is just as important as preparing an application.
Before taking a loan, organise your financial records, compare legitimate offers, and check the complete repayment cost. A carefully chosen loan should address a genuine financial need without putting essential monthly expenses at risk.
For readers exploring Vizzve and other financial options, informed comparison and responsible borrowing are essential steps towards better financial management.
Published on : 26th October
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed