

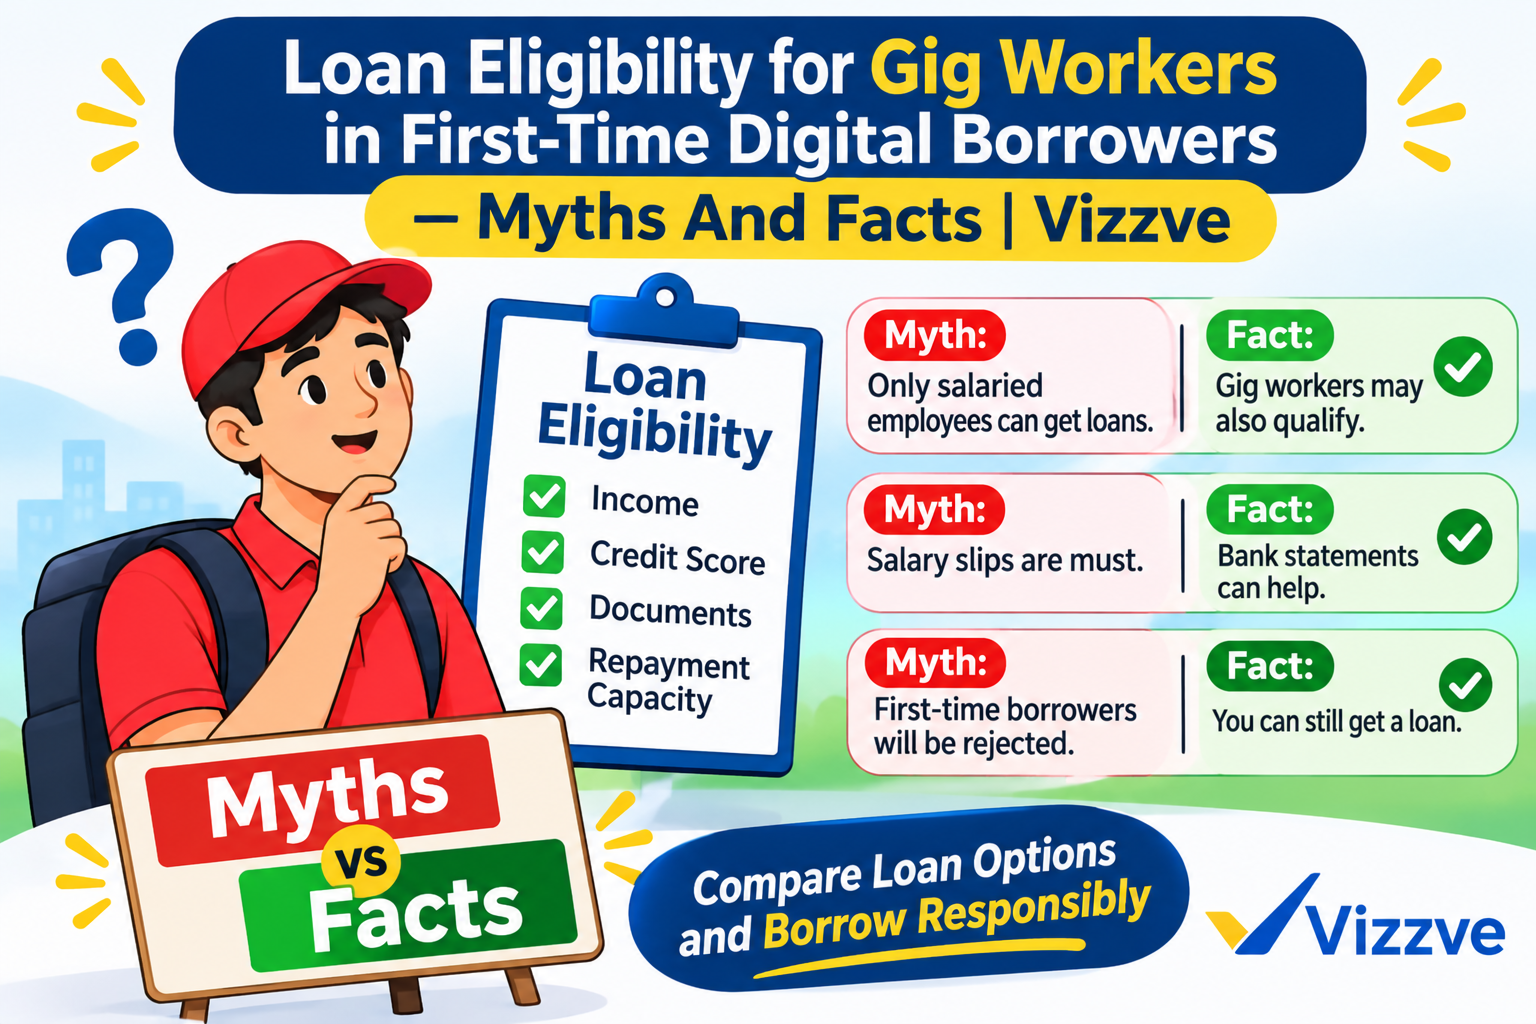
Getting a loan for the first time can be confusing for gig workers and digital borrowers. Many people believe that loans are available only to salaried employees or individuals with a fixed monthly income. However, this is not always true.
Gig workers such as delivery partners, cab drivers, freelancers, online service providers, and independent workers may also qualify for loans depending on the lender's eligibility requirements, income assessment, and credit profile.
With the growth of digital lending in India, borrowers have more ways to explore financial services. However, several myths about loan eligibility, credit scores, interest rates, and documentation can create confusion.
This guide explains the most common myths and facts about loan eligibility for gig workers and first-time digital borrowers, helping them make informed and responsible financial decisions.
1. Understanding Loan Eligibility for Gig Workers
Loan eligibility refers to the conditions a financial institution considers before approving a loan application.
For gig workers, lenders may evaluate different financial details because their earnings are not always fixed.
Common eligibility factors include:
-
Age and identity verification.
-
Average monthly income.
-
Bank account transaction history.
-
Gig platform earnings.
-
Credit score and repayment history.
-
Existing loans and financial obligations.
-
Employment or occupation details.
Important: Loan approval depends on the lender's assessment. Having a particular income or credit score does not guarantee approval.
2. Top Myths and Facts About Gig Worker Loan Eligibility
Myth 1: Only salaried employees can get personal loans.
Fact: Gig workers and self-employed individuals may also qualify for personal loans. Lenders may consider alternative income records, bank statements, and platform earnings.
Myth 2: Gig workers cannot apply without salary slips.
Fact: Salary slips are not the only way to demonstrate income. Depending on lender policy, bank statements, payment records, invoices, and gig platform earnings may be accepted.
Myth 3: First-time borrowers are automatically rejected.
Fact: First-time borrowers can apply for loans even if they have limited or no previous credit history. Lenders may assess their income, financial stability, and other available information.
Myth 4: A high income guarantees loan approval.
Fact: Income is only one part of the eligibility assessment. Existing debt, repayment capacity, credit history, and lender policies also matter.
Myth 5: Digital loans do not require documentation.
Fact: Digital applications may simplify document submission, but lenders still need to verify identity, income, and other relevant details.
Myth 6: A low credit score means you can never get a loan.
Fact: A low credit score can reduce approval chances or affect loan terms, but lenders may consider other financial information. Approval is subject to their policies.
Myth 7: All digital loans have very high interest rates.
Fact: Interest rates vary by lender, loan product, borrower profile, and repayment risk. Compare the Annual Percentage Rate (APR), not just the advertised interest rate.
Myth 8: Gig workers must have only one source of income.
Fact: Some lenders may consider income from multiple platforms or freelance activities when assessing repayment capacity.
Myth 9: Applying for multiple loans improves approval chances.
Fact: Multiple loan applications within a short period can result in several hard credit enquiries and may negatively affect a credit profile. Compare offers before applying.
Myth 10: Loan approval is guaranteed through digital applications.
Fact: Online applications do not guarantee approval. Every application is subject to the lender's verification and credit assessment.
3. Additional Myths and Facts First-Time Borrowers Should Know
|
Myth |
Fact |
|---|---|
|
Aadhaar alone guarantees a loan |
Lenders consider several eligibility factors |
|
Gig workers cannot build credit history |
Responsible credit use can help build credit history |
|
All lenders have the same eligibility rules |
Requirements differ between lenders |
|
A larger loan is always better |
Borrow according to repayment capacity |
|
EMI is the only cost to consider |
APR and applicable charges also matter |
|
Digital lending apps are all regulated lenders |
Verify the actual bank or NBFC behind the loan |
|
Missing one EMI has no consequences |
Delays may lead to charges and negative credit reporting |
|
Loan rejection means future rejection |
Future applications may be assessed differently |
4. Common Loan Eligibility Requirements for Gig Workers
Although requirements vary between lenders, gig workers may need to meet the following conditions:
A. Age Requirements
The applicant must satisfy the lender's minimum and maximum age requirements.
B. Income Requirements
The borrower may need to demonstrate sufficient and reasonably consistent earnings through platform payments, bank statements, or other accepted records.
C. Credit Profile
Lenders may examine credit history, outstanding debt, and previous repayment behaviour.
D. Identity Verification
Applicants generally need valid identity and address documentation according to lender requirements.
E. Repayment Capacity
The lender evaluates whether the applicant can manage the proposed EMI after accounting for regular expenses and existing obligations.
5. Documents That May Be Required
First-time digital borrowers should prepare the following documents:
-
Aadhaar card or other accepted identity proof.
-
PAN card.
-
Bank statements.
-
Gig platform income statements.
-
Freelance payment records or invoices, where applicable.
-
Address proof, if required.
-
Additional financial documents requested by the lender.
The exact documentation depends on the financial institution and loan product.
6. How First-Time Digital Borrowers Can Improve Loan Eligibility
First-time borrowers can take several practical steps to strengthen their financial profile.
Step 1: Maintain Regular Income Records
Keep bank statements, payment receipts, and platform earning reports. These records can help demonstrate your earning activity.
Step 2: Maintain a Healthy Credit Profile
Pay existing EMIs and credit card bills on time. Avoid unnecessary defaults and overdue balances.
Step 3: Reduce Existing Financial Obligations
Before applying, review your existing loans and monthly commitments.
Step 4: Use a Bank Account for Income Transactions
Receiving gig earnings through a bank account can help maintain clear financial records.
Step 5: Provide Accurate Information
Submit genuine personal, banking, and income details. Incorrect information can delay your application.
Step 6: Choose an Affordable Loan Amount
Do not borrow more than you need. Select an EMI that remains manageable even when your monthly earnings fluctuate.
7. Why Loan Eligibility Can Be Different for Gig Workers
Traditional salaried employees generally receive regular salary payments, whereas gig workers may earn different amounts each month.
For example:
-
Delivery partners earn based on completed orders and incentives.
-
Cab drivers earn based on rides and working hours.
-
Freelancers receive payments based on completed projects.
-
Independent service providers may have multiple clients.
Because of these differences, lenders may use different methods to assess income and repayment capacity.
|
Financial factor |
Salaried employees |
Gig workers |
|---|---|---|
|
Income source |
Monthly salary |
Platform or freelance earnings |
|
Income pattern |
Often fixed |
May fluctuate |
|
Income proof |
Salary slips |
Bank statements and earnings records |
|
Employment proof |
Employer documents |
Platform or work records |
|
Credit assessment |
Credit and income |
Credit and income |
|
Repayment capacity |
Monthly income and expenses |
Average income and expenses |
Gig workers should maintain clear financial records to make their income easier to assess.
8. Myths About Digital Lending and Borrower Safety
Digital lending can make loan applications convenient, but borrowers should understand the risks and regulations.
Myth 1: Every loan application on a mobile app is safe.
Fact: Always verify the actual regulated lender and its association with the digital lending application.
Myth 2: Borrowers do not need to read loan agreements.
Fact: Read the loan agreement and Key Facts Statement (KFS) before accepting a loan.
Myth 3: Digital lenders can charge any fee without disclosure.
Fact: Applicable charges must be disclosed according to regulatory requirements. Review the KFS carefully.
Myth 4: Borrowers have no rights after accepting a digital loan.
Fact: RBI-regulated digital lending requirements provide borrower protections, including applicable cooling-off and grievance redressal arrangements.
Myth 5: Sharing OTPs helps speed up loan approval.
Fact: Never share OTPs, PINs, passwords, or confidential banking credentials with unknown people.
9. RBI Guidelines Every First-Time Digital Borrower Should Know
The Reserve Bank of India introduced the Digital Lending Directions, 2025 to strengthen transparency and borrower protection in digital lending.
Important provisions include:
-
Creditworthiness assessment: Regulated lenders must assess relevant borrower information, including age, occupation, and income.
-
Key Facts Statement: Borrowers should receive important loan information through the KFS.
-
APR disclosure: The annualised cost of borrowing must be disclosed.
-
Cooling-off period: Borrowers must receive an applicable option to exit a digital loan during the initial cooling-off period by paying the principal and proportionate APR without penalty, subject to the permitted disclosed processing fee.
-
Grievance redressal: Regulated lenders and relevant lending service providers must provide grievance redressal arrangements.
-
Data privacy: Borrower information must be handled according to applicable data collection, consent, and privacy requirements.
These guidelines help borrowers understand their loan terms and make informed decisions.
Official reference: RBI Digital Lending Directions, 2025.
10. Practical Checklist Before Applying for a Loan
Use this checklist before submitting your loan application.
11. How Vizzve Helps Gig Workers Understand Loan Eligibility
Vizzve aims to provide useful financial information to gig workers and first-time digital borrowers.
Understanding loan eligibility can help borrowers prepare better before applying for financial assistance.
Vizzve-related educational resources can help readers learn about:
-
Loan eligibility requirements.
-
Income documentation.
-
Credit scores and credit history.
-
Digital lending processes.
-
EMI and repayment planning.
-
Loan comparison and financial safety.
-
Responsible borrowing practices.
Before applying, borrowers should always verify the lender, understand the loan terms, and evaluate their repayment capacity.
12. Key Takeaways
-
Gig workers may qualify for loans even without traditional salary slips.
-
First-time borrowers are not automatically rejected.
-
Lenders may consider bank statements and gig platform earnings.
-
A high income does not guarantee loan approval.
-
Credit history and repayment capacity are important eligibility factors.
-
Digital loan applications still require appropriate verification.
-
Borrowers should compare APR, interest rates, and additional charges.
-
RBI digital lending guidelines provide important borrower protections.
-
Responsible borrowing helps maintain long-term financial stability.
13. Frequently Asked Questions (FAQs)
1. Can gig workers get loans in India?
Yes. Gig workers can apply for loans if they meet the lender's income, identity, credit assessment, and other eligibility requirements.
2. Can first-time digital borrowers get loans without a credit history?
Yes. Some lenders may consider first-time borrowers with limited credit history by evaluating income, bank transactions, and other financial information.
3. Are salary slips compulsory for gig workers?
No. Depending on lender policy, bank statements, platform earnings, invoices, and other income records may be accepted.
4. Does a low credit score mean loan rejection?
Not necessarily. A low credit score may affect eligibility and loan terms, but some lenders may consider other financial factors.
5. Can delivery partners apply for personal loans?
Yes. Delivery partners can apply if they meet the lender's eligibility and documentation requirements.
6. Can freelancers and gig workers apply for digital loans?
Yes. Eligible freelancers and gig workers may apply through regulated lenders offering suitable credit products.
7. Is loan approval guaranteed for first-time borrowers?
No. Every application is subject to the lender's verification, credit assessment, and approval policies.
8. Can gig workers use bank statements as income proof?
Some lenders accept bank statements to assess income patterns and financial activity.
9. Does having multiple income sources improve loan eligibility?
Multiple income sources may help demonstrate earning capacity, depending on how the lender evaluates income stability.
10. Can applying for multiple loans affect my credit score?
Multiple hard credit enquiries within a short period may affect your credit profile. Research and compare offers before submitting applications.
11. What is the minimum income required for a gig worker loan?
There is no universal minimum income. Requirements vary according to the lender, loan product, and applicant profile.
12. Are digital loans safe for first-time borrowers?
They can be safe when offered by regulated lenders through legitimate digital lending arrangements. Always verify the lender and read the loan terms.
13. What is a Key Facts Statement (KFS)?
A KFS is a document that provides important loan details, including APR, charges, and repayment information.
14. How can gig workers improve their loan eligibility?
They can maintain income records, pay existing debts on time, reduce financial obligations, and provide accurate application details.
15. Can gig workers get loans with irregular monthly income?
Some lenders may consider average earnings and other financial records instead of requiring an identical monthly income. Approval depends on lender policy.
14. Conclusion
There are many misconceptions about loan eligibility for gig workers and first-time digital borrowers. The reality is that salaried employment is not the only possible route to loan eligibility.
Gig workers, freelancers, delivery partners, and independent service providers may qualify for financial products depending on their income records, credit history, repayment capacity, and lender requirements.
Understanding the difference between myths and facts helps borrowers avoid confusion and make better financial decisions.
Vizzve encourages gig workers and first-time digital borrowers to stay informed, compare loan options, and choose responsible borrowing practices.
Published on : 11th November
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed