

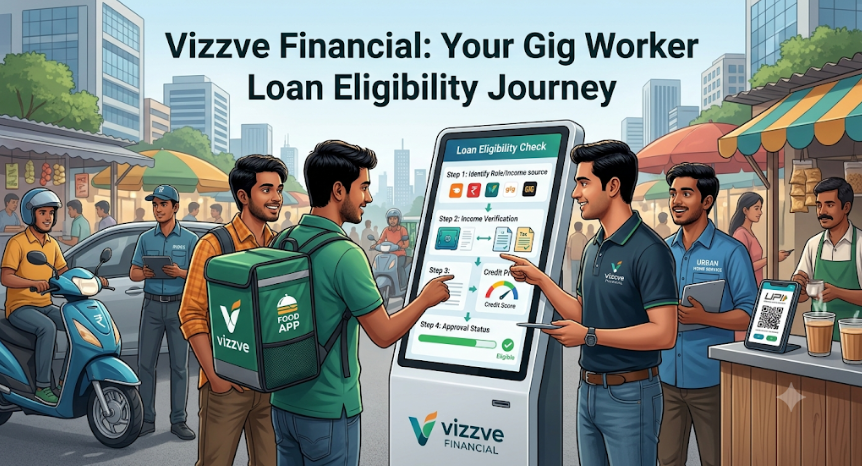
Introduction
Getting a personal loan can seem confusing, especially when you are a gig worker or applying for your first digital loan.
Today, many Indians earn through delivery services, bike taxis, cab platforms, freelancing, online businesses and independent work. Unlike traditional salaried employees, these individuals may not receive monthly salary slips or fixed income.
This often creates questions such as:
-
Can delivery partners apply for personal loans?
-
How can freelancers prove their monthly income?
-
Can someone without previous loan history get approved?
-
What documents are required for a digital loan?
-
How can gig workers check their loan eligibility?
The good news is that gig workers and first-time digital borrowers may qualify for personal loans through lenders that accept their occupation and income profile.
However, approval is not automatic. Lenders assess income consistency, repayment capacity, credit history, existing financial obligations and KYC details.
This step-by-step guide explains how to check your eligibility, prepare the required documents and complete a personal loan application confidently.
3. AI Answer Box – Quick Explanation
How can gig workers check personal loan eligibility?
Gig workers can check personal loan eligibility by reviewing the lender's age and income requirements, calculating their average monthly earnings, checking existing EMIs and preparing valid income documents.
The basic process involves:
-
Checking the lender's eligibility criteria.
-
Calculating average monthly income.
-
Reviewing credit history.
-
Preparing bank statements and earning records.
-
Choosing an affordable loan amount.
-
Completing the online application.
-
Submitting KYC and income documents.
-
Reviewing the loan offer before accepting.
First-time digital borrowers can also apply without previous loan experience. The lender may assess other available financial information to determine repayment capacity.
4. Understanding Loan Eligibility for Gig Workers
Before starting the application, it is important to understand what loan eligibility means.
Loan eligibility refers to the financial and personal conditions an applicant must satisfy before a lender considers providing credit.
For gig workers, eligibility assessment may be slightly different because income is not always fixed.
Who Can Apply for a Gig Worker Personal Loan?
The following professionals may be eligible, depending on the lender's policy:
-
Food delivery partners.
-
Bike taxi drivers.
-
Cab drivers.
-
E-commerce delivery executives.
-
Freelancers.
-
Independent digital marketing professionals.
-
Online service providers.
-
Self-employed professionals.
-
Part-time platform workers.
Common Eligibility Requirements
|
Eligibility Factor |
What Lenders May Check |
|---|---|
|
Age |
Minimum and maximum age requirements |
|
Income |
Average monthly earnings |
|
Occupation |
Nature of gig or freelance work |
|
Bank account |
Transaction history |
|
Credit profile |
Existing credit history, if available |
|
Existing EMIs |
Current repayment commitments |
|
KYC |
Identity and address verification |
There is no universal income threshold or age requirement for every gig worker loan. Always check the actual lender's conditions.
5. Step-by-Step Guide to Check Loan Eligibility for Gig Workers
Here is a practical process that first-time digital borrowers can follow before applying.
Step 1: Identify Your Employment Category
Identify whether you work as a delivery partner, freelancer, cab driver or independent professional.
This helps you find lenders that accept your type of employment.
Step 2: Calculate Your Average Monthly Income
Add your earnings over the previous six months and divide by six.
This provides a useful estimate of your average income.
Step 3: Check Your Credit Profile
Review your credit report to understand previous borrowing, outstanding balances and repayment history.
If you are a first-time borrower, you may have a limited credit history.
Step 4: Prepare Your Income Documents
Collect bank statements, platform payout records, invoices and other documents that support your earnings.
Step 5: Calculate Your Repayment Capacity
Consider your household expenses, existing EMIs and emergency savings before selecting a loan amount.
Step 6: Compare Different Lenders
Compare interest rates, APR, processing charges, repayment periods and eligibility requirements.
6. How to Calculate Average Monthly Income as a Gig Worker
Income verification is an important part of a personal loan application.
Unlike salaried employees, gig workers may receive different payments every week or month.
A practical approach is to calculate average earnings over several months.
Example: Monthly Income Calculation
Suppose a delivery partner earns the following amounts:
|
Month |
Income |
|---|---|
|
January |
₹21,000 |
|
February |
₹24,000 |
|
March |
₹22,000 |
|
April |
₹26,000 |
|
May |
₹23,000 |
|
June |
₹25,000 |
|
Total |
₹1,41,000 |
Average monthly income:
This calculation can help the applicant understand their earnings. The lender may use a different calculation and consider income after expenses or other adjustments.
Why Is Income Consistency Important?
Lenders want to understand whether applicants can repay their loans.
For example:
-
Regular income deposits can help demonstrate earnings.
-
Bank statements can show payment patterns.
-
Platform statements can support income verification.
-
Multiple months of records can provide a broader financial picture.
Expert commentary: Gig workers should avoid relying only on their best-earning month when planning a loan. A realistic average gives a better understanding of what EMI they can manage.
7. Documents Required for First-Time Digital Borrowers
First-time digital borrowers should prepare the necessary documents before beginning their application.
Essential Documents Checklist
|
Document |
Purpose |
|---|---|
|
Aadhaar Card |
KYC verification, where applicable |
|
PAN Card |
Financial identity verification |
|
Bank Statements |
Income and transaction assessment |
|
Platform Earnings Statement |
Proof of gig earnings |
|
Freelance Invoices |
Evidence of professional income |
|
Address Proof |
Address verification, if required |
|
Photograph |
Applicant verification, if required |
Can You Apply Without a Salary Slip?
Yes. Some lenders accept alternative income documents.
Examples include:
-
Delivery platform payout statements.
-
Cab service earning records.
-
Bank transaction history.
-
Freelance invoices.
-
Digital payment receipts.
-
Income tax returns, where applicable.
However, document requirements vary between lenders. Alternative income proof does not guarantee approval.
8. How Can First-Time Digital Borrowers Apply for a Personal Loan Online?
Once you understand your eligibility and have prepared the required documents, you can proceed with the online application.
Online Loan Application Process
Step 1: Visit the Lender's Official Website
Choose a legitimate bank, NBFC or lending platform and verify the regulated lender associated with the loan.
Step 2: Select the Personal Loan Option
Review the available personal loan product and its eligibility requirements.
Step 3: Enter Your Personal Information
Provide the requested details, such as:
-
Full name.
-
Date of birth.
-
Mobile number.
-
Residential address.
-
Employment category.
Step 4: Enter Your Income Details
Mention your average monthly income accurately.
Do not inflate earnings to improve your chances of approval.
Step 5: Complete KYC Verification
Submit the required identity information through the lender's approved verification method.
Step 6: Upload Supporting Documents
Provide bank statements, earning records and any other requested documents.
Step 7: Wait for Application Assessment
The lender may verify your information and assess your repayment capacity.
Step 8: Review the Loan Offer
If the application is approved, carefully review the loan amount, interest rate, APR, processing charges, EMI and repayment terms.
Step 9: Accept the Agreement
Proceed only after understanding the loan agreement and accepting its conditions.
Step 10: Receive the Loan Disbursement
The regulated lender processes disbursement according to its procedures and applicable requirements.
9. How to Calculate Personal Loan Affordability
Getting an approval offer does not necessarily mean that the loan is affordable.
Before applying, understand how much of your monthly income is already committed to existing expenses and repayments.
Example of EMI Affordability
Consider a gig worker with the following financial details:
|
Particulars |
Amount |
|---|---|
|
Average monthly income |
₹30,000 |
|
Household expenses |
₹15,000 |
|
Existing loan EMI |
₹3,000 |
|
Remaining amount |
₹12,000 |
The remaining ₹12,000 is not automatically available for a new EMI. The borrower should also consider savings, emergencies and fluctuations in income.
Simple EMI Formula
Where:
-
P = Principal loan amount.
-
R = Monthly interest rate.
-
N = Number of monthly instalments.
Illustrative Loan EMI Comparison
Assume a ₹50,000 personal loan at 18% annual nominal interest on a reducing balance.
|
Tenure |
Approximate EMI |
Approximate Total Interest |
|---|---|---|
|
6 months |
₹8,784 |
₹2,704 |
|
12 months |
₹4,584 |
₹5,008 |
|
18 months |
₹3,193 |
₹7,474 |
|
24 months |
₹2,496 |
₹9,904 |
Illustrative figures, rounded to the nearest rupee. Fees and other charges are excluded. Actual loan terms may differ.
Expert tip: A longer tenure can reduce monthly EMI, but it usually increases the total interest paid. Choose a tenure based on affordability rather than just a lower EMI.
10. First-Time Borrowers vs Experienced Borrowers
Understanding the difference can help new applicants prepare their applications.
|
Factor |
First-Time Borrower |
Experienced Borrower |
|---|---|---|
|
Previous loans |
Usually none |
May have previous loans |
|
Credit history |
May be unavailable |
May be established |
|
Repayment record |
Not available |
Can be assessed |
|
Income documents |
Required |
Required |
|
Eligibility assessment |
Based on available information |
Based on available information |
|
Approval |
Not guaranteed |
Not guaranteed |
Does Having No Credit Score Mean Loan Rejection?
No. A person with no established credit history is different from someone with a poor repayment history.
Some lenders may consider alternative information, such as income consistency, banking transactions and other permitted financial details.
11. Pros and Cons of Digital Personal Loans for Gig Workers
|
Pros |
Cons |
|---|---|
|
Convenient online application |
Approval is not guaranteed |
|
Less dependence on physical paperwork in some processes |
Verification may take additional time |
|
Alternative income documents may be accepted |
Income fluctuations can affect assessment |
|
Can help manage planned expenses |
Interest and fees increase borrowing costs |
|
Responsible repayment can build credit history |
Missed payments may harm credit history |
When Should Gig Workers Consider a Personal Loan?
A personal loan may be worth considering for a genuine and necessary expense when the borrower has a realistic repayment plan.
Examples include:
-
Emergency medical expenses.
-
Essential vehicle repairs.
-
Education expenses.
-
Necessary household requirements.
-
Work-related equipment purchases.
Avoid borrowing for unnecessary purchases or taking another loan simply to pay existing EMIs without a sustainable repayment plan.
12. Common Mistakes to Avoid During the Loan Application
First-time borrowers sometimes make mistakes that can affect their application or financial well-being.
|
Common Mistake |
Better Approach |
|---|---|
|
Reporting incorrect income |
Provide accurate earnings |
|
Uploading incomplete documents |
Check document requirements |
|
Ignoring existing EMIs |
Calculate total debt obligations |
|
Applying to many lenders at once |
Compare eligibility before applying |
|
Choosing the highest loan amount |
Borrow only what is required |
|
Ignoring processing charges |
Review APR and KFS |
|
Using unverified loan apps |
Verify the regulated lender |
|
Missing repayment dates |
Maintain a repayment reminder |
13. RBI Digital Lending Rules: What First-Time Borrowers Should Know in 2026
The Reserve Bank of India introduced the Reserve Bank of India (Digital Lending) Directions, 2025, to strengthen transparency and borrower protection in digital lending.
The framework includes important requirements for regulated lenders.
Important Borrower Protections
1. Creditworthiness Assessment
Lenders must collect relevant economic information, including age, occupation and income details, to assess creditworthiness.
2. Key Fact Statement (KFS)
Borrowers should receive a KFS explaining important loan terms and costs before accepting the loan.
3. APR Disclosure
The Annual Percentage Rate helps borrowers understand the all-inclusive annualised cost of credit.
4. Data Privacy
Digital lenders must follow applicable consent and data protection requirements.
5. Transparent Loan Documentation
Relevant loan documents, including the KFS and sanction-related documents, must be provided to borrowers as required.
6. Digital Lending App Verification
The RBI's public Digital Lending Apps directory helps customers check claims about an app's association with regulated entities. The directory is intended as a verification aid and should be considered alongside other lender checks.
For additional information, visit the RBI official website.
How Can You Protect Yourself From Fake Loan Apps?
-
Verify the actual lender.
-
Check the app's association with a regulated entity.
-
Never share OTPs or banking passwords.
-
Avoid suspicious upfront payment requests.
-
Read the privacy policy.
-
Review the loan agreement.
-
Save all payment receipts.
-
Use official complaint channels if necessary.
14. Latest Gig Economy Developments in India
India's gig economy is becoming increasingly important to employment and financial inclusion.
NITI Aayog's report on India's gig and platform economy estimated that the workforce could grow from 7.7 million in 2020–21 to 23.5 million by 2029–30. These are estimates and projections, not a current headcount.
The Government has also introduced social security provisions for gig and platform workers under the Code on Social Security, 2020. The Ministry of Labour and Employment published further information about these provisions in 2025.
Why Does This Matter for Loan Applicants?
-
Gig work is becoming a more visible employment category.
-
Digital payment records can help document earnings.
-
Financial inclusion remains an important policy objective.
-
Workers should maintain reliable income records.
-
Formal recognition of gig work does not guarantee credit approval.
The e-Shram portal provides information about registration and relevant worker welfare initiatives.
15. Practical Example: A Delivery Partner Applying for a First Personal Loan
Let's understand the process through a simple real-world-style example.
Meet Arun, a food delivery partner who earns through a digital delivery platform.
He wants to apply for a ₹40,000 personal loan to cover an unexpected expense.
Arun's Financial Profile
|
Particulars |
Details |
|---|---|
|
Occupation |
Food Delivery Partner |
|
Average Monthly Income |
₹25,000 |
|
Existing EMI |
₹2,000 |
|
Previous Loan History |
None |
|
Requested Loan Amount |
₹40,000 |
|
Bank Statements |
Available |
|
Platform Earnings Records |
Available |
What Should Arun Do?
-
Calculate his average monthly income.
-
Collect six months of bank statements, if available and requested.
-
Download his platform earning statements.
-
Check his credit report, if one exists.
-
Calculate an affordable EMI.
-
Compare lenders that accept gig workers.
-
Complete KYC verification.
-
Review the loan offer before accepting.
Since Arun has no previous borrowing history, the lender may assess other available financial information.
Important: This is an illustrative example. His application may be approved or rejected depending on the lender's assessment.
16. How Can Gig Workers Improve Their Loan Eligibility?
Building a strong financial profile takes time. These habits can help applicants become better prepared for future credit requirements.
Maintain Regular Bank Transactions
Receive your work payments through a bank account wherever possible. Keep your transaction history organised.
Track Monthly Earnings
Maintain a simple record of weekly and monthly income.
Reduce Existing Debt
Avoid unnecessary borrowing and manage existing EMIs responsibly.
Check Your Credit Report
Review your credit information periodically and report genuine errors through the appropriate channels.
Choose a Realistic Loan Amount
Do not borrow more simply because a lender offers a higher amount.
Maintain an Emergency Fund
Set aside savings to manage periods when gig earnings are lower than expected.
Avoid Multiple Loan Applications
Compare lender requirements first. Multiple formal credit enquiries within a short period may affect your credit profile.
17. Benefits of Checking Loan Eligibility Before Applying
Checking eligibility before submitting an application can help borrowers make better financial decisions.
|
Benefit |
Explanation |
|---|---|
|
Better preparation |
Understand the requirements beforehand |
|
Document readiness |
Collect the necessary records |
|
Financial planning |
Calculate affordable EMIs |
|
Informed decisions |
Compare available loan terms |
|
Reduced unnecessary applications |
Avoid applying without understanding lender criteria |
|
Better borrowing habits |
Understand total repayment obligations |
An eligibility check is useful, but it does not guarantee final approval.
18. Frequently Asked Questions (FAQs)
1. How can gig workers check personal loan eligibility?
Gig workers can check eligibility by reviewing lender requirements, calculating average income, checking credit history, preparing bank statements and reviewing existing EMI commitments.
2. Can first-time digital borrowers apply for personal loans?
Yes. First-time digital borrowers may apply even without previous loan experience. Approval depends on lender-specific eligibility requirements.
3. Can delivery partners get personal loans without salary slips?
Some lenders accept alternative income documents, such as bank statements, delivery platform earning reports and payment records.
4. What is the minimum income required for gig worker loans?
There is no universal minimum income requirement. Each lender establishes its own income and eligibility criteria.
5. Is a credit score mandatory for first-time borrowers?
Not necessarily. Some lenders may consider other financial information when an applicant has no established credit history.
6. How many months of bank statements are required?
The requirement varies by lender. Some may request three or six months of statements, while others may have different verification requirements.
7. Can freelancers apply for personal loans online?
Yes. Freelancers may apply through lenders that accept self-employed or freelance income profiles.
8. Does irregular income reduce loan eligibility?
It may affect eligibility because lenders consider income consistency and repayment capacity. Maintaining clear earning records can help demonstrate financial activity.
9. Can bike taxi drivers apply for personal loans?
Yes. Bike taxi drivers may apply if their occupation and income documentation meet the lender's requirements.
10. What documents are needed for a first personal loan?
Common documents include PAN, identity verification details, bank statements, address proof where required and supporting income records.
11. Does having no previous loan history mean rejection?
No. A lack of credit history does not automatically result in rejection. Lenders may assess other available financial information.
12. How can gig workers prove monthly income?
They may use platform payout statements, bank credits, digital payment records, freelance invoices and other acceptable financial documents.
13. Can e-Shram registration guarantee a personal loan?
No. e-Shram registration does not guarantee loan approval. Lending decisions are based on the lender's eligibility and repayment assessment.
14. Is applying for a digital personal loan safe?
It can be safe when using a legitimate lending arrangement with an RBI-regulated entity. Always verify the lender and review the KFS and loan agreement.
15. How long does personal loan approval take?
Processing time depends on the lender, document verification, eligibility assessment and application details. There is no guaranteed approval timeline.
19. Key Takeaways
-
Gig workers can apply for personal loans through lenders that accept their occupation.
-
First-time digital borrowers can apply without previous loan experience.
-
Average monthly income is useful for understanding repayment capacity.
-
Salary slips are not the only acceptable income evidence.
-
Bank statements and platform payout records can support income verification.
-
Credit history and existing EMI commitments may influence approval.
-
Comparing APR, processing fees and repayment tenure is important.
-
RBI Digital Lending Directions, 2025, provide important borrower safeguards.
-
e-Shram registration does not guarantee loan approval.
-
Responsible borrowing helps maintain long-term financial stability.
20. Vizzve Financial – Explore Personal Loan Options
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Whether you are a delivery partner, freelancer, cab driver or first-time digital borrower, understanding your eligibility is an important first step.
Explore available loan options through Vizzve Financial and review the applicable requirements before applying.
Loan eligibility, documentation, interest rates and approval are subject to the applicable lender's policies and verification. Approval is not guaranteed.
21. Conclusion
Applying for a personal loan as a gig worker or first-time digital borrower does not have to be complicated.
The most important step is understanding your financial position before submitting an application.
By calculating average monthly earnings, maintaining bank records, preparing alternative income documents and reviewing your credit profile, you can make the application process more organised.
Remember that loan approval is not based on income alone. Lenders also consider repayment capacity, existing financial obligations, credit information and their own eligibility policies.
Take time to compare available options, understand the total borrowing cost and select an EMI that fits your income.
Ready to explore personal loan options? Visit Vizzve Financial at www.vizzve.com.
Published on : 4 th November
Published by : Reddy kumar
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed