

The way people earn money is changing. Alongside traditional salaried employment, many people now work as delivery partners, drivers, freelancers, online service providers, logistics workers and independent professionals.
For these workers, income may come from multiple assignments, platforms or customers rather than a fixed monthly salary.
This can make borrowing different from the traditional salaried-loan process.
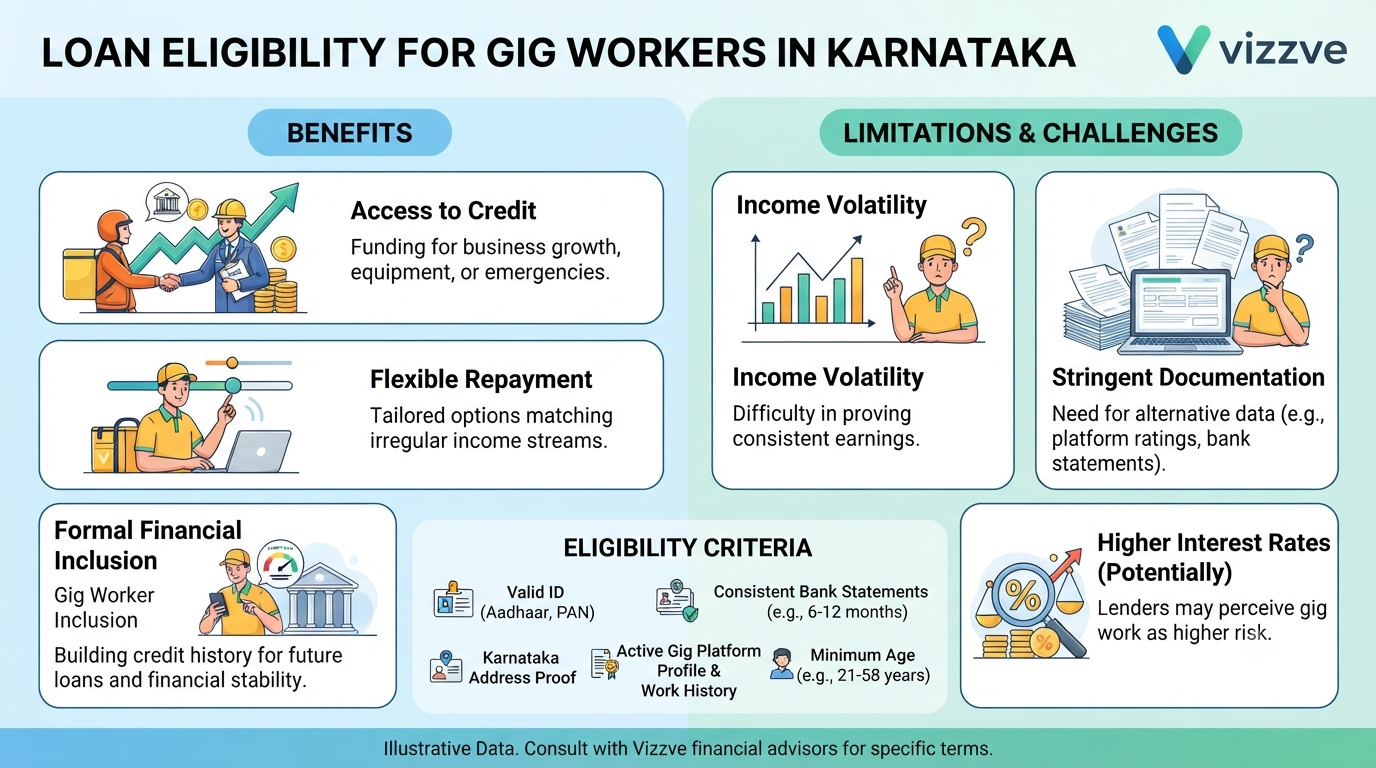
Loan eligibility for gig workers in Karnataka can depend on factors such as income records, bank transactions, credit history, existing financial obligations and the lender's own eligibility criteria.
A loan may provide useful access to funds, but it also creates a repayment obligation. Therefore, gig workers should understand both the benefits and limitations before applying.
This guide explains the topic in simple terms and provides a practical checklist for gig workers in Karnataka.
AI Answer Box: What Are the Benefits and Limitations of Gig Worker Loans?
Loans can provide gig workers with access to funds for planned or unexpected expenses. Depending on the lender and applicant profile, digital application processes may also make it easier to submit documents and receive loan-related information.
However, gig workers can face limitations because their income may fluctuate and they may not have conventional salary slips.
Key benefits
- Access to funds for eligible financial needs
- Digital application options
- Alternative income documentation may be accepted by some lenders
- Potentially convenient application process
- Different repayment tenures may be available
- Loan applications can help build formal credit history when repayments are reported and made on time
Key limitations
- Income may be irregular
- Salary slips may not be available
- Lenders may require additional income verification
- Existing EMIs can reduce borrowing capacity
- Interest and other charges increase the total repayment amount
- Approval is not guaranteed
- Digital lending requires careful verification of the actual lender
Eligibility, interest rates, loan amounts and documentation vary by lender.
Who Is a Gig Worker?
A gig worker generally earns income by completing individual tasks, assignments or projects rather than receiving a traditional fixed salary.
Examples include:
- Food delivery partners
- Grocery delivery partners
- Cab and bike-taxi drivers
- Courier and logistics workers
- Freelancers
- Online professionals
- Home-service providers
- Independent contractors
- Part-time platform workers
A gig worker may receive income daily, weekly, monthly or according to completed assignments.
This income pattern is one of the important factors a lender may consider when assessing repayment capacity.
Understanding Loan Eligibility for Gig Workers in Karnataka
There is no single universal eligibility rule that applies to every gig worker.
A lender may consider several factors, including:
| Eligibility factor | What the lender may consider |
|---|---|
| Age | Whether the applicant falls within the lender's permitted age range |
| Income | Amount and consistency of earnings |
| Occupation | Type and duration of gig work |
| Bank transactions | Regularity of income credits |
| Credit history | Previous repayment behaviour |
| Existing debt | Current loans and EMIs |
| Documents | KYC and income-related records |
| Loan amount | Whether requested amount fits repayment capacity |
| Tenure | Ability to manage the proposed repayment schedule |
For digital lending by RBI-regulated entities, the RBI's Digital Lending Directions, 2025 require regulated entities to obtain information about a borrower's economic profile for creditworthiness assessment, including age, occupation and income details.
Benefits of Loans for Gig Workers in Karnataka
1. Access to Formal Credit
A personal loan can provide access to formal credit for eligible borrowers.
Instead of relying on informal borrowing, a borrower can evaluate formal loan terms such as:
- Loan amount
- Interest rate
- APR
- EMI
- Tenure
- Processing charges
- Repayment schedule
The actual availability and terms depend on the lender.
2. Digital Application Convenience
Many loan applications can be completed digitally.
For gig workers who spend much of their working day on the road, an online application can be more convenient than repeatedly visiting a branch.
Depending on the lender, the process may involve:
- Online application
- KYC verification
- Income assessment
- Credit assessment
- Loan offer
- Agreement and KFS review
- Disbursement
Digital convenience does not remove the need to understand the loan terms.
3. Alternative Income Records May Be Useful
Traditional salaried applicants may provide salary slips and employer documents.
Gig workers may instead have records such as:
- Bank statements
- Platform earnings statements
- Invoices
- Receipts
- Income tax records
- Other accepted financial documents
Whether a particular document is accepted depends on the lender.
4. Flexible Loan Amounts and Tenures May Be Available
Depending on the lender and product, borrowers may be offered different loan amounts and repayment periods.
A borrower should not automatically select the maximum amount available.
Instead, consider:
Required amount → Monthly affordability → Total repayment → Loan tenure
The smallest EMI is not necessarily the lowest-cost option.
5. Can Help Establish a Credit History
When a loan is reported to credit information companies and repayments are made as agreed, the account can become part of the borrower's credit history.
Responsible repayment can support a healthy credit profile over time.
However, missed or delayed payments can also negatively affect a borrower's credit record.
6. Useful for Planned Financial Needs
Depending on the loan product and its terms, borrowed funds may help with expenses such as:
- Vehicle-related expenses
- Education
- Household requirements
- Business or work-related needs
- Medical expenses
- Emergency expenses
The borrower should understand the purpose, cost and repayment obligation before taking the loan.
Limitations of Loans for Gig Workers
1. Irregular Income Can Make Repayment Difficult
One of the biggest practical challenges for gig workers is income fluctuation.
Earnings can change because of:
- Number of working hours
- Demand
- Incentives
- Seasonal changes
- Fuel costs
- Platform conditions
- Personal availability
A borrower should calculate affordability using realistic income rather than the highest-earning month.
2. No Traditional Salary Slip
Some gig workers do not receive monthly salary slips.
This can mean that lenders may request alternative documents to verify income.
For example:
- Bank statements
- Platform earnings reports
- Invoices
- Tax records
- Other financial information
Different lenders may have different requirements.
3. Approval Is Not Guaranteed
Being a gig worker does not automatically qualify someone for a loan.
Similarly, having a certain income or credit score does not guarantee approval.
A lender may assess the complete application, including:
- Income
- Credit history
- Existing obligations
- Documentation
- Repayment capacity
- Internal risk policies
4. Loan Costs Can Increase the Overall Repayment
A loan is not limited to the amount received by the borrower.
The overall cost may include applicable:
- Interest
- Processing fees
- Taxes
- Penal charges, where applicable
- Other disclosed charges
For digital lending, borrowers should review the Key Fact Statement (KFS) and APR before accepting an offer.
The RBI's digital lending framework requires regulated entities to provide a KFS and disclose key loan information to borrowers.
5. Existing EMIs Can Reduce Eligibility
A gig worker may already have:
- Two-wheeler EMI
- Vehicle loan
- Personal loan
- Credit card outstanding
- Consumer durable loan
A new loan adds another repayment obligation.
Example
Suppose a gig worker earns an average of ₹30,000 per month and already pays ₹6,000 toward existing EMIs.
A new loan would increase the total monthly repayment obligation.
Therefore, the borrower should evaluate the complete budget before applying rather than looking at the new EMI alone.
Benefits vs Limitations: Quick Comparison
| Benefits | Limitations |
|---|---|
| Access to formal credit | Approval is not guaranteed |
| Digital application convenience | Income may fluctuate |
| Alternative income records may be accepted | Salary slips may not be available |
| Different loan products may be available | Documentation requirements vary |
| Can support certain financial needs | Interest and fees increase repayment cost |
| May contribute to credit history with responsible repayment | Missed payments can affect credit history |
| Online loan information can be reviewed | Digital lending requires lender verification |
Documents Gig Workers May Need
The exact requirements depend on the lender.
However, gig workers should be prepared with documents such as:
Identity Documents
- PAN card
- Aadhaar or other accepted identity document
- Address proof
Financial Documents
- Recent bank statements
- Platform earnings records
- Invoices
- Receipts
- ITR, where applicable
Other Information
- Employment or work history
- Existing loan details
- Bank account information
- Contact details
Keep your documents accurate and up to date.
Credit Score and Gig Worker Loan Eligibility
Credit history can be an important part of a loan assessment.
Before applying:
- Check your credit report.
- Review active loans.
- Check repayment history.
- Identify incorrect information.
- Avoid unnecessary borrowing.
- Pay existing EMIs on time.
There is no single credit-score number that guarantees loan approval for every gig worker.
Each lender can have its own credit assessment process.
Income Proof: What Should Gig Workers Maintain?
Maintaining a clear financial trail can make income verification easier.
Consider keeping:
- Regular bank transaction records
- Platform payment statements
- Digital invoices
- Tax documents
- Records of business-related expenses
- Records from multiple income sources
Simple income tracking example
| Month | Gig earnings |
|---|---|
| January | ₹28,000 |
| February | ₹31,000 |
| March | ₹26,000 |
| April | ₹33,000 |
| May | ₹29,000 |
| June | ₹30,000 |
This type of record gives a better picture of income variation than relying only on the highest monthly earnings.
What Should Gig Workers Check Before Applying?
Use this checklist:
Eligibility
☑ Age requirement
☑ Occupation requirement
☑ Income requirement
☑ Work history
☑ Credit history
Documents
☑ PAN
☑ Identity proof
☑ Address proof
☑ Bank statements
☑ Income records
Loan Costs
☑ Interest rate
☑ APR
☑ Processing fee
☑ Taxes and other applicable charges
☑ Total repayment
Safety
☑ Actual lender identified
☑ KFS reviewed
☑ Loan agreement read
☑ Official website/app verified
☑ No OTP/PIN/password shared
Digital Loan Safety for Gig Workers
Digital lending can be convenient, but borrowers should verify the platform before submitting personal and financial information.
The RBI has created a public directory of Digital Lending Apps (DLAs) reported by regulated entities to help customers verify an app's claimed association with a regulated entity. The RBI also advises customers to check the association through the regulated entity's website and avoid downloading loan apps received through SMS or social-media links.
Follow these precautions:
- Use the official lender website or verified application.
- Identify the actual bank or NBFC providing the loan.
- Read the KFS.
- Check the APR and applicable charges.
- Do not share OTPs.
- Never share UPI PINs or banking passwords.
- Avoid making payments to personal accounts.
- Keep copies of important loan documents.
- Check the lender's grievance-redressal details.
What Is the Role of a Loan Platform Like Vizzve?
A loan platform can help borrowers discover and compare available loan offers from lending partners.
According to Vizzve's website, Vizzve Financial connects borrowers with multiple banks and NBFCs and presents loan offers through its platform. The actual lender, eligibility criteria, interest rate and loan terms can vary by offer.
For a gig worker, a platform can potentially simplify the process of exploring loan options, but the borrower should still identify the actual lender and review the complete loan terms before accepting an offer.
Important: Vizzve itself does not make every loan decision. Loan approval and terms are subject to the relevant lender's eligibility and assessment.
Vizzve Financial: Exploring Loan Options
Vizzve Financial can be used to explore available loan options and application information.
According to its official website, Vizzve works with banks and NBFCs and allows users to view loan offers through its platform.
Before accepting any offer:
- Check the actual lender.
- Review the loan amount.
- Compare the APR.
- Check the EMI.
- Review the tenure.
- Read the KFS.
- Understand processing fees and other charges.
- Confirm repayment terms.
Vizzve's website also warns users not to pay representatives in cash or to personal accounts and advises using official Vizzve channels.
Step-by-Step Guide: How Gig Workers Can Prepare for a Loan
Step 1: Calculate Your Average Income
Review several months of income rather than using one high-income month.
Step 2: List Existing EMIs
Write down all current monthly repayments.
Step 3: Check Your Credit Report
Look for repayment issues or incorrect information.
Step 4: Decide the Required Loan Amount
Borrow based on the actual financial requirement.
Step 5: Prepare Documents
Keep KYC, bank and income-related records ready.
Step 6: Compare Offers
Compare interest rate, APR, EMI, tenure and fees.
Step 7: Verify the Lender
Find out which bank or NBFC is actually providing the loan.
Step 8: Read the KFS
Review key loan terms before accepting.
Step 9: Check Repayment Affordability
Make sure the EMI remains manageable during lower-income periods.
Step 10: Apply Through an Official Channel
Use the verified lender or platform website/application.
Example of Loan Affordability
Consider a hypothetical gig worker:
| Financial detail | Amount |
|---|---|
| Average monthly earnings | ₹32,000 |
| Work-related expenses | ₹5,000 |
| Existing EMI | ₹4,000 |
| Essential expenses | ₹14,000 |
| Amount remaining before new EMI | ₹9,000 |
The ₹9,000 balance should not automatically be treated as an affordable EMI limit.
The borrower should also consider:
- Emergency savings
- Income fluctuations
- Medical expenses
- Family obligations
- Fuel and work expenses
- Unexpected financial commitments
This example is for illustration only and is not a lender's eligibility formula.
Pros and Cons of Loans for Gig Workers
Pros
- Access to formal credit
- Convenient digital application options
- Alternative income records may be accepted
- Potential access to different loan products
- Can help meet eligible financial requirements
- Responsible repayment can contribute to credit history
Cons
- Variable income can make repayment challenging
- Some lenders may have strict documentation requirements
- Interest and fees increase the total cost
- Existing debt can reduce borrowing capacity
- Approval is not guaranteed
- Unverified digital lending apps can create financial and privacy risks
Expert Perspective: Borrow Based on Stable Repayment Capacity
For gig workers, the most important question is not simply “How much loan can I get?”
A better question is:
“How much EMI can I realistically manage even when my income is lower than usual?”
Maintaining consistent income records, reviewing credit history and understanding total borrowing costs can help create a more realistic picture of affordability.
A responsible borrowing approach should consider both the best and weaker income periods.
Key Takeaways
- Gig workers in Karnataka can explore loans subject to individual lender requirements.
- Income consistency and verifiable financial records can be important.
- A salary slip is not necessarily the only form of income documentation.
- Credit history and existing EMIs can affect loan assessment.
- A loan provides funds but also creates a repayment obligation.
- Compare APR, interest, fees and total repayment instead of focusing only on EMI.
- Read the KFS and loan agreement before accepting an offer.
- Verify the actual bank or NBFC behind a digital loan.
- Never share OTPs, PINs or passwords.
- Use official websites and applications.
- Borrow only an amount that fits your realistic repayment capacity.
Frequently Asked Questions
1. Can gig workers in Karnataka get a personal loan?
Gig workers may apply for personal loans if they meet the eligibility requirements of the selected lender. Approval depends on the lender's assessment.
2. Is a salary slip mandatory for gig workers?
Not necessarily. Some lenders may accept alternative income records, such as bank statements or platform earnings statements. Requirements differ.
3. What documents can gig workers use as income proof?
Depending on the lender, documents may include bank statements, platform earnings reports, invoices, receipts or income-tax records.
4. Does credit score affect gig worker loan eligibility?
Credit history can be considered during loan assessment. However, there is no single credit-score threshold that applies to every lender.
5. Can delivery partners apply for personal loans?
Delivery partners can apply if they satisfy the selected lender's eligibility requirements and provide the required information and documents.
6. Can drivers working with ride-hailing platforms apply for loans?
Drivers may apply for loans, subject to lender-specific income, documentation, credit and repayment requirements.
7. What are the main benefits of a gig worker loan?
Potential benefits include access to formal credit, digital application convenience and the possibility of using alternative income documentation where accepted.
8. What are the main limitations?
Variable income, documentation requirements, existing debt, loan costs and lender-specific eligibility criteria can be important limitations.
9. Does irregular income reduce loan eligibility?
It can affect how repayment capacity is assessed. Maintaining consistent and verifiable financial records can help demonstrate the income pattern.
10. Can gig workers apply without a traditional employer?
Yes, gig workers can apply for suitable loan products, but the lender may require evidence of income and work activity.
11. Should I borrow the maximum amount offered?
Not necessarily. The amount borrowed should be based on the actual financial requirement and realistic repayment capacity.
12. What is APR?
APR, or Annual Percentage Rate, is an annualised measure used to communicate the cost of a digital loan based on applicable rules. Review it along with the KFS and other charges.
13. What is a KFS?
A Key Fact Statement is a standardised document containing important information about a loan, helping borrowers understand key terms and costs before accepting the loan.
14. How can I verify a digital lending app?
Check the app's association with the relevant regulated bank or NBFC through official channels and use the RBI's available DLA directory for verification assistance.
15. Does Vizzve guarantee loan approval?
No. Loan approval and terms depend on the applicable lender's eligibility criteria and assessment. Vizzve's official website describes its service as connecting borrowers with multiple banks and NBFCs.
Conclusion
Loan eligibility for gig workers in Karnataka can provide access to formal credit, but it also comes with important limitations.
Gig workers should pay particular attention to income stability, documentation, credit history, existing EMIs and total loan costs. Digital applications can make the process more convenient, but borrowers should always verify the actual lender and read the KFS before accepting an offer.
Published on : 2nd October
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed