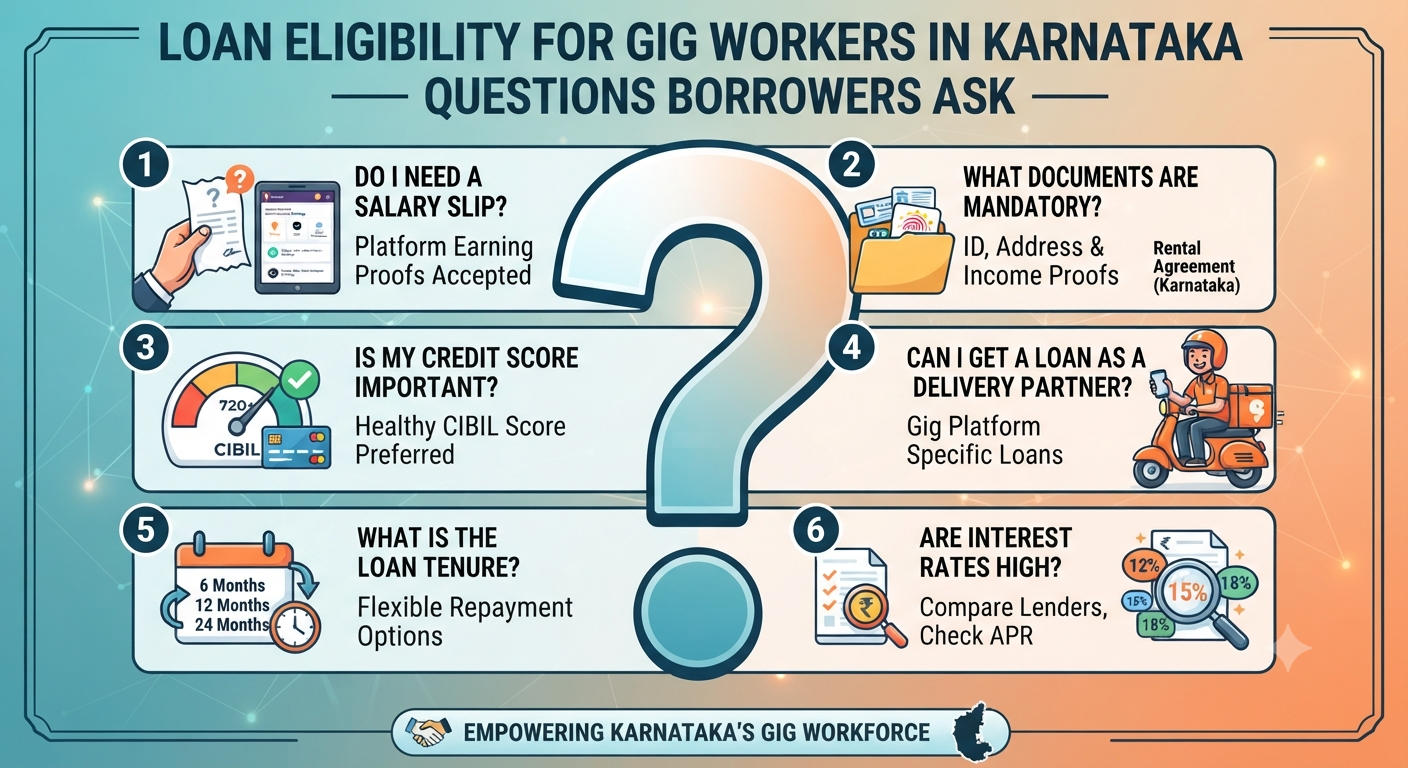
Loan Eligibility for Gig Workers in Karnataka — Questions Borrowers Ask
Vizzve Admin
Gig work has become an important source of income for many people in Karnataka. Delivery partners, cab drivers, freelancers, online sellers, home-service professionals and independent workers may earn regularly without receiving a traditional monthly salary.
This often leads to questions such as:
Can gig workers get personal loans?
What documents are required?
Can bank statements prove gig income?
Does a credit score matter?
How much loan can a gig worker get?
The answers depend on the lender, loan product and applicant's financial profile. There is no single eligibility rule applicable to every gig worker.
This guide answers the most common questions borrowers may have before applying for a loan.
AI Answer Box: Loan Eligibility for Gig Workers in Karnataka
Gig workers in Karnataka may be eligible for personal loans if they meet the lender's requirements. Depending on the lender, eligibility may be assessed using income records, bank statements, credit history, existing financial obligations, KYC documents and repayment capacity.
Quick Answer
Before applying, gig workers should check:
- Minimum and maximum age requirements
- Income and work history requirements
- Bank statement requirements
- Credit history
- Existing EMIs and debts
- KYC documents
- Acceptable income proof
- Loan amount and tenure
- Interest rate and applicable charges
- Repayment affordability
Important: Approval is not guaranteed simply because an applicant is a gig worker or meets some basic criteria. Final eligibility is determined according to the lender's applicable policies.
What Is a Gig Worker Loan?
A gig worker loan generally refers to credit available to individuals who earn through flexible, independent or project-based work.
Common examples include:
- Food delivery partners
- E-commerce delivery workers
- Cab and auto drivers
- Freelancers
- Online tutors
- Independent consultants
- Home-service professionals
- Beauty professionals
- Online sellers
- Digital creators
- Part-time service providers
Unlike salaried employees, gig workers may receive payments from multiple sources or experience changing monthly income.
For this reason, lenders may use different documents to assess income and repayment capacity.
Why Do Gig Workers Have Questions About Loan Eligibility?
The traditional loan application process often focuses on salaried employment.
A salaried applicant may have:
- Salary slips
- Employer records
- Form 16
- Regular salary credits
A gig worker may instead have:
- Platform earnings
- Bank transactions
- Invoices
- Tax records
- Payment receipts
- Business income
- Multiple income sources
The exact evidence accepted varies by lender.
Frequently Asked Questions About Gig Worker Loans
1. Can gig workers get personal loans in Karnataka?
Yes, gig workers may qualify for personal loans if they meet the eligibility criteria of the relevant lender.
The lender may consider factors such as income, credit history, documentation, existing obligations and repayment capacity.
2. Can I get a personal loan without a salary slip?
Possibly.
Some lenders may accept alternative income documentation from self-employed or gig workers.
Depending on the lender, this could include:
- Bank statements
- Income records
- Platform earnings
- Tax documents
- Invoices
- Other acceptable financial records
Always check the lender's current documentation requirements.
3. What documents do gig workers need for a loan?
Requirements vary, but commonly requested documents can include:
| Document |
Purpose |
| PAN |
Identity and financial verification |
| Aadhaar/accepted ID |
KYC verification |
| Address proof |
Residential verification |
| Bank statements |
Financial activity and income assessment |
| Income documents |
Income verification |
| Platform records |
Evidence of gig earnings |
| Tax records |
Financial documentation where applicable |
Not every lender will require every document listed above.
4. Can delivery partners apply for personal loans?
Delivery partners may apply for personal loans if they satisfy the lender's eligibility conditions.
Maintaining clear records of delivery-platform earnings and bank transactions can help demonstrate the applicant's financial activity.
5. Can cab drivers get personal loans?
Cab and auto drivers may qualify for loans depending on lender requirements.
Potentially relevant information can include:
- Bank transactions
- Driving or platform income
- Work history
- Existing liabilities
- Credit history
- KYC documents
6. Can freelancers apply for loans?
Yes, freelancers may apply for loan products for which they meet the lender's eligibility requirements.
Because freelancers may receive payments from different clients, maintaining organized financial records can be useful.
7. Does credit score matter for gig workers?
Credit history can be an important part of a lender's assessment.
A credit profile may reflect previous borrowing and repayment behaviour.
However, credit score is not necessarily the only factor considered. Lenders may also assess income, existing debt, documentation and other eligibility criteria.
8. How can I prove my gig income?
The acceptable method depends on the lender.
Potential forms of evidence can include:
- Bank statements
- Platform payment records
- Invoices
- Tax documents
- Payment receipts
- Other financial records accepted by the lender
Keeping records consistently can make the income-verification process easier.
9. Does variable income reduce loan eligibility?
Variable income can affect how a lender assesses repayment capacity.
For example, a gig worker may earn ₹35,000 in one month and ₹22,000 in another.
Instead of planning an EMI around the highest monthly income, borrowers should consider whether the EMI remains affordable during lower-income periods.
10. How much personal loan can a gig worker get?
There is no single amount that applies to all gig workers.
The amount offered can depend on factors such as:
- Income
- Credit profile
- Existing EMIs
- Repayment capacity
- Loan tenure
- Lender policies
- Documentation
The maximum eligible amount is not necessarily the amount a borrower should take.
11. Can I apply for a loan if I already have an EMI?
Possibly.
However, the lender may consider existing financial obligations when assessing repayment capacity.
Before taking another loan, calculate:
Existing monthly obligations + proposed new EMI = total monthly debt payments
Make sure the resulting payment fits comfortably within your realistic income.
12. Does working for a delivery or ride-hailing platform guarantee loan approval?
No.
Working with a particular platform does not automatically guarantee loan approval.
The lender may evaluate several factors before making a lending decision.
13. Can gig workers with multiple income sources apply for loans?
Potentially, yes.
Applicants should accurately disclose income according to the lender's application requirements and provide supporting documentation where required.
Do not exaggerate income to obtain a higher loan amount.
14. How long should I have been working as a gig worker before applying?
There is no universal minimum period for every lender.
Some lenders may have specific work-history or income-history requirements.
Check the current eligibility conditions of the lender before applying.
15. Can gig workers apply online?
Some lenders and lending platforms provide online application processes.
Before submitting personal information online, verify:
- The website or application
- The actual lender
- Privacy information
- Loan terms
- Applicable charges
- Customer-support details
Loan Eligibility Factors at a Glance
| Eligibility Factor |
What Borrowers Should Understand |
| Age |
Lenders may specify age limits |
| Income |
Income helps assess repayment capacity |
| Work profile |
Lender may assess the nature of earnings |
| Credit history |
Previous repayment behaviour may matter |
| Bank statements |
May help demonstrate financial activity |
| Existing debt |
Current EMIs can affect affordability |
| Documents |
Required documents vary |
| Loan amount |
Should match repayment capacity |
| Tenure |
Longer tenure can change total repayment cost |
| Lender policy |
Eligibility differs between lenders |
Look at several months of earnings rather than one unusually strong month.
Review your credit information before applying.
If you find an error, contact the relevant credit information company or lender through the appropriate process.
Do not base affordability only on the amount offered by the lender.
Calculate whether the proposed EMI remains manageable when income is lower.
No.
Borrowers should verify the actual lender and carefully review the application's terms and disclosures before proceeding.
No. OTPs and other confidential banking credentials should not be shared with unknown people.
Be extremely cautious. Verify any fee through the lender's official documentation and payment channel.
Treat "guaranteed approval" claims cautiously. Legitimate lending decisions depend on the applicable eligibility and underwriting process.

